


Izumi (TSE:8273) drew fresh attention after half-year results on October 13 showed sales of ¥253,907 million and net income of ¥8,426 million, along with an affirmed second quarter-end dividend of ¥15 per share.
Despite the latest earnings and dividend affirmation, Izumi’s share price has softened, with a 30 day share price return of down 7.69% and a 90 day share price return of down 8.71%, while the 1 year total shareholder return is down 6.63%. This points to fading momentum even as the business continues to report incremental progress and tidy up its group structure through the planned subsidiary merger.
Compare Izumi’s recent softness with other retailers that still screen well for quality and value by scanning our curated 14 high quality undervalued stocks list.
Izumi now combines modest earnings progress with a weaker share price and a forecast dividend shaped by the recent stock split. Does that mix still tilt the risk reward in favour of new buyers at this valuation?
Price-to-Earnings of 11.2x: Is it justified?
Izumi closed at ¥912, and on a reported P/E of 11.2x it screens as inexpensive compared with both its own fair P/E estimate and retail peers. That sets up a valuation story where the market price looks cautious even while earnings and margins have been improving from a low base.
The P/E ratio links what investors pay today to the profits the retailer generates per share, which is especially important for a mature chain with steady but not rapid forecasts. For Izumi, this lens matters because earnings are expected to grow 7.16% per year while revenue is projected to rise 2.9% per year, so much of the interest rests on how reliably that profit stream holds up rather than on fast expansion.
On that score, the shares trade at a P/E of 11.2x versus an estimated fair P/E of 14.2x, which implies the multiple could shift higher if the market grows more comfortable with the current earnings quality. The same 11.2x sits well below the JP Multiline Retail industry average of 16.5x and under the peer average of 25.9x, so the market is pricing Izumi at a clear discount compared with comparable retailers rather than paying up for its recent 45% earnings growth and higher net margin of 3% versus 2.1% last year.
Explore the SWS fair ratio for Izumi.
Result: Preferred multiple of Price-to-Earnings of 11.2x (UNDERVALUED)
Still, that discount can quickly look fragile if Izumi experiences weaker consumer traffic in Japan or if its retail peripheral services struggle to cover fixed costs.
Find out about the key risks to this Izumi narrative.
Another view on Izumi using cash flows
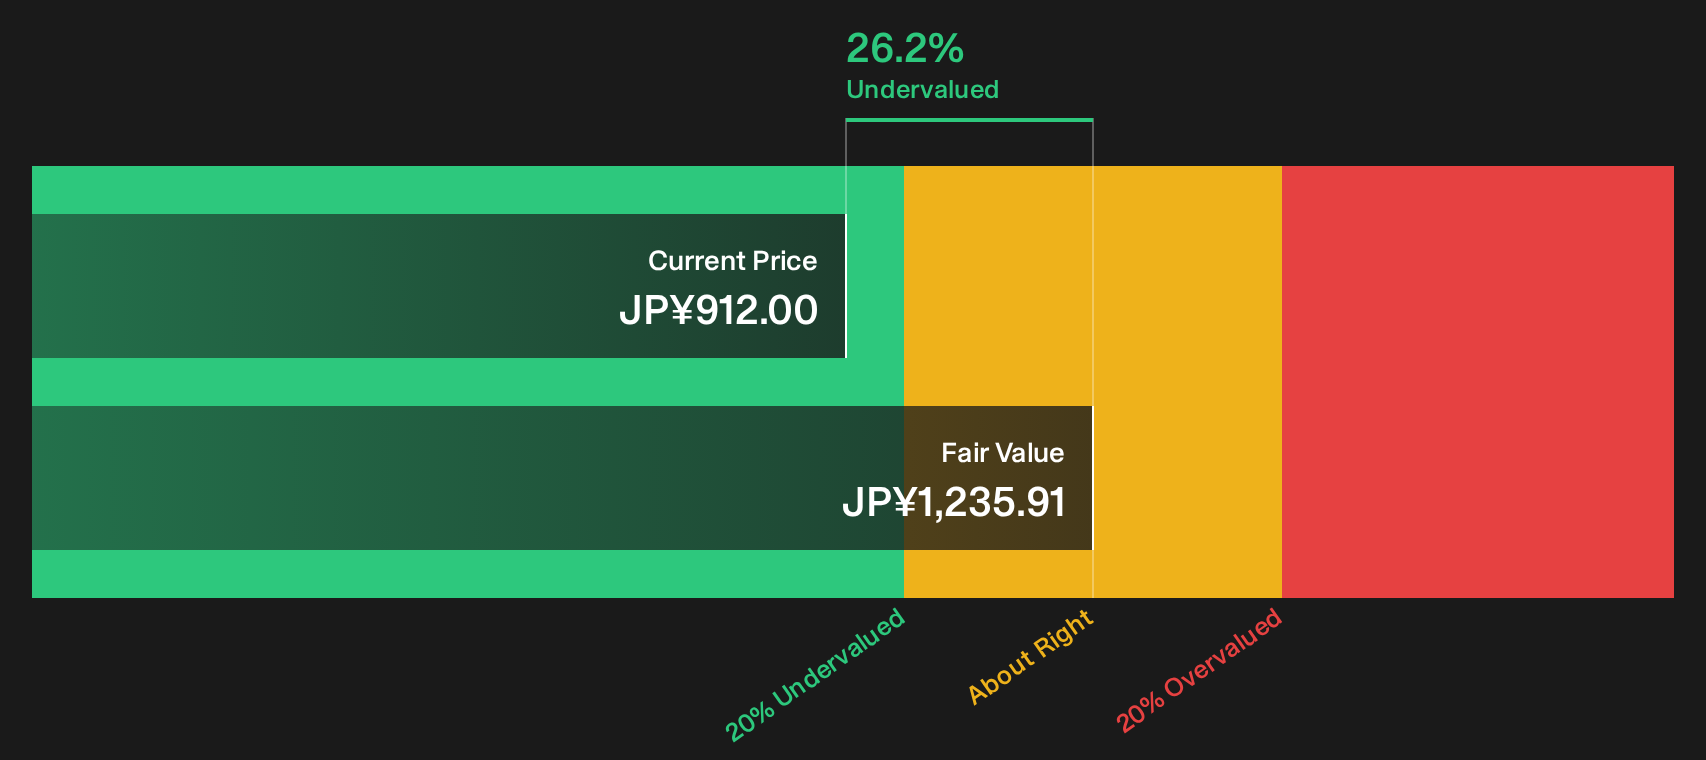
The earnings multiple paints Izumi as inexpensive, yet the SWS DCF model points to something stronger. On that framework, the shares at ¥912 compare with an estimated future cash flow value of ¥1,235.91, which signals undervaluation based on long term cash generation rather than near term earnings alone.
This gap between price and modeled cash flows can look like an opportunity if Izumi keeps converting profits into cash. It also raises the question of what might close that gap and on what timeline for investors.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Izumi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Izumi is mixed, with clear upside signs sitting alongside issues that could trip up the story. Investors should move quickly and test the numbers against their own expectations. To see both sides of that ledger in one place, review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Izumi?
If Izumi has your attention but you want a wider watchlist, use the Simply Wall Street Screener to spot fresh opportunities before they move.
- Target reliable yield hunters by scanning for income ideas in the 29 dividend fortresses that match your dividend and payout preferences.
- Hunt for strong fundamentals with less balance sheet stress using the list of solid balance sheet and fundamentals (22 results) to focus on sturdier financial profiles.
- Unearth underfollowed opportunities by running the 73 high quality undiscovered gems and see which quieter tickers still line up with solid metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com