


General Mills has seen a sharp reset in investor sentiment over the past few years, and that slide puts fresh focus on whether the current share price still lines up with the sales the business generates.
- The stock is down 38.0% over the past three years, which puts pressure on the question of how much investors are now willing to pay for each dollar of General Mills' revenue.
- The group leans heavily on steady packaged food demand and established brands, which can support relatively predictable sales but still leaves open how those sales should be valued when growth expectations are muted.
- There is a second opinion on General Mills worth weighing. See what analysts think General Mills's shares could be worth.
For investors, the key question is whether General Mills' current market value is adequately grounded in its sales profile or asking too much of it.
If you are weighing whether General Mills still fits your portfolio after that 38.0% three year slide, it can help to compare it with a focused list built around 30 high quality undervalued stocks.
Does General Mills Look Fairly Valued on Sales?
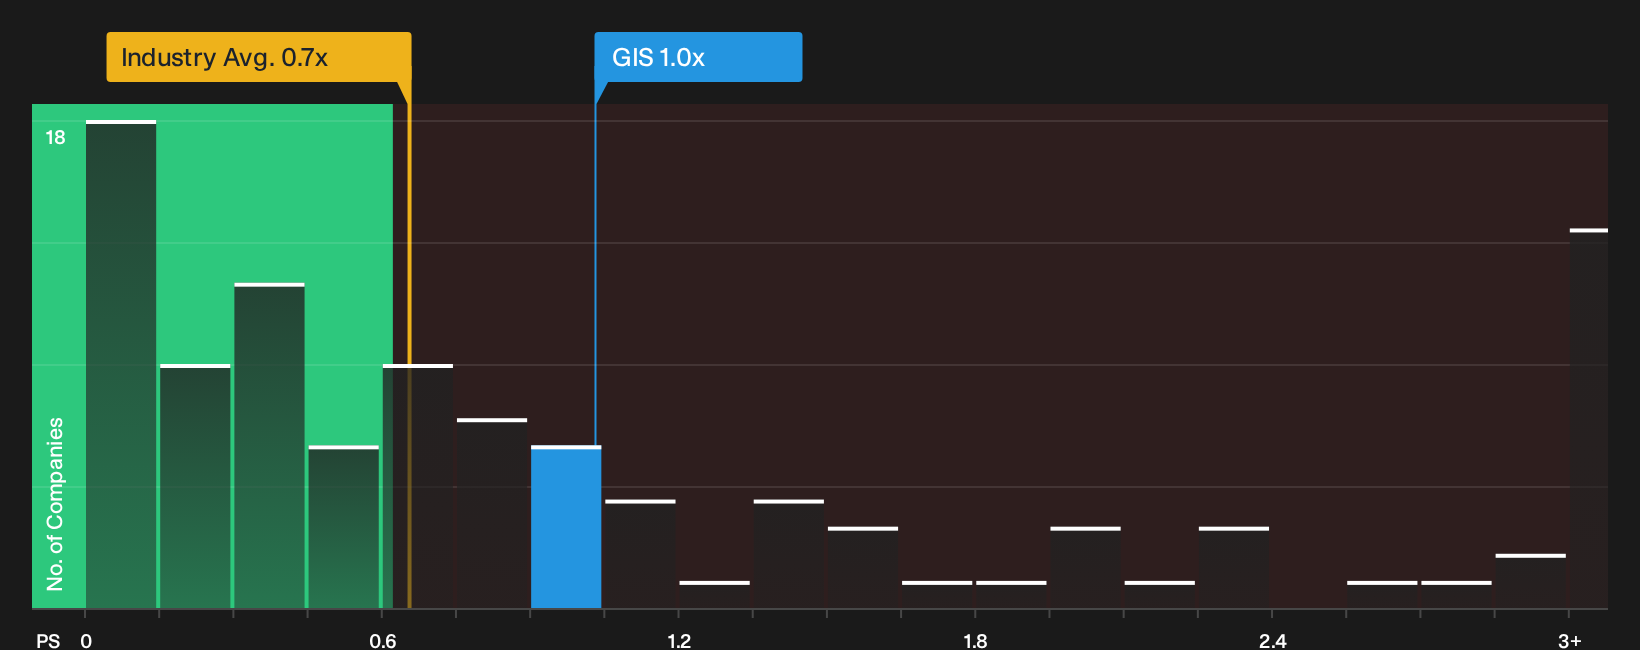
P/S is a useful lens for General Mills because investors often focus on its ability to convert steady supermarket shelf space into recurring revenue. On that measure, the stock trades on a P/S of 1.0x, which is slightly above the Food industry average of 0.7x and also ahead of the peer group at 0.8x. That indicates the market is paying a modest premium for each dollar of General Mills' sales compared with many packaged food rivals.
A tailored fair-value model that blends the company’s growth profile, margins, scale and risk suggests a P/S level close to where General Mills currently trades. The current ratio sits very near that reference point, so the multiple on its own does not lean strongly toward the stock being either clearly cheap or clearly expensive. Instead, the decision rests on how much weight you place on the durability of its brands and cash generation. Explore the numbers behind General Mills's P/S valuation.
The General Mills Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the General Mills valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. These Narratives sit on the platform’s Community page and each one turns General Mills' implied fair value into a clear, testable view on the business so you can watch how that idea holds up over time.
Community views on General Mills split between cost savings supporting a steadier story and spending and complexity keeping the risk skewed the other way.
Bull case: 7% undervalued
"General Mills plans to deliver US$750 million of cost savings in fiscal 2027 as part of a US$3 billion program through fiscal 2030..."
Discover why this Narrative puts General Mills at 7% undervalued.
Bear case: 17% overvalued
"The heavy emphasis on remarkability investments, including a double digit increase in media spend and higher SG&A, risks locking General Mills into structurally higher overhead..."
Explore why this Narrative puts General Mills at 17% overvalued.
One last General Mills check before you stop at price
Valuation only tells part of the story for General Mills, because the research also flags specific risk checks that could change how you view that sticker price once you see them. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com