


As European markets navigate the complexities of geopolitical tensions and fluctuating energy prices, the pan-European STOXX Europe 600 Index has shown resilience, advancing by 2.09% in local currency terms. Amid this backdrop, identifying stocks with robust fundamentals becomes crucial for investors seeking stability and potential growth opportunities in a dynamic environment.
Top 10 Undiscovered Gems With Strong Fundamentals In Europe
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apator | 13.65% | 6.21% | 20.01% | ★★★★★★ |
| B&C Speakers | 39.08% | 14.82% | 13.88% | ★★★★★★ |
| Angler Gaming | NA | -4.50% | -4.71% | ★★★★★★ |
| innoscripta | 30.37% | 42.47% | 38.04% | ★★★★★☆ |
| Proact IT Group | 55.08% | 4.63% | 6.21% | ★★★★★☆ |
| Byggmax Group | 3.28% | -5.41% | -33.83% | ★★★★★☆ |
| Edel SE KGaA | 142.35% | 1.36% | 12.24% | ★★★★☆☆ |
| Volati | 103.38% | 4.10% | -12.97% | ★★★★☆☆ |
| SP Group | 83.41% | 5.40% | 9.36% | ★★★★☆☆ |
| Lea Bank | 14.47% | -7.37% | -27.19% | ★★★★☆☆ |
Here's a peek at a few of the choices from the screener.
Alligo (OM:ALLIGO B)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Alligo AB (publ) operates in Sweden, Norway, and Finland, offering workwear, personal protection items, tools, and consumables with a market capitalization of approximately SEK6.25 billion.
Operations: Alligo generates revenue primarily from its wholesale segment, specifically machinery and industrial equipment, amounting to SEK9.82 billion. The company's financial performance is influenced by its ability to manage costs within this segment effectively.
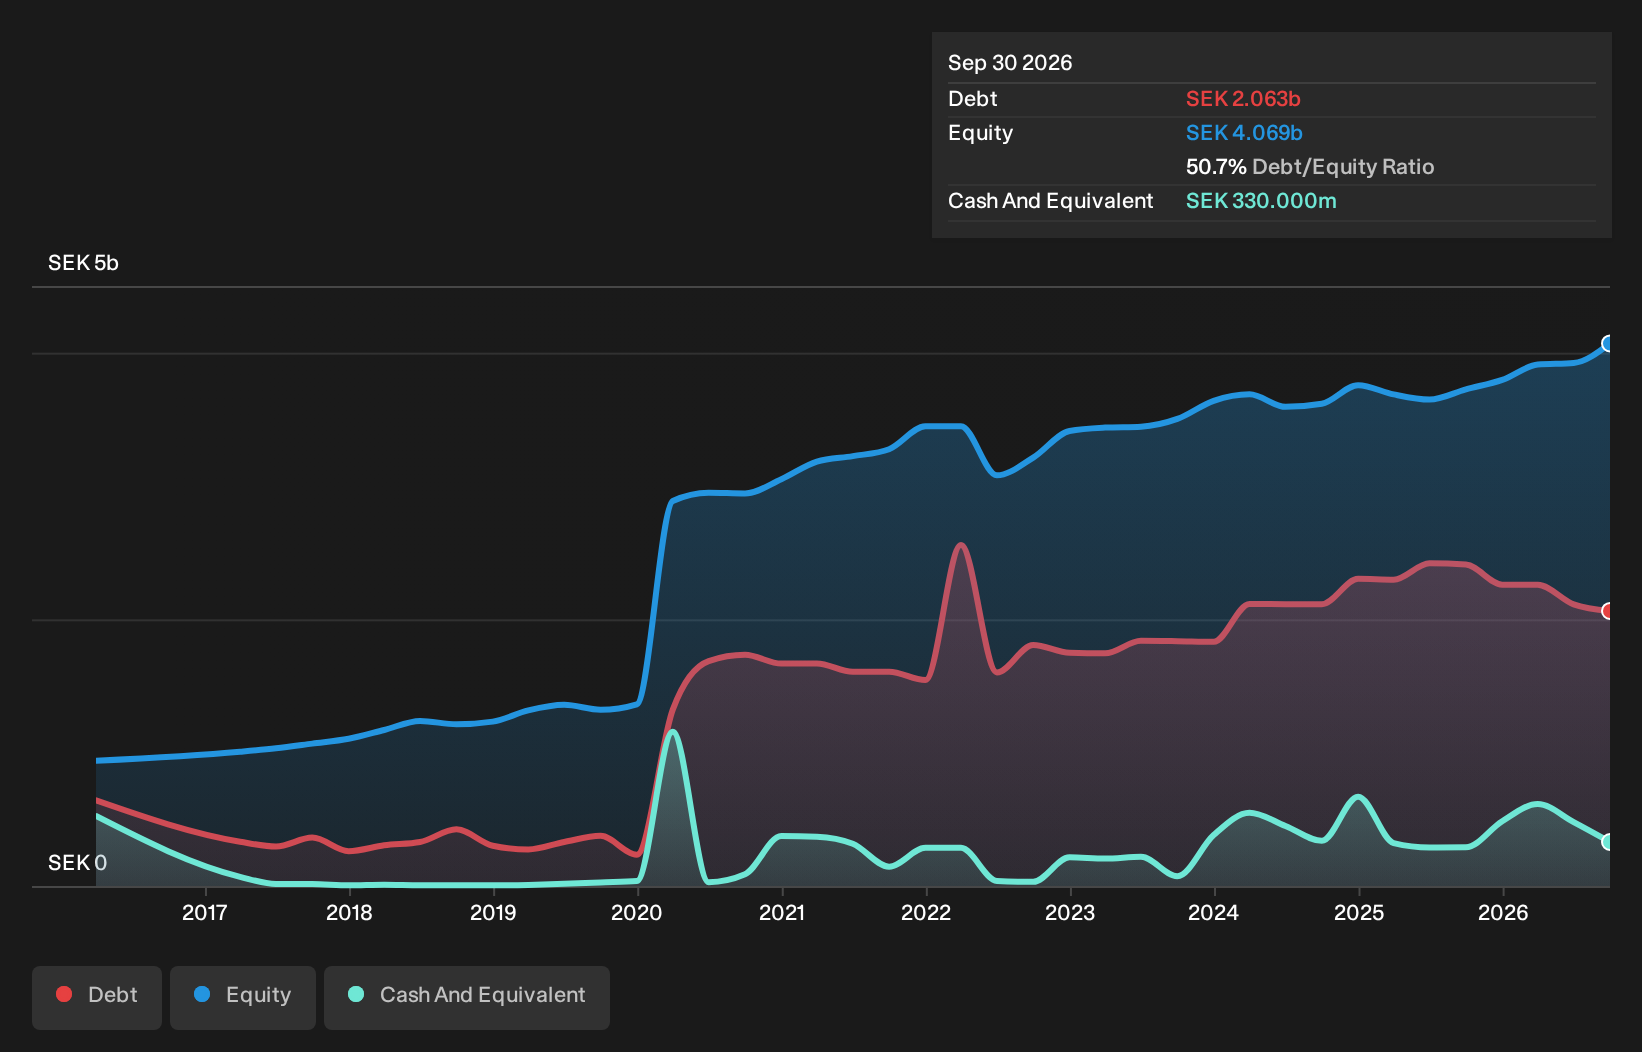
Alligo, a dynamic player in the Trade Distributors industry, has seen its earnings grow by 51.5% over the past year, outpacing the sector's 17.7% increase. Despite a high net debt to equity ratio of 41.6%, Alligo's interest payments are well covered with EBIT at 5.2 times interest obligations, indicating robust financial health. The company seems undervalued as it trades at 70% below its estimated fair value and maintains high-quality earnings alongside positive free cash flow figures like A$1.12 billion recently reported for levered free cash flow in June 2026, suggesting strong operational efficiency despite increased debt levels over five years from 49.8% to 53.8%.
- Unlock comprehensive insights into our analysis of Alligo stock in this health report.
Explore historical data to track Alligo's performance over time in our Past section.
Proact IT Group (OM:PACT)
Simply Wall St Value Rating: ★★★★★☆
Overview: Proact IT Group AB (publ) is a company that offers data and information management services, including cloud services and data center solutions, across Sweden, the United Kingdom, the Netherlands, Germany, and internationally with a market cap of SEK3.74 billion.
Operations: Proact IT Group generates revenue primarily through its data and information management services, including cloud services and data center solutions. The company's financials indicate a focus on expanding its service offerings across various international markets. Key financial metrics include a market cap of SEK3.74 billion, reflecting its position in the industry.
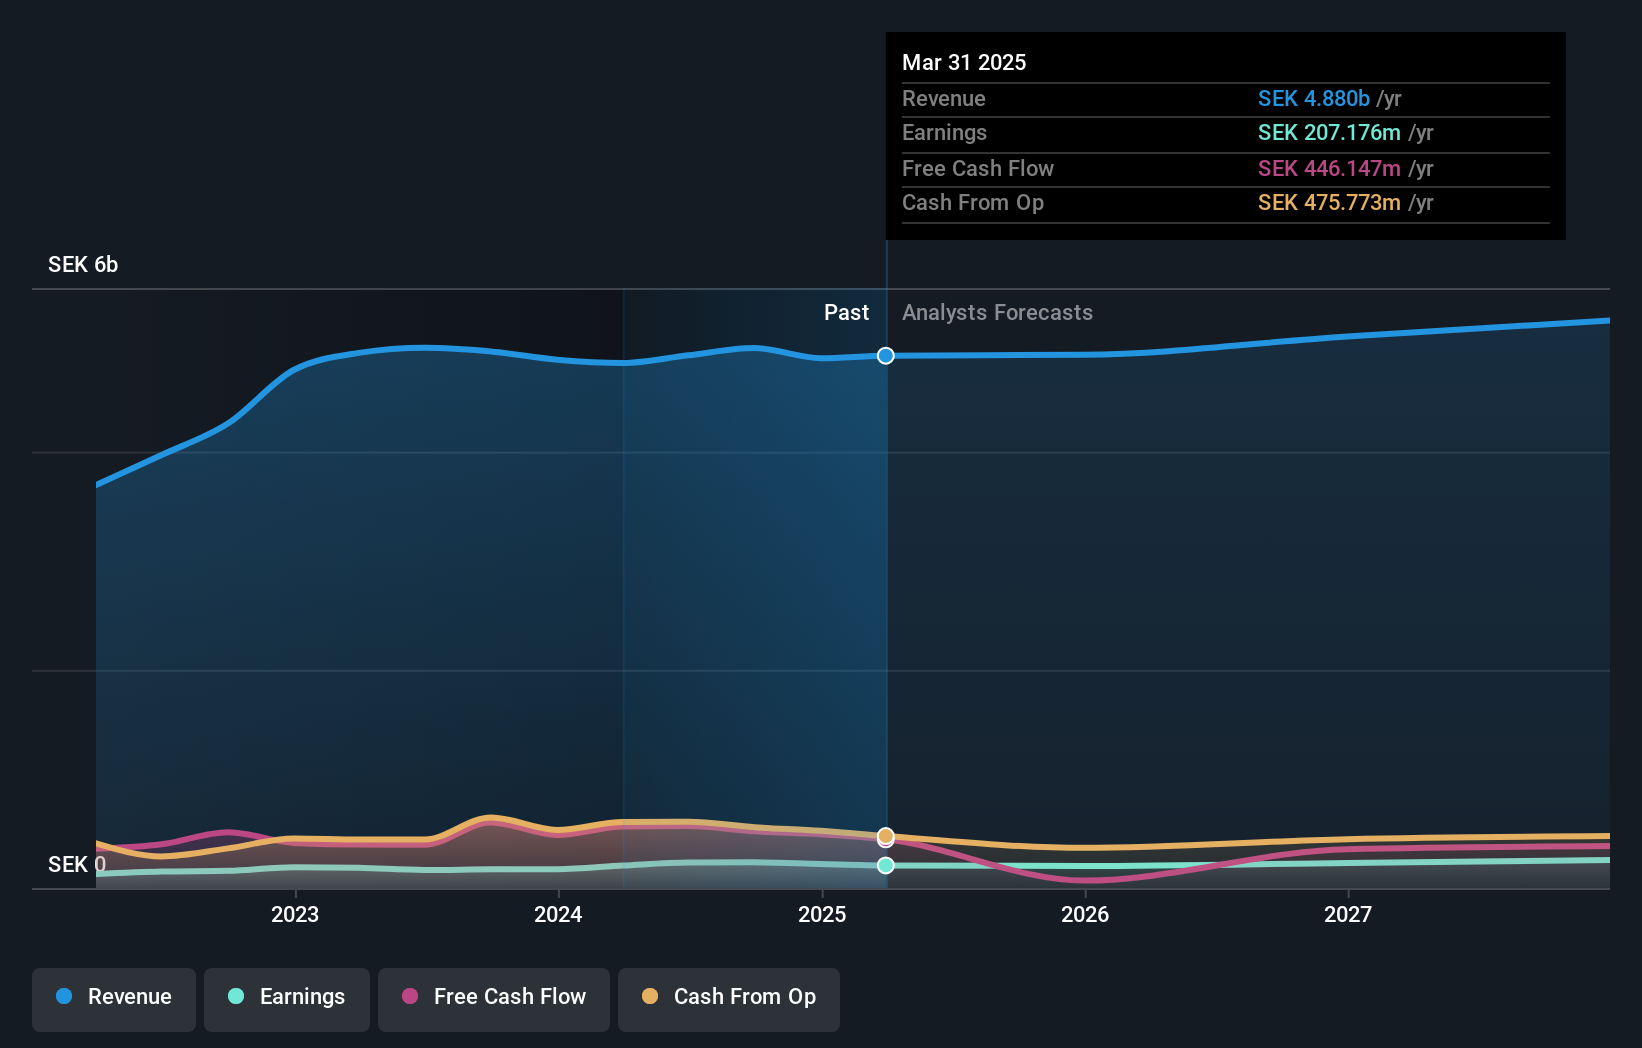
Proact IT Group, a noteworthy player in the European IT sector, has seen its earnings grow by 47.3% over the past year, outpacing the industry average of -2.1%. The company trades at 37.2% below its estimated fair value and maintains a satisfactory net debt to equity ratio of 9.2%. Recent financials show robust performance with third-quarter revenue reaching SEK 1,180 million compared to SEK 1,084 million last year, while net income jumped to SEK 80 million from SEK 37 million. Proact's strategic leadership changes seem poised to drive further growth and strengthen regional operations in Central Europe.
- Delve into the full analysis health report here for a deeper understanding of Proact IT Group.
Understand Proact IT Group's track record by examining our Past report.
Phoenix Mecano (SWX:PMN)
Simply Wall St Value Rating: ★★★★★★
Overview: Phoenix Mecano AG is a global manufacturer and seller of industrial components, operating through its subsidiaries, with a market capitalization of CHF399.65 million.
Operations: Phoenix Mecano AG generates revenue primarily from its Dewertokin Technology Group (€344.18 million), Enclosure Systems (€218.82 million), and Industrial Components (€199.05 million) segments.
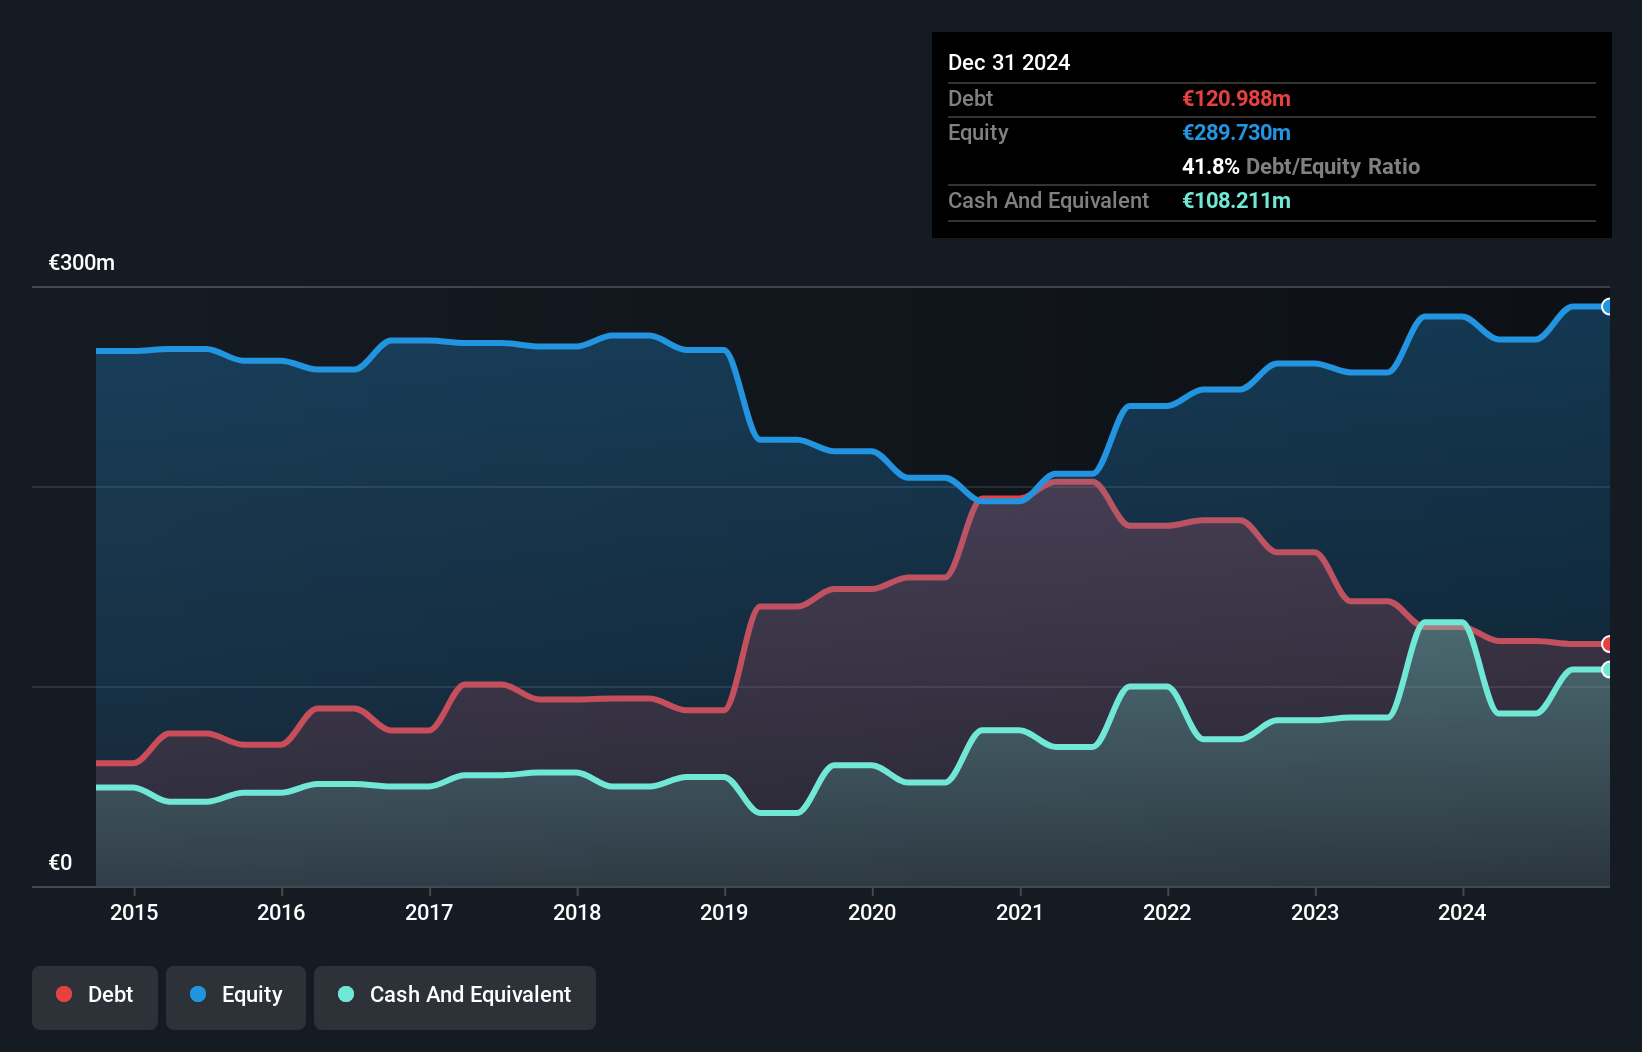
Phoenix Mecano, a relatively small player in the industry, has shown a commendable reduction in its debt to equity ratio from 98.1% to 54.2% over five years, indicating stronger financial health. Trading at nearly half of its estimated fair value suggests it might be undervalued compared to peers. The company’s interest payments are comfortably covered by EBIT with a coverage ratio of 10.6 times, showing solid operational performance. Despite recent negative earnings growth of -1.3%, which trails the industry average slightly, Phoenix Mecano recorded an increase in net income to €14.5 million for H1 2026 from €13.9 million last year, hinting at potential resilience and recovery prospects moving forward.
- Click here and access our complete health analysis report to understand the dynamics of Phoenix Mecano.
Examine Phoenix Mecano's past performance report to understand how it has performed in the past.
Seize The Opportunity
- Gain an insight into the universe of 38 European Undiscovered Gems With Strong Fundamentals by clicking here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com