


Why Saputo's recent trade and portfolio moves matter now
Washington’s tougher stance on Canadian dairy access, Saputo (TSX:SAP) selling select overseas operations, and higher margin U.S. volumes have combined into a fresh catalyst that puts the stock back under the microscope.
Recent performance reflects that mixed backdrop. Saputo’s share price shows only modest short term momentum with a 30 day share price return of 2.5%. However, the 1 year total shareholder return of 21.3% and 3 year total shareholder return of 61% indicate that longer term holders have been rewarded as the portfolio reshaping and U.S. earnings improvement have filtered through.
Scan how Saputo compares to other dairy and food producers by reviewing our hand picked list of solid balance sheet and fundamentals (7 results) that may hold up better when trade rules shift.
Saputo has already baked some portfolio reshaping and U.S. margin progress into a CA$41.05 share price. The next step is working out whether you are being paid enough today to buy now or wait for a cleaner entry point.
Most Popular Narrative: 12% Undervalued
The most followed narrative on Saputo currently points to a fair value of CA$46.70 against the CA$41.05 last close. This frames the current price as leaving some upside if those assumptions play out.
A stronger balance sheet, with net debt to EBITDA around 1.4x and a target of 2.25x, together with a 5% dividend increase and an expanded share repurchase program of up to about 24 million shares, allows Saputo to step up capital returns while still funding growth projects. These actions can influence earnings per share and support valuation multiples.
See why 28 investors see Saputo as 12% undervalued.
Result: Fair Value of CA$46.70 (UNDERVALUED)
Still, the Saputo story can break if the U.S. whey import ban bites harder than expected, or if rising input costs quietly chip away at those margin ambitions.
Find out about the key risks to this Saputo narrative.
Another View: What Saputo’s P/E Is Telling You
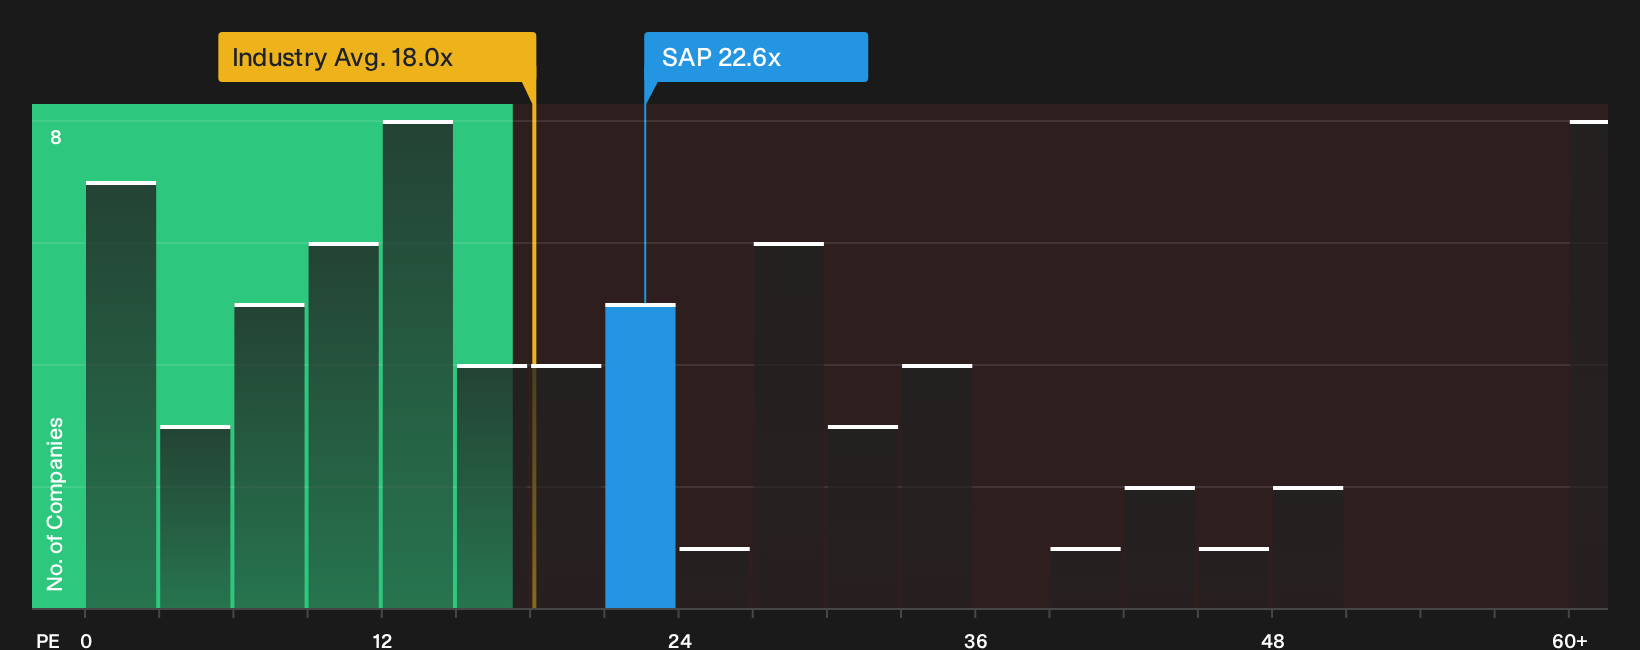
The fair value narrative paints Saputo as 12% undervalued at CA$46.70, yet the market is already paying a P/E of 22.6x. The fair ratio sits lower at 17.6x, while the broader North American Food industry trades near 17.5x and direct peers average a steep 48.2x.
Saputo therefore screens richer than the wider sector but cheaper than closer comparables. This leaves you weighing whether that premium to the industry is justified by its mix and earnings profile, or whether the market could drift toward the lower fair ratio instead.
To stress test that view against hard numbers, zoom out to how the valuation stacks up in detail with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment around Saputo leaves you undecided, consider reviewing the data yourself and testing every assumption, starting with the 3 key rewards
Looking for more Saputo sized investment ideas?
If Saputo has you thinking more broadly about where to put fresh capital, do not stop here. The right watchlist today can shape tomorrow’s outcomes.
- Target resilient compounding potential by scanning a 3 high quality undervalued stocks that blends quality fundamentals with room for sentiment to catch up.
- Prioritise staying power by filtering for 8 resilient stocks with low risk scores that aim to keep portfolio shocks in check when conditions change fast.
- Spot under followed opportunities by reviewing 10 high quality undiscovered gems that many investors have not fully scrutinised yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com