


Space Exploration Technologies has had a busy year on the market and in the headlines, and that mix of share price volatility and bold corporate plans now raises a simple question for you as an investor. Is the current valuation of SpaceX stock meaningfully supported by the company’s book value, or are you paying a large premium to its balance sheet?
- Year to date, the share price has fallen 10.1%, which puts the focus squarely on whether the recent pullback now lines up more closely with the value of assets on SpaceX’s books.
- With management talking up massive AI data center build outs, satellite expansion and even a possible Tesla merger, the scale of required investment could materially affect both future equity needs and the book value base that anchors any valuation using this lens.
- There is a second opinion on Space Exploration Technologies worth weighing. See what analysts think Space Exploration Technologies's shares could be worth.
The issue now is whether Space Exploration Technologies’ current share price looks well anchored when you compare it with its book value against the industry average.
If you are weighing Space Exploration Technologies against other AI heavyweights and capital intensive plays, it helps to see how a wider set of stocks with similar themes screens on fundamentals through our 55 AI infrastructure stocks
Has Space Exploration Technologies Run Too Far on Book Value?
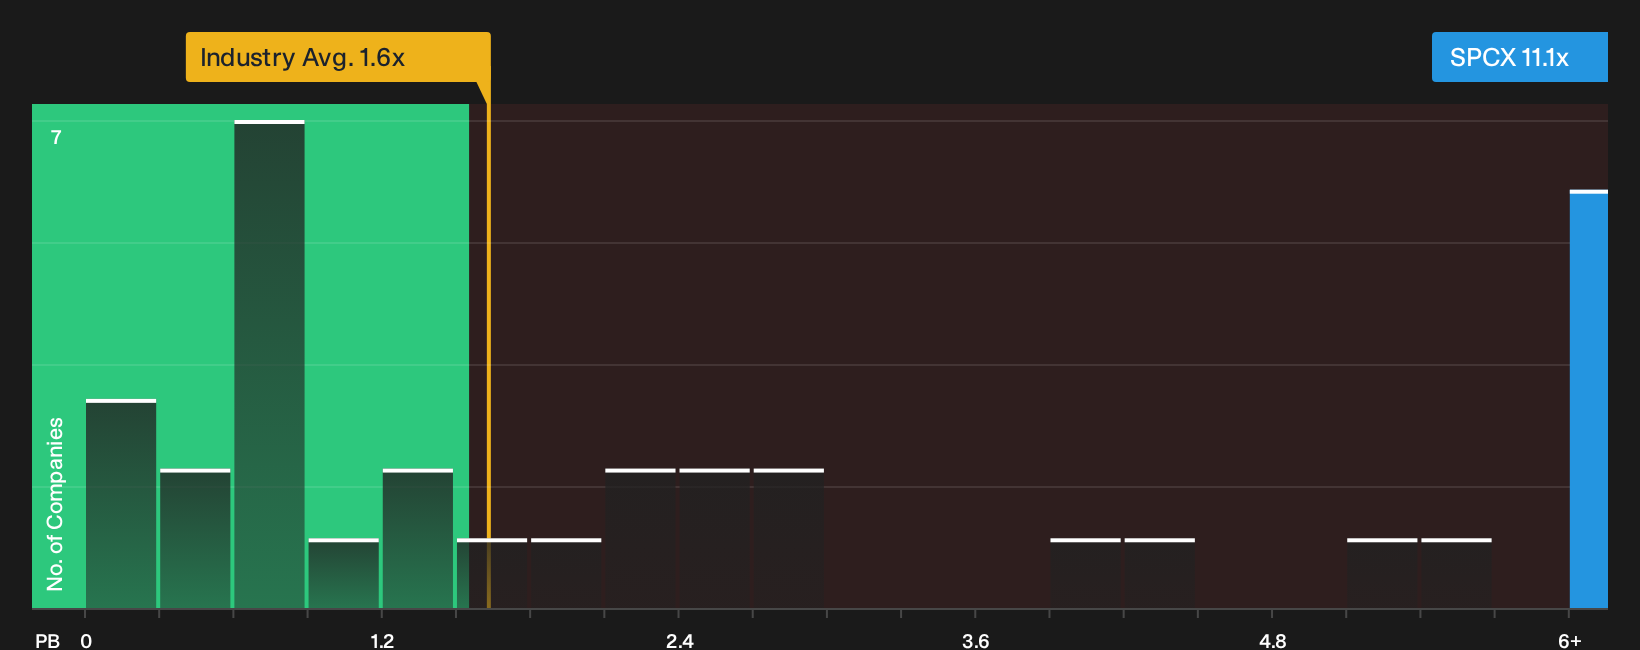
P/B is a useful lens for Space Exploration Technologies because so much of its value is tied up in heavy infrastructure and capital intensive projects. On this measure, the stock trades at about 11.1x book value. That is far above the broader Telecom industry average of 1.6x and still carries a premium to the 13.1x peer group that already prices in high growth and capital needs for similar businesses.
Despite the record 2026 IPO and excitement around AI data centers, Starship and potential Tesla tie ups, this spread suggests investors are paying a substantial uplift relative to both the sector and direct comparables for each dollar of equity on SpaceX’s balance sheet. The model flags this gap as extreme. This means it is heavily penalising the company’s risk profile and volatile cash flows rather than pointing to a precise fair P/B level. For you as a shareholder, the key question is whether that elevated multiple still feels acceptable given the funding demands, regulatory noise and merger speculation surrounding Space Exploration Technologies. Explore the numbers behind Space Exploration Technologies's P/B valuation.
The Space Exploration Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Space Exploration Technologies pick up where this valuation puzzle leaves off and explain which expectations for Space Exploration Technologies' growth, profitability and earnings would need to hold for the stock to be worth meaningfully more or less than today's market price.
Each narrative lays out the assumptions that underpin its view of fair value, so you can track those inputs against the company's reported numbers over time.
Community views on Space Exploration Technologies split between a multi-layer infrastructure thesis and a much more cautious read on current losses.
Bull case: 30% undervalued
"The central thesis has evolved from “Rockets + Starlink” toward a broader infrastructure model..."
Discover why this Narrative puts Space Exploration Technologies at 30% undervalued.
Bear case: 7% overvalued
"Although SpaceX’s revenue is growing steadily, the company as a whole is generating a net loss..."
Explore why this Narrative puts Space Exploration Technologies at 7% overvalued.
One more unresolved piece in the Space Exploration Technologies story
Valuation only tells part of the story for Space Exploration Technologies, because internal checks have also highlighted potential pressure points that could change how you view the risk side of the equation. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com