


Everpure (P) is back in focus after its collaboration with Cisco on the Cisco AI POD with FlashStack, a setup aimed at helping enterprise clients move artificial intelligence projects into full production.
Everpure’s collaboration with Cisco comes after a powerful run in the shares, with the 90-day share price return of 62.55% and year-to-date gain of 75.63% now giving way to a pullback, including a 1-day share price decline of 7.43% and 7-day drop of 9.15%. Long-term holders still see a 3-year total shareholder return of 272.24% and 5-year total shareholder return of 351.06%, so recent volatility looks more like a pause than a break in momentum.
Scan other AI infrastructure opportunities that echo the Everpure story by focusing on the 55 AI infrastructure stocks already filtered for this theme.
Everpure now trades below both analyst targets and an implied intrinsic value, even after that sharp run and pullback. Is the discount a genuine mispricing or a simple warning sign about how much optimism is already in the story?
Most Popular Narrative: 33% Undervalued
Everpure’s most followed narrative pegs fair value at $180 against a last close of $121.20, which points to a sizeable valuation gap that many investors are watching closely.
The market is pricing Everpure as an enterprise storage company. That is the wrong category. Once two or three analysts figure out what is actually happening inside this business, the multiple closes toward AI infrastructure peers, and the stock moves $70 to $80 from here without a single change in fundamentals.
See why 47 investors see Everpure as 33% undervalued.
Result: Fair Value of $180.00 (UNDERVALUED)
Still, this Everpure thesis leans heavily on hyperscale adoption and unusually low churn, and if either assumption fails, the undervaluation story could quickly unwind.
Find out about the key risks to this Everpure narrative.
Another View: Everpure looks expensive on sales multiples
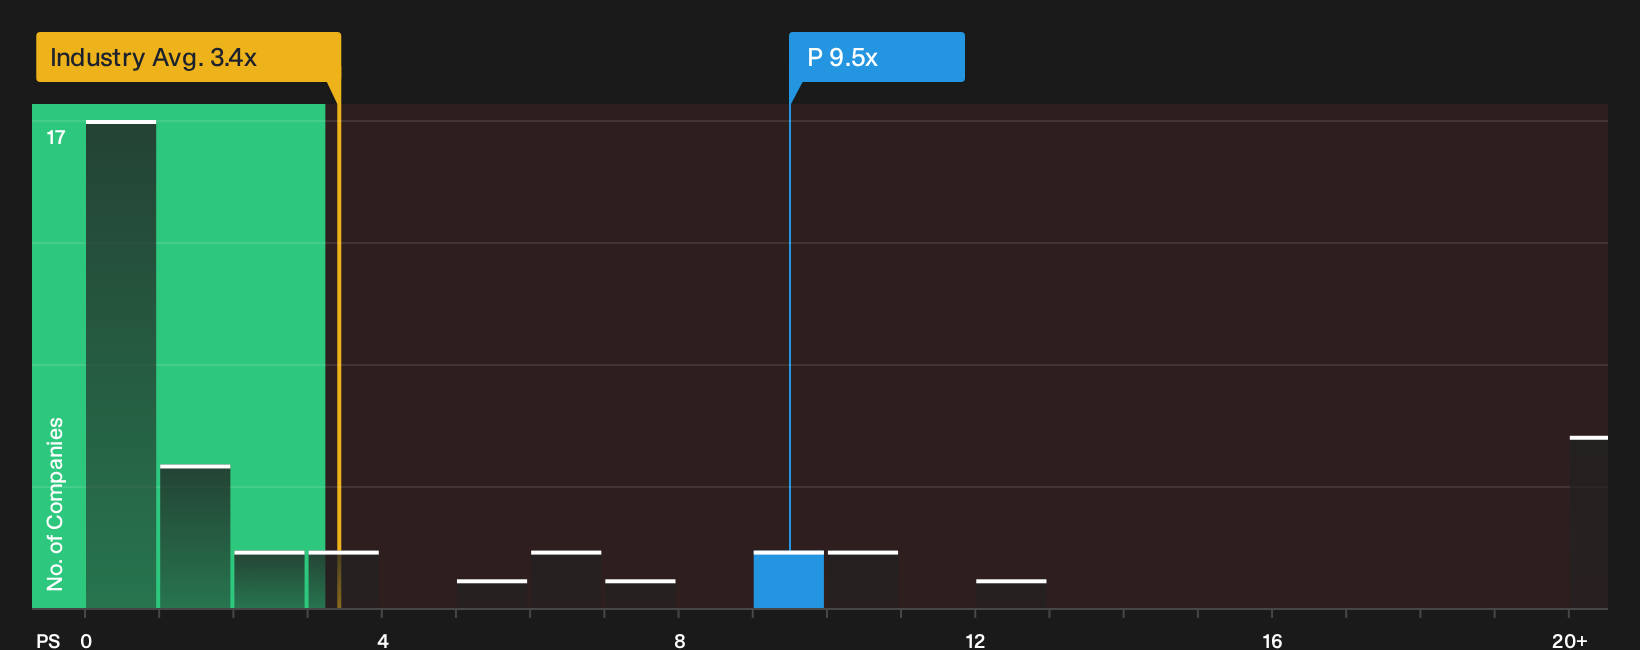
The DCF driven fair value story around Everpure points to a wide discount, yet the simple P/S check tells a different story. At 9.5x sales, the stock trades at almost 3x the wider US Tech sector on 3.4x and over 2x peer averages on 4.5x. That gap raises real questions about how much optimism is already in the price.
For investors who prefer simple ratios over complex models, this kind of rich P/S multiple can either flag overenthusiasm or mark an early read on stronger fundamentals. The only real question is which side of that trade you feel more comfortable underwriting over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between enthusiasm and caution around Everpure after all these numbers and narratives. Act quickly, review the full mix of potential upsides and issues, and ground your stance in the 3 key rewards and 2 important warning signs.
Looking for more Everpure style investment ideas?
If Everpure has you thinking about where the next opportunity might come from, do not stop here. Your next edge often comes from comparing a few very different setups, then deciding where risk and potential returns feel the most aligned with your plan.
- Target potential mispricing by scanning a curated set of high quality companies that appear cheap on fundamentals through the 30 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses with stronger balance sheets and cleaner financial footing using the list of solid balance sheet and fundamentals (26 results).
- Hunt for underfollowed ideas by checking a tighter 20 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com