


Five Below (FIVE) recently reworked its main credit agreement, extending its debt maturity to October 2031 and increasing both its revolving credit facility and letter of credit capacity.
Five Below shares trade at US$225.87 after a 16.8% year-to-date share price gain and an 11.2% 90-day share price return, while the 1-year total shareholder return of 43.8% points to strong longer-term momentum as the expanded credit facility reshapes how investors view its growth capacity and balance sheet risk.
Scan for other retailers with similar balance sheet flexibility and potential growth firepower by reviewing our hand picked list of solid balance sheet and fundamentals (26 results) alongside Five Below.
Bulls see Five Below using this larger credit line to fund expansion without stretching the balance sheet, while bears worry about overpaying for that option. Which story does the current valuation support?
Most Popular Narrative: 27.3% Undervalued
Against the last close of $225.87, the most followed narrative for Five Below points to a fair value of $310.48. The updated store rollout and capital deployment story is doing most of the valuation heavy lifting.
The planned entry into Puerto Rico from the second half of 2027, with initial stores in a kid-focused value market without a direct concept competitor, can open a new geography for Five Below and add incremental sales and potential profit contribution beyond the existing U.S. store base.
See why 15 investors see Five Below as 27% undervalued.
Result: Fair Value of $310.48 (UNDERVALUED)
Still, fuel and trucking costs pressuring margins, along with multiple legal and regulatory actions, could quickly challenge the bullish Five Below story that investors are leaning on.
Find out about the key risks to this Five Below narrative.
Another View: Cash Flows Point To Overvaluation
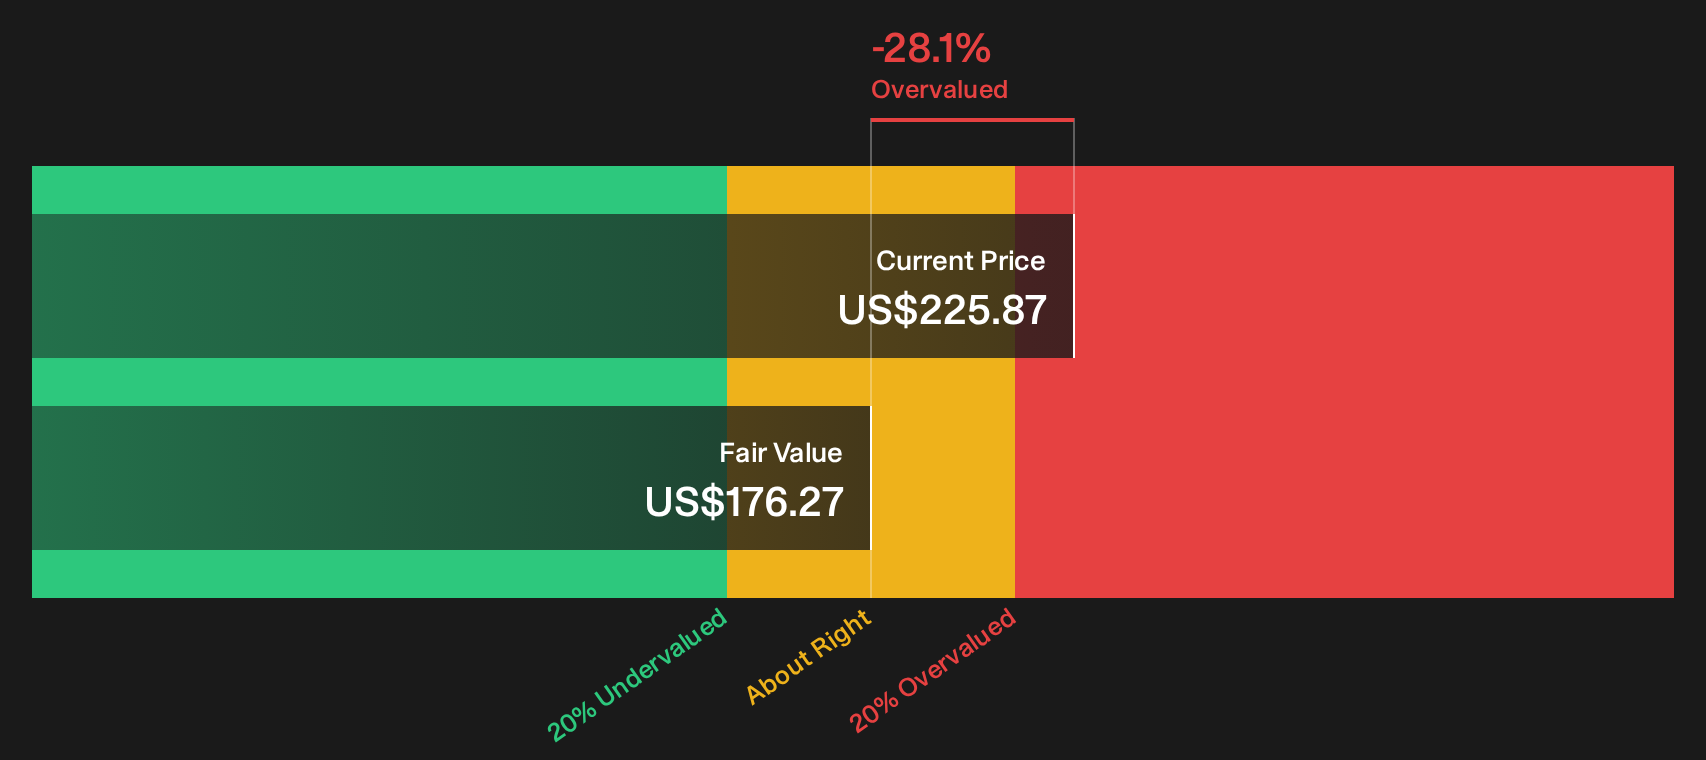
The 27.3% undervaluation story for Five Below leads to a very different result when the focus shifts to cash flows. The SWS DCF model puts fair value at $176.27, which is well below the current $225.87 share price and identifies the stock as overvalued on this measure.
This gap suggests investors are currently paying a premium for Five Below relative to the future cash flow profile implied by the model. The key question is whether you think the market is correctly pricing potential upside that the cash flow assumptions do not capture, or instead overpaying for growth that may not occur.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Five Below for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Five Below's value story are clear, and the market is already reacting. Step into the numbers yourself and weigh both sides. To see the full balance between upside potential and areas of concern, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Five Below?
If Five Below's mixed valuation story has you thinking harder about where to put fresh capital, consider broadening your watchlist with a few targeted stock ideas curated by the Simply Wall St screener.
- Target resilient capital by reviewing 30 resilient stocks with low risk scores that aim to keep portfolio volatility in check when sentiment swings.
- Hunt for mispriced quality through the 20 high quality undiscovered gems that many investors may not be watching yet.
- Prioritize financial strength and flexibility with a list of solid balance sheet and fundamentals (26 results) so you are not caught off guard when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com