


Sanofi (ENXTPA:SAN) moved back into focus after two pipeline headlines landed within days. Fresh phase 2b data on duvakitug in ulcerative colitis and Crohn’s disease arrived alongside a new worldwide mRNA collaboration with ScionxBio.
The fresh duvakitug data and ScionxBio mRNA deal arrive after a busy few weeks for Sanofi. The company also broke ground on a new insulin facility in Frankfurt and moved a Recursion AI-derived immunology candidate into its pipeline. Yet the share price at €74.95 still sits on a weaker year to date share price return of 8.95% and a one year total shareholder return that is down 8.62%. This suggests that recent positive headlines are lifting short term momentum, while longer term performance, with the three year total shareholder return down 14.34% and the five year total shareholder return up 7.99%, reflects a more muted journey for patient investors.
Compare Sanofi’s pipeline catalysts with other healthcare opportunities by scanning a hand picked set of 127 healthcare AI stocks that are also leaning on next generation therapies and data driven drug development.
Sanofi’s short burst of gains after a tougher year could be read as a re-rating of its drug engine or just a sentiment swing. The valuation work now needs to separate story from price.
Most Popular Narrative: 4% Overvalued
Sanofi closed at €74.95, while the most followed narrative, according to Szock, points to a fair value of €72.23 and labels the stock as slightly expensive.
Attraktive Bewertung und KursrücksetzerDie Aktie hat in den vergangenen Monaten nachgegeben und bewegt sich im Bereich von rund 76 bis 77 EUR. Damit notiert sie deutlich unter ihren früheren Höchstständen. Für langfristig orientierte Investoren eröffnet dieser Rücksetzer einen günstigen Einstiegspunkt, da das Kurs-Gewinn-Verhältnis (KGV) auf Basis der erwarteten Gewinne moderat ist und Analysten den fairen Wert spürbar höher ansetzen.
See why 5 investors see Sanofi as 4% overvalued.
Result: Fair Value of €72.23 (OVERVALUED)
Still, Sanofi’s case can quickly look different if key drugs face steeper patent pressure than expected or if late stage pipeline assets stumble in trials.
Find out about the key risks to this Sanofi narrative.
Another View: What Multiples Say About Sanofi
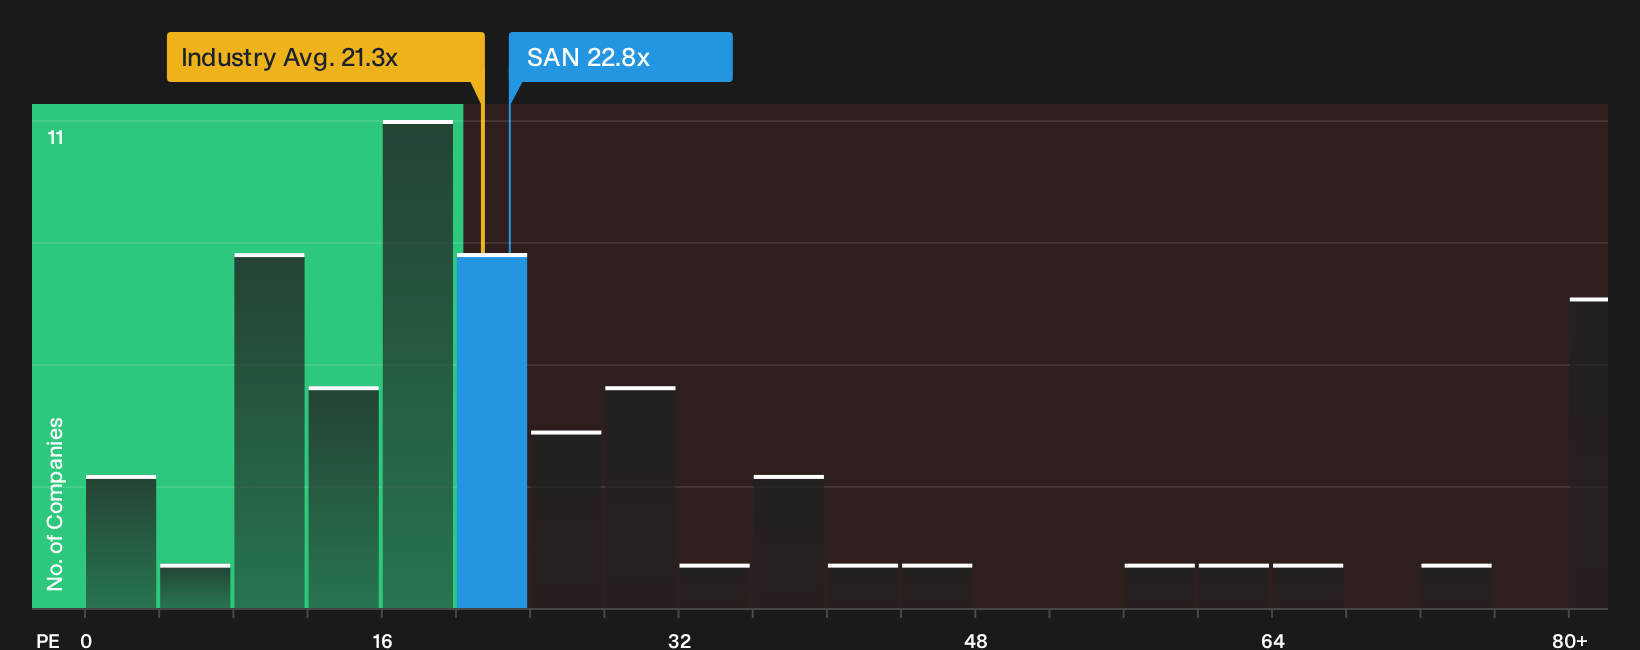
Sanofi may look only 4% overvalued against the €72.23 fair value in the leading narrative, yet its 22.8x P/E tells a tougher story. That level is higher than both the European pharma average on 21.3x and a peer average of 17.4x. The fair ratio, meanwhile, points to 38x as a level the market could move towards in a different scenario. For anyone weighing those gaps, the key question is whether current earnings quality and sector sentiment justify paying a richer multiple today or call for more caution.
To pressure test that view against earnings-based valuation, take a closer look at how the numbers stack up in our fair ratio workup. Then contrast that with the broader valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
The relative pricing picture versus the sector and peers is captured visually in the
Next Steps
Mixed messages in the data so far. If Sanofi’s signal feels unclear, move quickly, review the underlying trends yourself, and weigh both the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Sanofi?
If Sanofi leaves you on the fence, broaden your watchlist and put fresh ideas on your radar before other investors move first.
- Target resilience by scanning a 223 resilient stocks with low risk scores that focuses on businesses with comparatively steadier profiles and fewer red flags on core fundamentals.
- Hunt for value by reviewing a 191 high quality undervalued stocks that filters for quality companies trading below what their cash flows and balance sheets may justify.
- Spot early opportunities by working through a 619 high quality undiscovered gems that highlights quieter stories with solid numbers and limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com