


H. Lundbeck (CPSE:HLUN B) is preparing for a leadership handover after Chair Dorothea Wenzel signaled she will step down at the 2027 AGM, timed with its next Focused Innovator strategy phase.
Investors have already reacted to Lundbeck's refreshed Focused Innovator plan and clearer leadership timetable, with a 1 month share price return of 15.94% and a 90 day share price return of 22.27%, building on a 3 year total shareholder return of 52.49%. This performance points to momentum that shareholders will likely weigh against the company’s current valuation and execution risks.
Scan how H. Lundbeck’s leadership reset compares with other potential breakout opportunities across our hand picked 619 high quality undiscovered gems to see where governance shifts and fresh execution plans are already in play.
H. Lundbeck now has a clearer plan and a sharply higher share price. The real work for investors starts here. Does this quality neurology specialist still look reasonably priced after the recent jump?
Most Popular Narrative: 4.7% Overvalued
H. Lundbeck last closed at DKK51.50, slightly above the most followed narrative fair value estimate of DKK49.19. This frames the recent share price surge as leaving only a modest valuation cushion if earnings or the pipeline disappoint.
The current valuation and this narrative’s bearish stance together suggest that the share price broadly reflects H. Lundbeck’s existing growth drivers and pipeline progress, leaving limited margin for error if execution or key products underperform.
See why 15 investors see H. Lundbeck as 5% overvalued.
Result: Fair Value of DKK49.19 (OVERVALUED)
Still, H. Lundbeck’s reliance on a few key brands and a neuroscience heavy pipeline means that any setback in trials or patent exposure could quickly challenge this overvaluation narrative.
Find out about the key risks to this H. Lundbeck narrative.
Another View: Earnings Multiple Points to Value Support
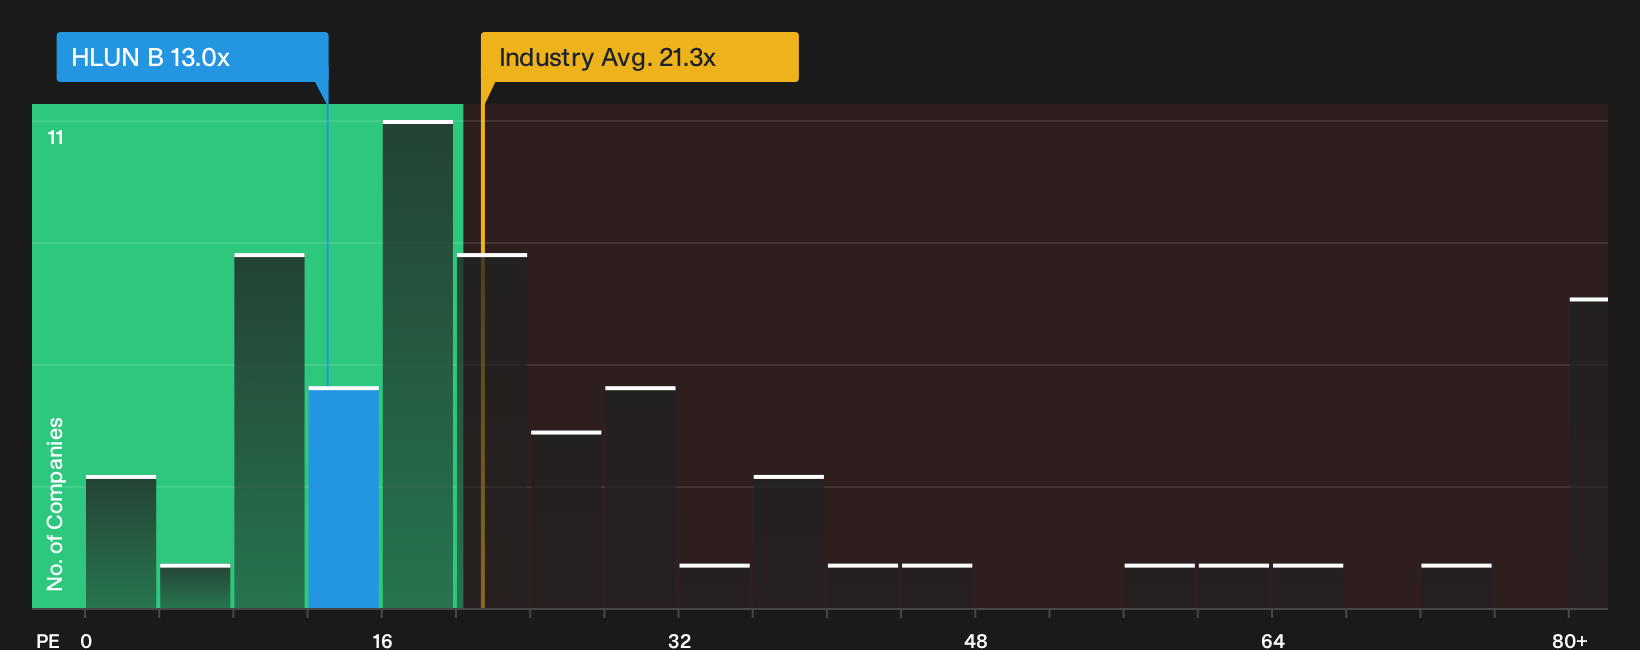
The crowd narrative around H. Lundbeck leans on a fair value of DKK49.19, which paints the current DKK51.50 price as modestly stretched. A different lens tells a softer story. The stock trades on a P/E of 13x, compared with a fair ratio of 14.8x, the European pharmaceuticals average of 19.9x and a peer average of 22.9x. That gap suggests the market already prices in plenty of earnings risk. The question is whether you see that discount as warranted caution or a potential cushion if sentiment improves.
For a closer look at how these valuation gaps stack up against earnings quality and sector peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Torn between caution and optimism around H. Lundbeck’s future path? Act while sentiment is live and weigh the red flags against the upside case using 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond H. Lundbeck?
Do not stop your research with H. Lundbeck. Broaden your watchlist with fresh ideas sourced from the Simply Wall Street Screener so you are not caught flat footed.
- Target reliable compounding by scanning a curated pool of resilient businesses with 223 resilient stocks with low risk scores that aim to keep volatility contained while still pursuing upside.
- Hunt for mispriced quality by using 191 high quality undervalued stocks to spot financially solid stocks that trade below their estimated worth and might reward patient investors.
- Strengthen your capital base with companies that prioritize balance sheet resilience through the list of solid balance sheet and fundamentals (203 results) before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com