


- Flowserve is scheduled to report results for the quarter ended September 2026 on October 28, with the market focused on how earnings and revenue line up against current expectations.
- The recent shift toward slightly more cautious analyst earnings forecasts, including a modestly negative Earnings ESP of 0.68%, highlights questions about how current demand and cost discipline are feeding through to near term profitability.
- This article examines how Flowserve's investment narrative intersects with softer earnings expectations ahead of the September 2026 results release.
Scan how Flowserve compares with other industrial stocks under earnings pressure by checking a curated set of 30 resilient stocks with low risk scores that pair resilient balance sheets with more predictable fundamentals.
Flowserve Investment Narrative Recap
For a shareholder in Flowserve, the core belief is that disciplined execution in pumps, valves and aftermarket services can support earnings even when end markets are uneven. The near term focus stays on how the Flowserve Business System, cost controls and mix toward higher margin work show up in the September quarter. Recent caution around the upcoming print does not by itself alter that longer operating thesis.
The main short term catalyst is evidence that margin work and aftermarket momentum remain intact, despite softer Middle East activity and trimmed 2026 organic sales expectations. The biggest risk is that ongoing regional disruption or weaker order trends make it harder for management to hit its own earnings guidance, which would pressure the current equity story.
Recent commentary around roughly US$60 million of sales impact and about a 20% reduction in Middle East run rate activity remains highly relevant as you weigh the October 28 earnings release. This part of the portfolio affects both near term revenue and how quickly any restoration or redundancy work might refill the backlog once conditions improve.
Flowserve has also been leaning on margin initiatives and the Trillium valves acquisition to shift the mix toward power and nuclear projects, where bookings above US$110 million in both Q1 and Q2 2026 give some visibility on multi year work. The earnings call will help you judge whether those higher margin streams, together with nearly US$700 million of Q2 aftermarket bookings, are offsetting softer organic demand and the drag from Middle East disruption in a consistent way.
Flowserve earnings assumptions and valuation setup
Analysts currently model Flowserve with a revenue growth rate of 6.5% a year over the next three years, starting from profit margins of 8.0% today that are projected to reach 13.2% by 2029. Earnings are forecast at US$371.3 million today and are expected to reach US$737.9 million, with earnings per share of US$4.98 by 2029, implying roughly a doubling of profit over that period. That profile underpins consensus assumptions that the stock could trade on a P/E of 19.9x on those 2029 earnings, compared with 25.5x on current figures and the broader US Machinery industry at 23.7x, using a discount rate of about 9%.
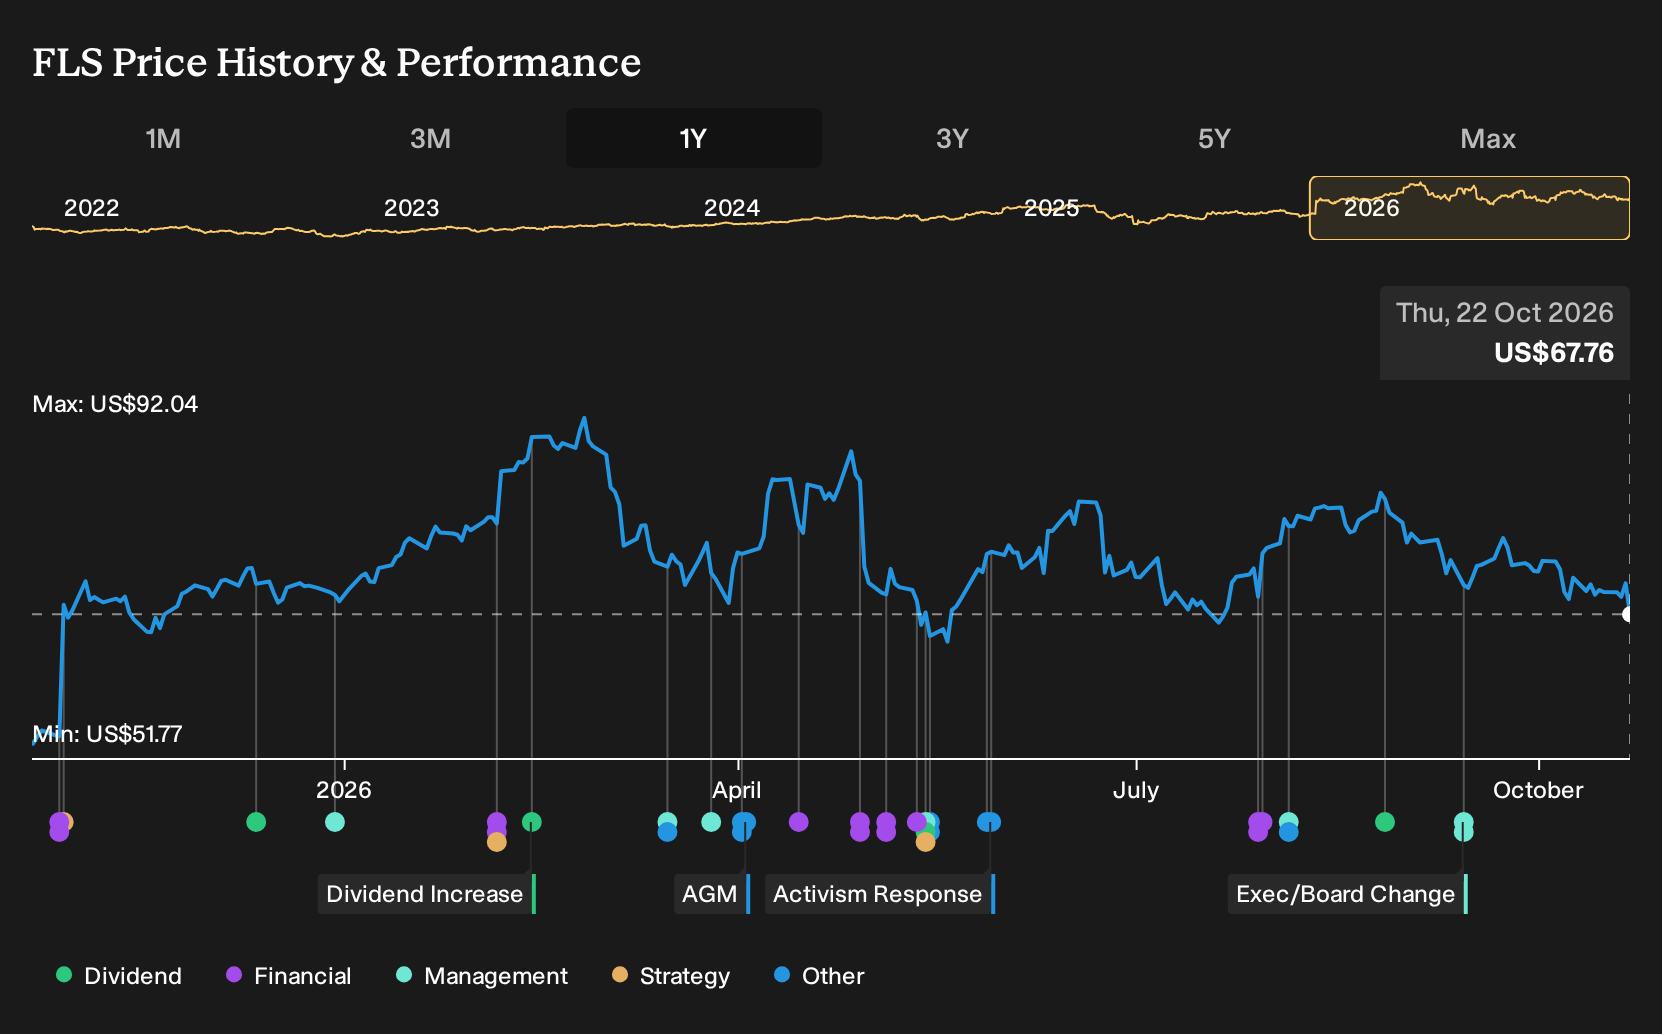
On the valuation side, the analyst group has clustered around a US$89.00 price target, compared with a current share price of US$74.37 as of late October 2026. Targets span from US$70.00 at the low end to US$100.00 at the top, reflecting different views on how much of the earnings and margin work is already reflected in the share price. To line up with the consensus case, you would need to be comfortable with 2029 revenues of about US$5.6b and earnings of US$737.9 million, together with that lower future P/E multiple of 19.9x on the modelled earnings base.
Flowserve's narrative projects US$5.6b revenue and US$737.9 million earnings by 2029. This rests on 6.5% yearly revenue growth and an earnings increase of about US$366.6 million from US$371.3 million today.
Uncover how Flowserve's fair value indicates a 31% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view around Flowserve focuses less on Middle East rebuild potential and more on the risk that original equipment and nuclear projects convert slowly into sales. The most cautious analysts were still modelling 2029 earnings around US$734.3 million on roughly US$5.6b of revenue before this earnings release, which supports a far more muted share price narrative. Opinions clearly span a wide range. Treat the upcoming numbers as a fresh data point that could shift both the upbeat and the more reserved forecasts you see today.
Explore 4 other Flowserve fair value estimates, including one that suggests it could be worth just $73.26.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Flowserve research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flowserve. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flowserve's overall financial health at a glance.
Looking For More Investment Ideas Beyond Flowserve?
If the Flowserve story has you thinking about portfolio balance, it can help to widen the lens and compare it with other companies that share traits you care about, whether that is quality, resilience, or income.
- If you want potential value combined with quality fundamentals, start with a focused set of 30 high quality undervalued stocks that already clear a high bar on both business strength and pricing.
- For investors who care most about stability and downside protection, a curated 30 resilient stocks with low risk scores can highlight businesses with stronger risk profiles than the broader market.
- If you are hunting for under followed opportunities, a targeted 20 high quality undiscovered gems can surface businesses that have solid metrics but receive far less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com