


What Recent Returns Signal For Global Net Lease
Global Net Lease (GNL) has drawn fresh attention after a period of uneven share performance, with the real estate investment trust now trading at a last close of US$7.28.
Over the past month the stock fell about 16%, and it declined roughly 18% across the past 3 months, even as the 1 year total return sits at around 4%.
For Global Net Lease, the picture is mixed, with the share price down over the year to date but the 1 year total shareholder return still positive once dividends are included. This suggests that income rather than price momentum has been doing more of the heavy lifting recently, as investors reassess both growth potential and risk around the REIT’s portfolio and balance sheet.
Scan beyond Global Net Lease and compare it with a hand picked 6 dividend fortresses that aims to balance income potential with financial resilience.
Global Net Lease offers a diversified net lease portfolio, yet the recent share price slide raises a sharper question. Is this now a solid income engine on sale, or fairly valued risk in a challenged REIT sector?
Most Popular Narrative: 27% Undervalued
On the most followed narrative, Global Net Lease screens as undervalued, with an implied fair value of about $10.00 against the recent $7.28 share price. This puts the focus squarely on whether its portfolio reshaping and deleveraging can justify that gap.
The deliberate portfolio transformation toward a pure-play single-tenant net lease structure with a focus on essential industrial, logistics, and high-quality office assets positions GNL to benefit from rising tenant demand for mission-critical real estate and asset-light business models. This is expected to support higher occupancy, stable revenue streams, and topline revenue growth.
See why 9 investors see Global Net Lease as 27% undervalued.
Result: Fair Value of $10.00 (UNDERVALUED)
Still, the Global Net Lease story depends on execution, with a loss of $61.6 million and leverage around 7x leaving little room for prolonged office or tenant stress.
Find out about the key risks to this Global Net Lease narrative.
Another View On Global Net Lease’s Valuation
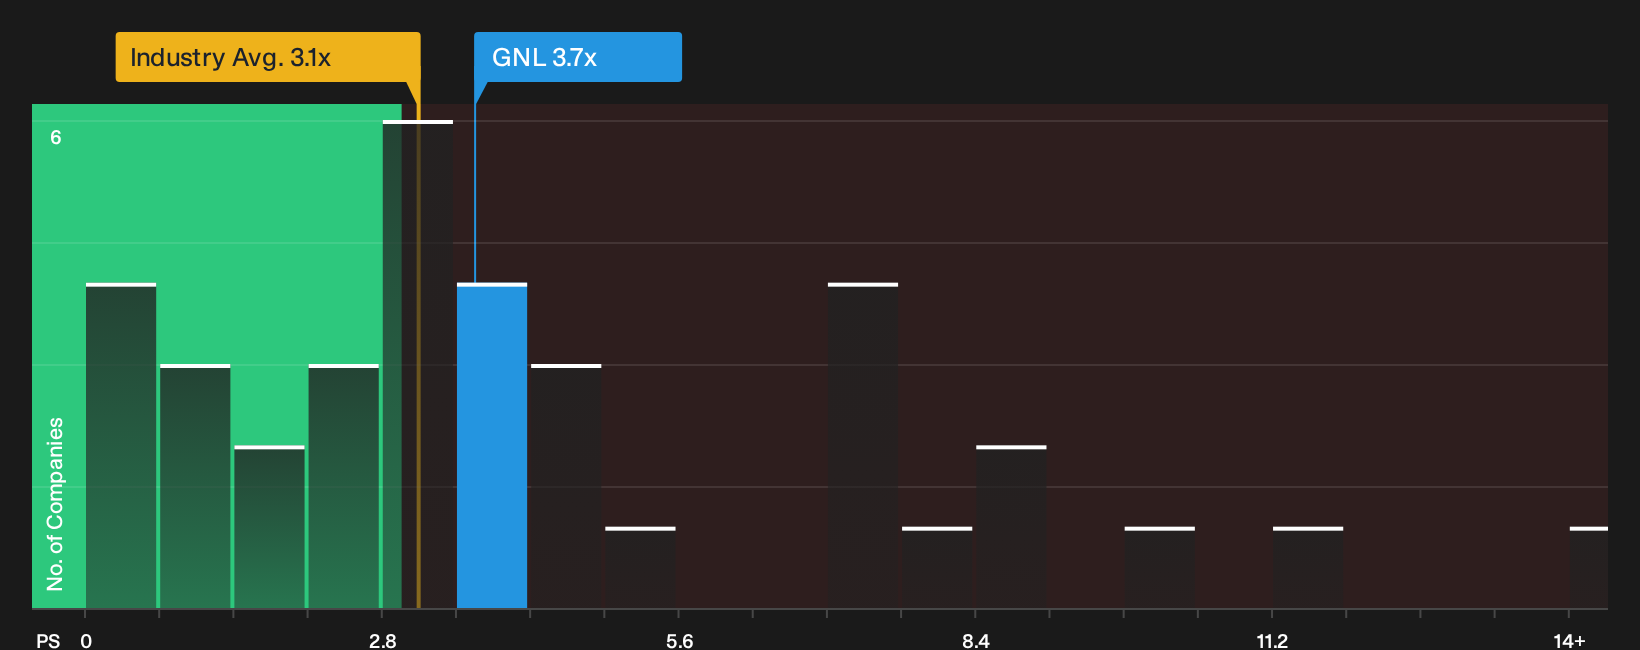
There is a twist when Global Net Lease is judged on revenue multiples. The stock trades on a P/S of 3.7x, which is higher than the 3.1x North American REITs average but below peers at 4.7x. The fair ratio sits higher again at 5.4x. Is that a cushion or a value trap in the making?
To see how that pricing gap lines up with fundamentals and risk, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Global Net Lease only matters if you act on it. Move quickly, review the full picture, and weigh both the apparent upside and the highlighted concerns by checking the 2 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Global Net Lease?
If Global Net Lease has your attention today, do not stop there. Broader opportunity often sits just outside your current watchlist, and you do not want to overlook it.
- Hunt for mispriced strength by reviewing companies that pass strict quality and value filters through the 30 high quality undervalued stocks.
- Prioritise staying power and financial discipline by scanning businesses with sturdy funding profiles in the list of solid balance sheet and fundamentals (26 results).
- Spot early standouts before they become crowded trades by tracking financially robust outliers via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com