


Analysts see a sharp pickup in Novanta (NOVT) revenue over the coming year, putting fresh attention on how its newer medical and automation products translate into growth while returns on invested capital trend lower.
At a share price of $136.66, Novanta has given investors a 22.96% share price return year to date. However, the 1-year total shareholder return of 15.01% and 5-year total shareholder return decline of 20.68% show momentum has only recently improved as expectations around future revenue have picked up despite concerns about weaker returns on invested capital.
Scan how Novanta compares with other fast-growing automation and medical technology plays by working through a curated set of 20 high quality undiscovered gems that the market may be underpricing.
The question now is whether Novanta’s sharp recent gain stems from a sturdier earnings engine or a mood shift among investors sizing up its next phase. That lens matters once you look at the valuation.
Most Popular Narrative: 30% Undervalued
With the most followed narrative putting Novanta’s fair value at $194.50 against a last close of $136.66, the gap it highlights rests on how recurring medical consumables, Gen AI related demand and manufacturing changes feed into future earnings.
Expansion of minimally invasive and robotic surgery, together with the Riverpoint Medical acquisition that roughly doubles recurring medical consumables revenue to about US$300 million and lifts medical exposure to around 60% of sales, increases Novanta''s mix of repeat consumables that can support more resilient revenue and gross margin over time.
See why 6 investors see Novanta as 30% undervalued.
Result: Fair Value of $194.50 (UNDERVALUED)
Still, higher leverage from the US$1.45b Riverpoint Medical deal and softer Medical Solutions margins could quickly challenge the current Novanta optimism if integration stumbles.
Find out about the key risks to this Novanta narrative.
Another View: What Novanta’s P/E Is Telling You
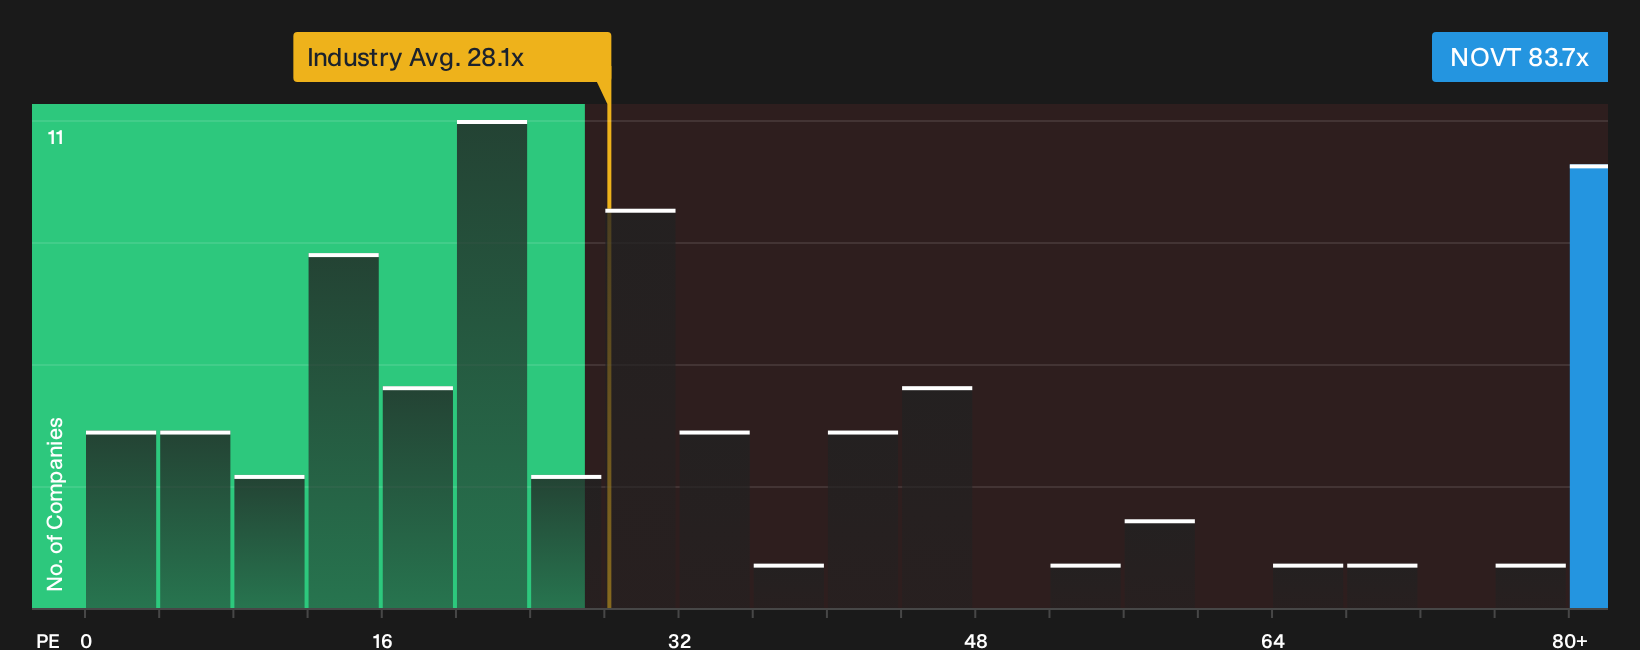
That 30% upside narrative meets a very different picture when you look at Novanta through its current P/E. The shares trade on roughly 83.7x earnings, compared with about 28.5x for the US Electronic industry, 52.5x for close peers, and a fair ratio of 40.6x. The gap points to meaningful valuation risk if execution or sentiment wobbles before earnings catch up, so the question is whether you think the story justifies paying roughly double the fair ratio today.
For a closer look at how these earnings multiples stack up against the underlying numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Novanta is clearly split, with enthusiastic upside narratives and clear caution flags now sitting side by side. Check the data quickly and decide where you land by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Novanta?
If Novanta has your attention, do not stop here. Broader context from other opportunities can sharpen your judgement and help you position your capital with intent.
- Spot potential bargains early by scanning a curated 29 high quality undervalued stocks that combines solid fundamentals with prices the market may be overlooking.
- Prioritise resilience and sleep-at-night holdings by working through a 30 resilient stocks with low risk scores that filters for businesses with stronger risk profiles.
- Target balance sheet strength by reviewing a list of solid balance sheet and fundamentals (26 results) that surfaces companies with sturdier finances and cleaner fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com