


RingCentral has seen a powerful rebound in its share price over the past few years, which naturally puts the focus on whether the current market value still lines up with what its earnings can support. With that kind of move in the rear-view mirror, investors are asking how much of the earnings story is already embedded in the US$79.42 price at the last close.
- Over the past 3 years, RingCentral has delivered a 211.9% return, so the key issue is how firmly that performance is anchored to the underlying earnings power of the business.
- The company runs a software-based communications platform, which can give it meaningful operating leverage as revenue grows and may support further improvement in how effectively earnings convert into cash over time.
- There is a second opinion on RingCentral worth weighing. See what analysts think RingCentral's shares could be worth.
The issue now is whether RingCentral's current share price is justified by the level and trajectory of its earnings.
If you are weighing whether RingCentral's earnings justify its recent rebound, it can help to compare that question with other software-focused businesses using 29 high quality undervalued stocks.
Is RingCentral Getting Expensive on Earnings?
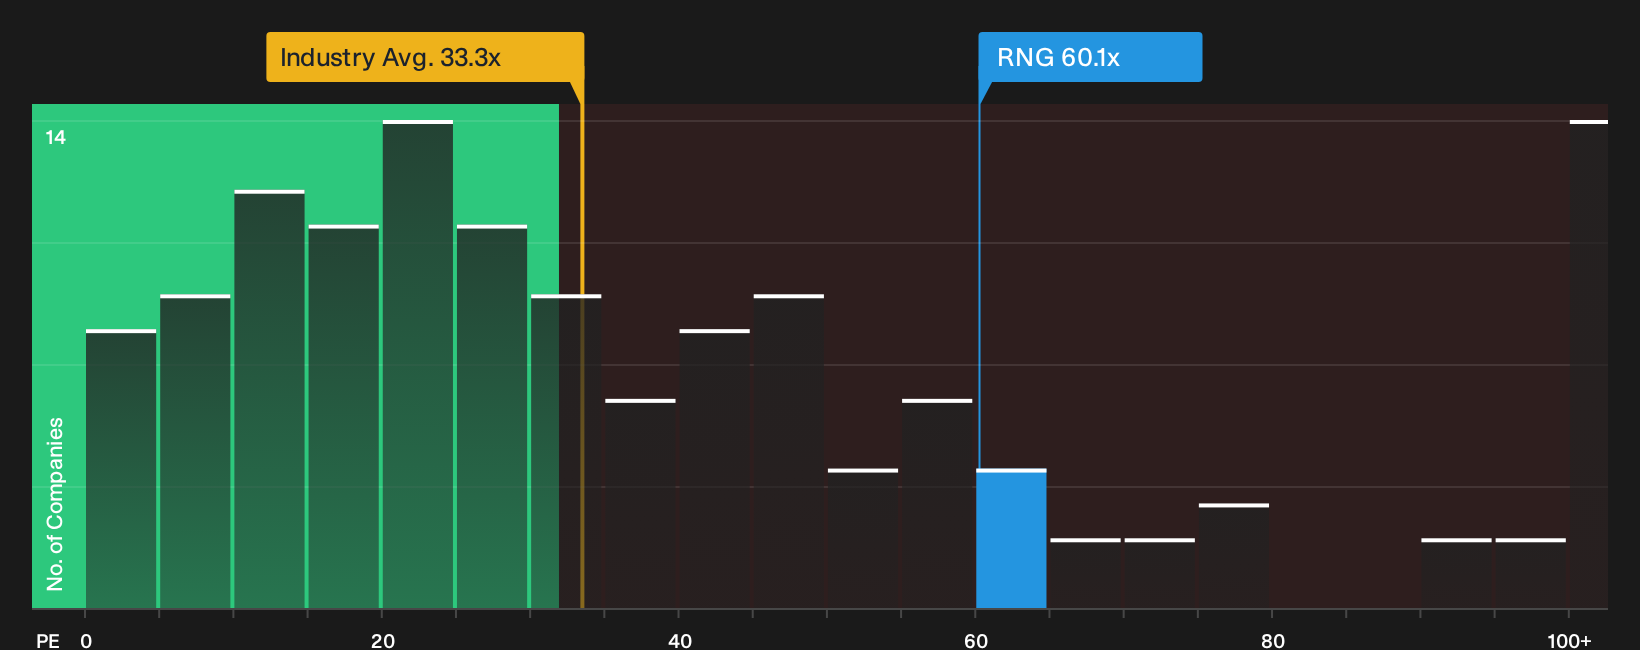
The P/E ratio fits RingCentral because earnings are now a key reference point for how the market values its communications platform. On that yardstick, the stock trades on about 60.1x earnings, which is well above both the wider software sector on roughly 33.3x and the peer group average around 28.6x.
A model that blends RingCentral's growth profile, profitability, size and risk suggests a lower P/E would typically be expected for this sort of business. On this framework, the current multiple screens as overvalued. That gap means the market is already placing a rich price on future earnings, so anyone considering the shares needs to judge whether the underlying cash generation and competitive position support paying that kind of premium. Explore the numbers behind RingCentral's P/E valuation.
The RingCentral Narrative: What Would Justify Today's Price?
RingCentral's valuation puzzle only really comes into focus once the underlying story is made explicit. Narratives on Simply Wall St's Community page spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than the current price. Rather than leaning on a single P/E or model output, each scenario lays out the assumptions behind its fair value so you can track those against future results.
RingCentral’s community views are split between AI driven upside and a richer valuation that some investors see as already baking in a lot of that promise.
Bull case: 7% undervalued
"RingCentral processes about 40 billion voice minutes and over 3 billion SMS messages each year, and management reports that these volumes are growing faster than the user base…"
Discover why this Narrative puts RingCentral at 7% undervalued.
Bear case: 38% overvalued
"Many enterprise customers are shifting toward fully bundled productivity suites (like Microsoft Teams, Zoom One, Google Workspace) that include embedded communications, which could decrease demand for RingCentral's standalone solutions…"
Explore why this Narrative puts RingCentral at 38% overvalued.
Before you act on RingCentral's valuation, there is one more angle to check
Numbers only tell part of the story for RingCentral, because the people setting priorities and the way they are rewarded can heavily shape how those numbers evolve. See who runs RingCentral and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com