


Almonty Industries (ALM) has entered a new phase after starting tungsten concentrate production at its Sangdong mine in South Korea. This shift is reinforced by new offtake and joint venture agreements across Spain and Rwanda.
Recent price action has cooled. The share price has fallen 39.02% over the past 30 days and 34.41% over 90 days. However, the 1-year total shareholder return of 14.83% and very large 3-year and 5-year total returns indicate that long-term momentum remains intact as Almonty Industries shifts from project build out to production.
Spot 33 best rare earth metal stocks that, like Almonty Industries, are tied to critical metals and could see sentiment swing quickly as production milestones land.Almonty Industries now trades at a steep discount to both analyst targets and some intrinsic value estimates after this sharp pullback. Is that a mispricing, or is the market simply pricing in execution risk on the new projects?
Most Popular Narrative: 43% Undervalued
On the narrative view, Almonty Industries screens as materially undervalued, with a fair value of $15.26 against the last close at $8.75. The gap may come down to whether the market is underestimating execution risk across its tungsten portfolio.
The assumed bearish price target for Almonty Industries is $15.26, which represents up to two standard deviations below the consensus price target of $24.49. This valuation is based on what can be assumed as the expectations of Almonty Industries's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 1 investors see Almonty Industries as 43% undervalued.
Result: Fair Value of $15.26 (UNDERVALUED)
Still, if Sangdong ramps smoothly and Los Santos tailings prove commercially robust, Almonty Industries could end up outpacing the cautious narrative that bearish analysts outline.
Find out about the key risks to this Almonty Industries narrative.
Another View: What Almonty Industries' P/E Is Saying
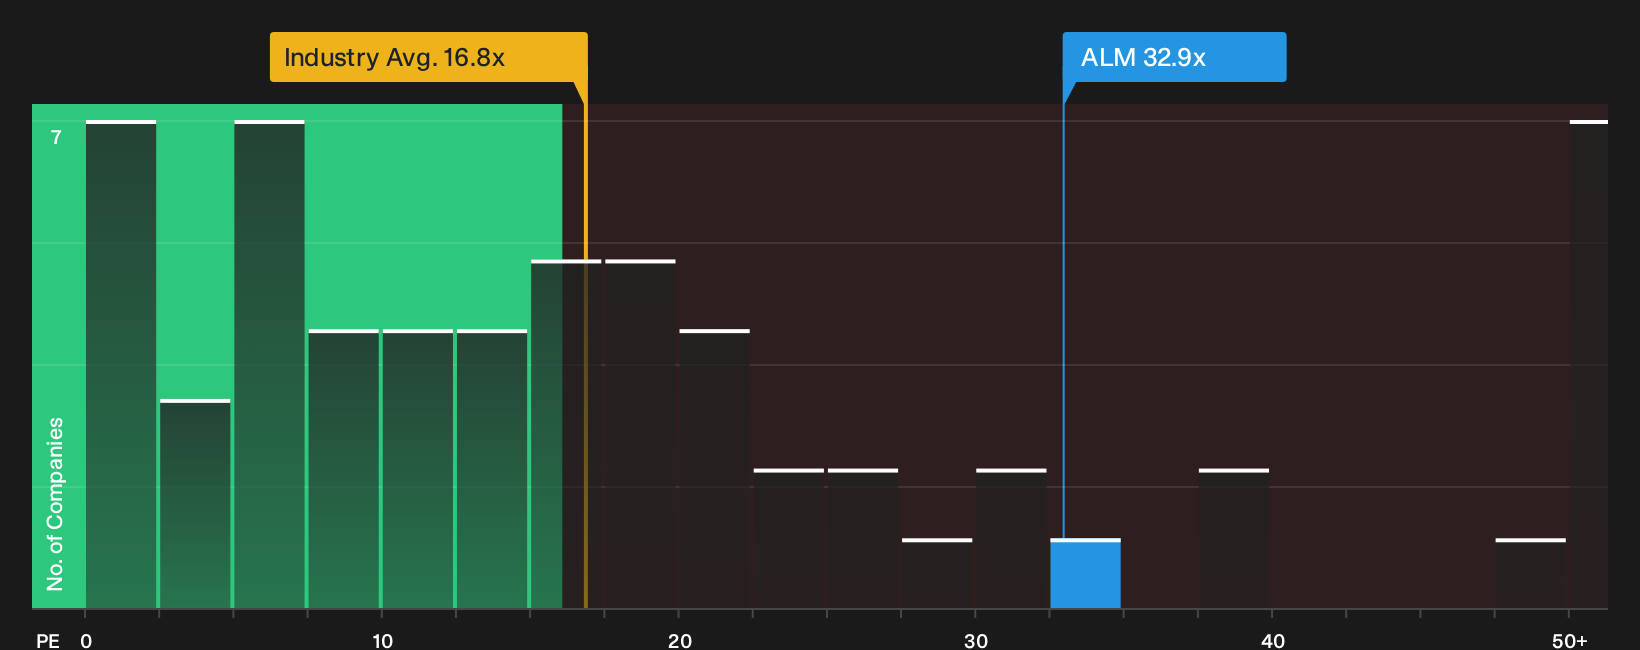
The story changes once the focus shifts from fair value models to the P/E ratio. Almonty Industries trades on 32.9x earnings, which is higher than the US Metals and Mining industry at 16.8x and above peers at 21.5x. Yet the fair ratio sits at 47.2x. Is the premium multiple a warning sign, or is the market only partway through repricing future growth?
To unpack how that valuation gap could close in either direction, take a closer look at the detailed breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Almonty Industries story so far. Given the blend of concern and optimism in the current data, it may be helpful to move quickly and pressure test the thesis yourself by weighing up the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Almonty Industries?
If Almonty Industries has put critical metals on your radar, broaden your watchlist with a few focused screeners that can quickly surface fresh opportunities.
- Target value first by scanning companies that currently screen as 29 high quality undervalued stocks and may warrant a closer look on their fundamentals.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (26 results) that can help you focus on businesses with stronger financial footing.
- Get ahead of the crowd by checking 20 high quality undiscovered gems that the market may not be paying full attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com