


Paymentus Holdings (PAY) moved back onto investor radars after an analyst upgrade highlighted a more positive view on its earnings trajectory, prompting fresh attention to the stock’s recent performance.
The recent rating upgrade landed on a stock that already had momentum, with a 1-day share price return of 3.06% and a 7-day share price gain of 6.04% helping push Paymentus Holdings to US$34.07. Over a longer horizon, the 3-year total shareholder return of 133.20% and 1-year total shareholder return of 10.65% suggest the stronger recent moves are building on an already solid track record rather than appearing in isolation.
Seize this earnings upgrade as a chance to review Paymentus Holdings alongside a hand picked 20 high quality undiscovered gems with similar quality traits hiding in plain sight.Bulls see the upgraded earnings outlook and long run returns as proof Paymentus Holdings deserves its recent re-rate. Bears argue the optimism is already priced in. Which case do the current valuation markers support next?
Most Popular Narrative: 15% Undervalued
On Simply Wall St’s most followed narrative, Paymentus Holdings screens as undervalued, with a fair value of $40.14 against the latest close at $34.07. This frames this earnings upgrade inside a wider debate about growth durability under a 7.28% discount rate.
The AI native Service Commerce stack, including patented BillWallet, Billeo and AI360 products that already show early user adoption without marketing spend, positions Paymentus Holdings to capture new software and AI driven payment use cases, which can add higher margin revenue streams and support adjusted EBITDA growth.
See why 11 investors see Paymentus Holdings as 15% undervalued.
Result: Fair Value of $40.14 (UNDERVALUED)
Still, if large enterprise clients push harder on pricing or investor confidence weakens again after early 2026 selling, the Paymentus Holdings narrative could shift quickly.
Find out about the key risks to this Paymentus Holdings narrative.
Another View: What Paymentus Holdings’ P/E Is Telling You
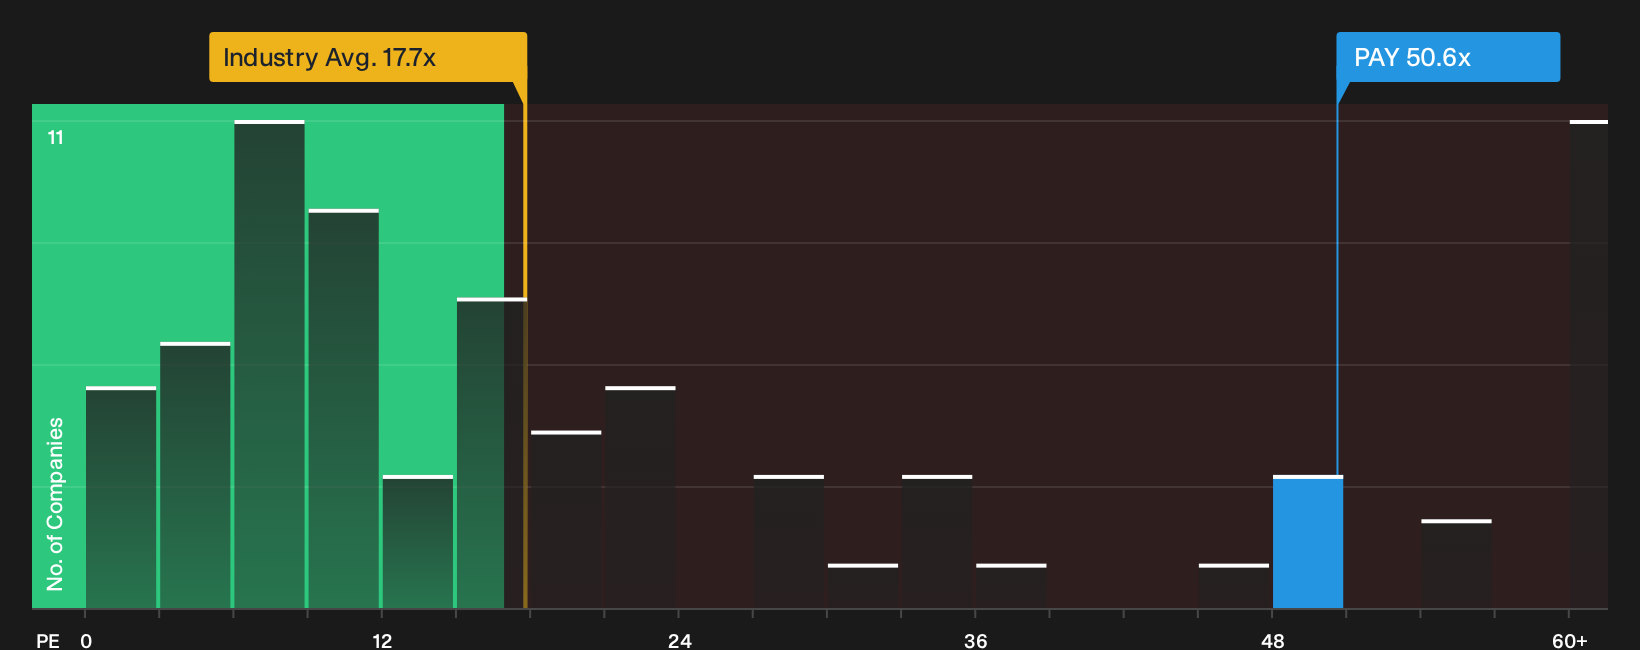
There is a very different message once you look at Paymentus Holdings through its P/E ratio. The shares trade at 50.6x earnings, compared with 17.6x for the US Diversified Financial industry, a peer average of 34.5x and a fair ratio of 18.3x that the market could move towards.
That gap points to meaningful valuation risk if expectations cool, even with strong earnings growth forecasts on the table. It leaves a simple question for you to weigh: Is this premium a comfort or a constraint for owning PAY at today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Paymentus Holdings today. If you want to move past the headlines and form your own stance quickly, start by weighing 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paymentus Holdings?
If Paymentus Holdings has your attention, do not stop there. Use the screener to quickly line up other candidates that fit the kind of portfolio you want.
- Target potential bargains by scanning a curated 29 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Anchor your watchlist with sturdier balance sheets by sorting companies in the list of solid balance sheet and fundamentals (26 results) that can better handle shocks and funding pressures.
- Hunt for under the radar potential by reviewing the 20 high quality undiscovered gems where fundamental strength has not yet attracted broad attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com