


Hesai Group (NasdaqGS:HSAI) just rolled out Kosmo, a 3D world data engine that pairs its Kosmo One AI spatial camera with cloud software to capture and reconstruct physical spaces for AI and robotics.
The launch of Kosmo arrives after a tough stretch for Hesai Group’s shareholders, with the share price down 25.6% over the past 30 days and 49.6% year to date, even though the 3-year total shareholder return is up 21.4%. This suggests long-term holders have still seen gains despite fading recent momentum.
Scan the AI hardware and robotics space beyond Hesai Group by sizing up curated 93 robotics and automation stocks that could be building the next layer of Physical AI infrastructure.
Hesai Group now trades well below its recent levels, just as Kosmo could reshape how investors view the business. Is this a reasonable entry today, or does patience for a cheaper price make more sense?
Most Popular Narrative: 58% Undervalued
Against a last close of $12.14, the most popular narrative tags Hesai Group with a fair value near $28.97. This frames the Kosmo launch inside a much bigger earnings and cash flow story built on LiDAR volumes, margins, and discount rate assumptions.
The projection of 2025 LiDAR shipments reaching 1.2 million to 1.5 million units, with nearly 200,000 high-margin robotic LiDAR units, is expected to significantly boost revenue.
Anticipated net revenues of RMB 3 billion to RMB 3.5 billion for 2025, driven by strong demand and mass market adoption, indicate potential growth in revenue.
See why 34 investors see Hesai Group as 58% undervalued.
Result: Fair Value of $28.97 (UNDERVALUED)
Still, heavy reliance on a few major clients and ongoing LiDAR pricing pressure could quickly weaken the upbeat Hesai Group narrative if conditions change.
Find out about the key risks to this Hesai Group narrative.
Another View: Hesai Group Through The P/E Lens
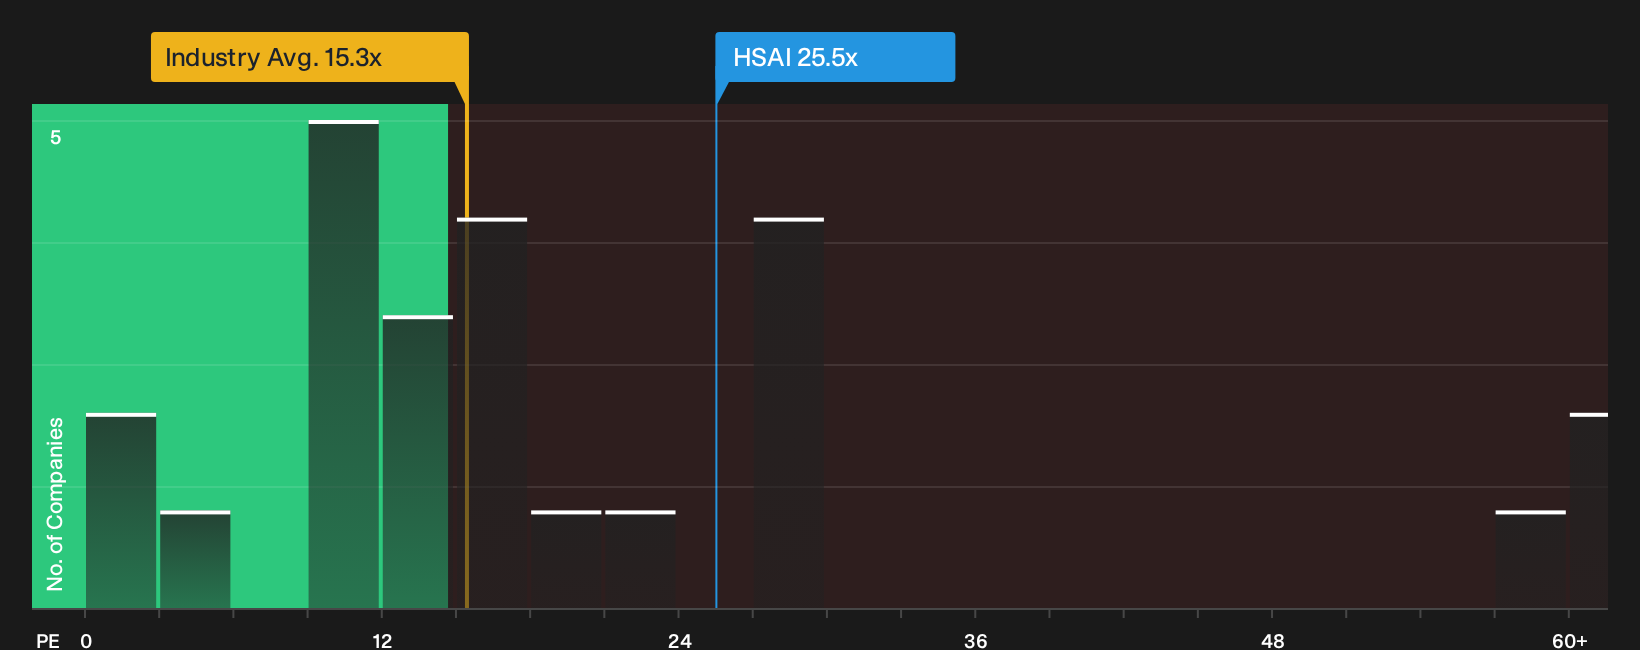
The first narrative paints Hesai Group as heavily undervalued, yet the simple earnings multiple tells a different story. The shares trade at a P/E of 25.5x, while the wider US Auto Components industry averages 15.3x and direct peers sit near 13.6x.
Against that backdrop, the stock screens as expensive relative to both sector and peer group, even though the fair ratio for Hesai Group is estimated at 29.3x. That gap points to limited valuation cushion if growth or margins disappoint. Which signal do you trust more: the crowd’s optimism or the tougher peer comparison?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hesai Group is split right now, so move quickly to test the numbers, stress test the assumptions, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Hesai Group style investment ideas?
If you stop with Hesai Group, you risk missing other opportunities that fit your approach, so put the Simply Wall Street Screener to work for you.
- Target stronger balance sheets by scanning a list of solid balance sheet and fundamentals (26 results) that can help you focus on companies with support for future plans.
- Hunt for better value opportunities through a curated 29 high quality undervalued stocks that highlights businesses where fundamentals and pricing look more aligned.
- Build a watchlist of overlooked prospects using a focused 20 high quality undiscovered gems that surfaces under-the-radar stocks before they become crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com