


What Plug Power’s New Engineering Hire Signals For Investors
Plug Power (PLUG) has put manufacturing execution in sharper focus by appointing Dr. Lee Sweetland as Global Engineering Industrialization Lead, a move that directly targets its proton exchange membrane stack production.
The hire is not about a new product announcement. It is about how efficiently the existing hydrogen portfolio can be produced, shipped, and run in the field, which is where costs and reliability are determined.
Sweetland’s remit covers industrialization of Plug Power’s PEM stack technology, with a specific mandate around manufacturing performance, product reliability, and cost competitiveness across the hydrogen solutions lineup.
That scope matters for a business that designs and sells fuel cell systems, electrolyzers, and liquid hydrogen infrastructure, because small technical choices in stack design and assembly can influence long-term service costs and uptime.
For context, Plug Power’s share price has retreated to US$1.38, with a 30 day share price return down 34.6% and a 1 year total shareholder return down 52.1%. This signals fading momentum despite management changes and attention on the upcoming November earnings update.
Scan 20 high quality undiscovered gems that, unlike Plug Power, are already pairing advanced manufacturing stories with stronger fundamentals and less reliance on fresh equity to keep the hydrogen thesis moving.
After a slide that has already erased most of Plug Power’s five year return, the live question now is whether today’s US$1.38 still leaves meaningful upside ahead, or whether most of the recovery case already sits in the rear view mirror as valuation enters the frame.
Most Popular Narrative: 61% Undervalued
Plug Power’s most followed valuation story pegs fair value at $3.55, well above the recent $1.38 share price. This puts execution and liquidity under a sharper spotlight for anyone weighing that gap.
Operational improvements such as gross margin enhancements from Project Quantum Leap, restructuring, facility consolidation, and favorable hydrogen supply agreements are already yielding sharply better margins and targeting breakeven gross margin by Q4, which can lead directly to improved net margins and earnings.
Expansion of Plug Power's vertically integrated hydrogen production and distribution network (new facilities in Georgia, Louisiana, and soon Texas) is strengthening supply reliability, lowering production costs, and enhancing customer confidence, supporting both volume-driven revenue growth and future margin gains.
See why 202 investors see Plug Power as 61% undervalued.
Result: Fair Value of $3.55 (UNDERVALUED)
Still, Plug Power’s narrative leans on policy support and large hydrogen projects; setbacks on subsidies or delayed final investment decisions could quickly test those assumptions.
Find out about the key risks to this Plug Power narrative.
Another View: Plug Power Looks Expensive On Sales
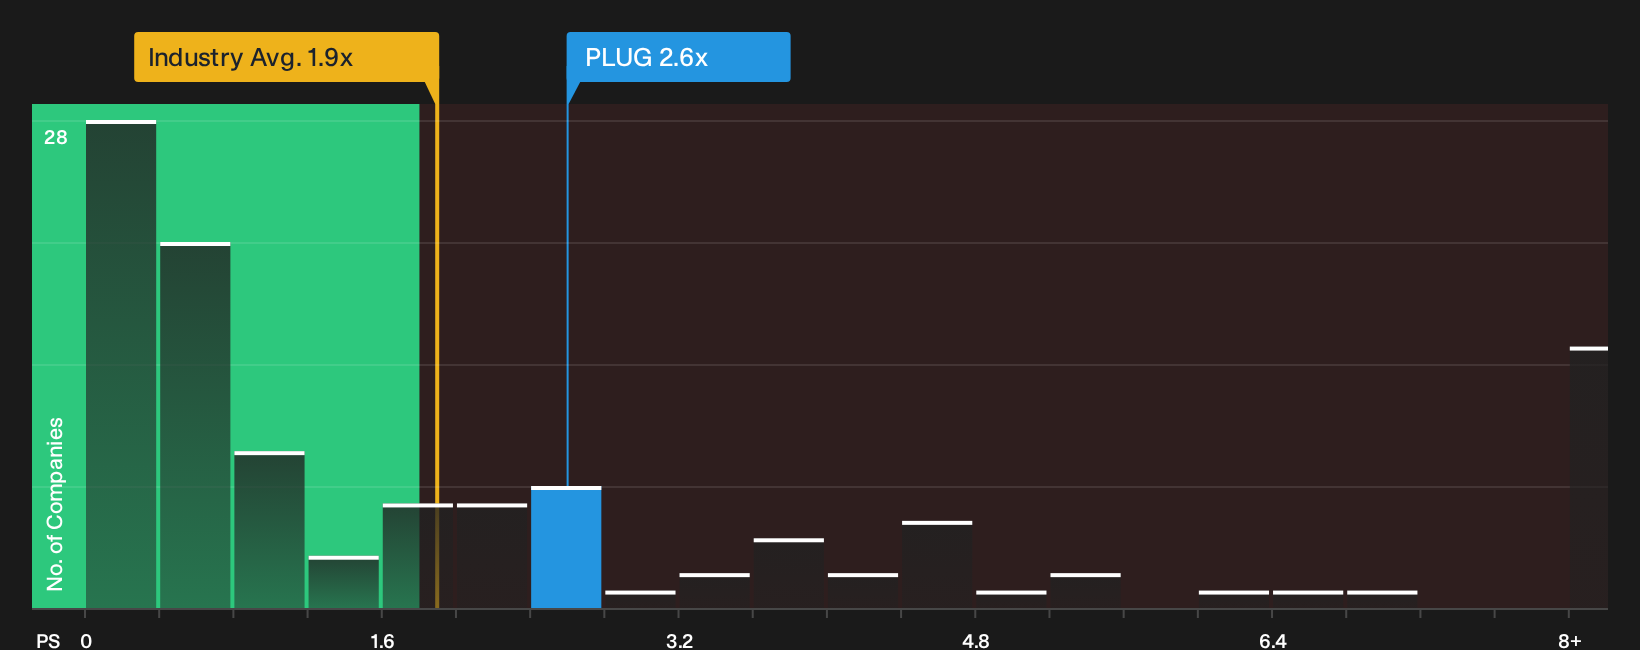
On a simple sales yardstick, Plug Power screens as pricey. The P/S ratio sits at 2.6x, compared with 1.9x for the US Electrical industry and 1.6x for peers, while the fair ratio estimate is 0.6x. That kind of gap points to real valuation risk if sentiment cools.
Numbers alone do not tell you whether that risk is worth taking. They only flag how much optimism is already in the price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Concerned by the split signals around Plug Power’s valuation and execution story? Use the data to stress test your own thesis, then weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Plug Power?
If Plug Power has you rethinking risk and reward, you can use that momentum to refresh your watchlist with other opportunities that match your goals.
- Target greater upside potential by screening for companies that combine quality fundamentals with attractive pricing using the 29 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night holdings by filtering for businesses with 30 resilient stocks with low risk scores that keep volatility in tighter check.
- Strengthen the core of your portfolio by focusing on financially robust companies through a list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com