


Equifax has just enjoyed a sharp rebound on the back of fresh earnings news, and the jump puts a spotlight on whether the current share price lines up with the profit stream that backs it. With the stock now around US$187, the core issue for you as an investor is how that price stacks up against the company’s earnings power.
- Over the past 5 years the stock has delivered a decline of about 29%, which makes the recent upswing an important test of how much earnings strength the market is now pricing in.
- Recent earnings and revenue news, alongside new data and verification services such as the expanded open banking partnership and mortgage tools, can shape how reliably Equifax converts its information assets into cash flows that support its valuation.
- Your read on Equifax is one view; the desks covering it have another. See what analysts think Equifax's shares could be worth.
The stock's next move may depend on whether Equifax's current earnings are strong and durable enough to justify where the shares trade today.
If you want to test the same earnings question Equifax now faces across a wider field, scan a curated set of 29 high quality undervalued stocks.
Does Equifax Look Pricey on Earnings?
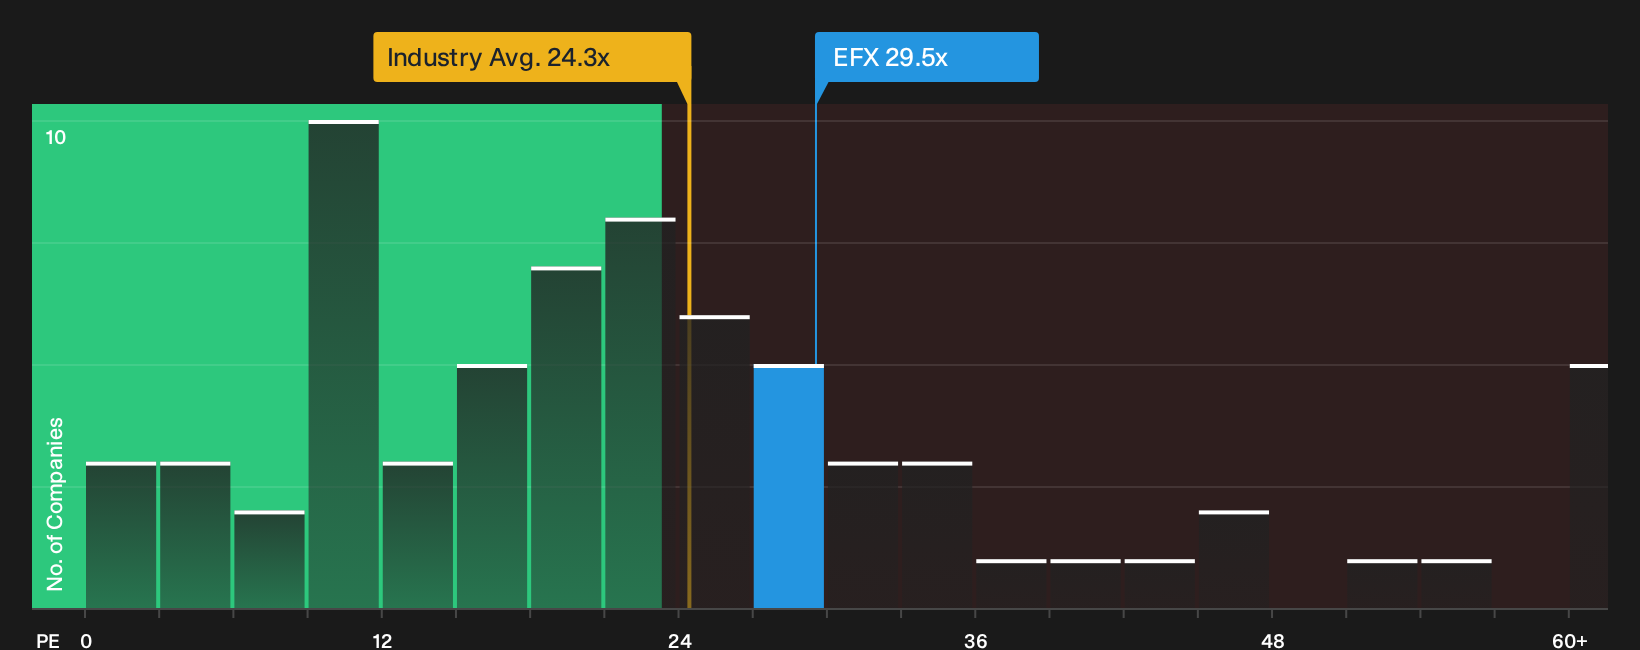
The P/E ratio fits Equifax because earnings remain a key anchor for how investors value data and analytics platforms. On this measure, the stock trades on about 29.5x, which is close to the 29.8x peer average and higher than the wider Professional Services industry on roughly 24.3x. That leaves Equifax priced at a premium to the broader group of service providers, while lining up more closely with direct competitors.
The fair multiple implied by a more tailored model that factors in margins, growth profile, size and risks comes in below the current P/E. This points to Equifax screening as overvalued on this yardstick. Despite the strong Q3 earnings release in 2026 lifting the share price, the market is still attaching a richer earnings tag than this framework would suggest. You therefore need to judge whether the recent product moves and open banking push are enough to support that gap. Explore the numbers behind Equifax's P/E valuation.
The Equifax Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Equifax valuation puzzle leaves off by spelling out what kind of future growth, profitability and earnings profile would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one turns that into a concrete thesis about the business that you can watch over time, rather than a single static fair value snapshot on Equifax's Community page.
Community views on Equifax are now split between one camp that sees more earnings power in the current price and another that thinks mortgage and regulatory risks are being underappreciated.
Bull case: roughly fairly valued
"Rapidly growing Work Number records, now at 217 million active records with 108 million unique Social Security numbers, along with high margin Workforce Solutions revenue and 52.1% segment EBITDA margins, are increasing the share of recurring verification income…"
Discover why this Narrative puts Equifax at roughly fairly valued.
Bear case: 26% overvalued
"Rising use of low cost VantageScore in mortgage and active debate over bi merge or single bureau sourcing increase the chance that regulators or lenders pressure bureau pricing even as Equifax grows The Work Number and alternative data sets…"
Explore why this Narrative puts Equifax at 26% overvalued.
One more Equifax angle that could change your view
Valuation only tells part of the story for Equifax, because separate checks have flagged potential pressure points that deserve a closer look before you put this ticker in a mental box. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com