


Insmed has seen its share price swing sharply over recent years, and with fresh clinical and commercial updates landing, the question now is whether the current valuation is adequately backed by its sales profile.
- Over the past 3 years the stock has gained about 298.1%, which puts a lot of weight on whether the revenue base can carry that kind of repricing.
- Recent progress with respiratory therapies such as TPIP and the launch of BRINSUPRI in Japan may support expectations for future product sales and influence how much investors are willing to pay for each dollar of current revenue.
- The analysts covering Insmed have run their own numbers. See what analysts think Insmed's shares could be worth.
The issue now is whether Insmed's present share price, after a mixed run that includes a large multi year gain and a steep year to date fall, is justified by the level of sales the business is generating.
If you want more context on how a volatile story like Insmed compares with others, a focused stock screen built around 36 healthcare AI stocks can be a useful next step in your research.
Where Does Insmed Sit on Sales?
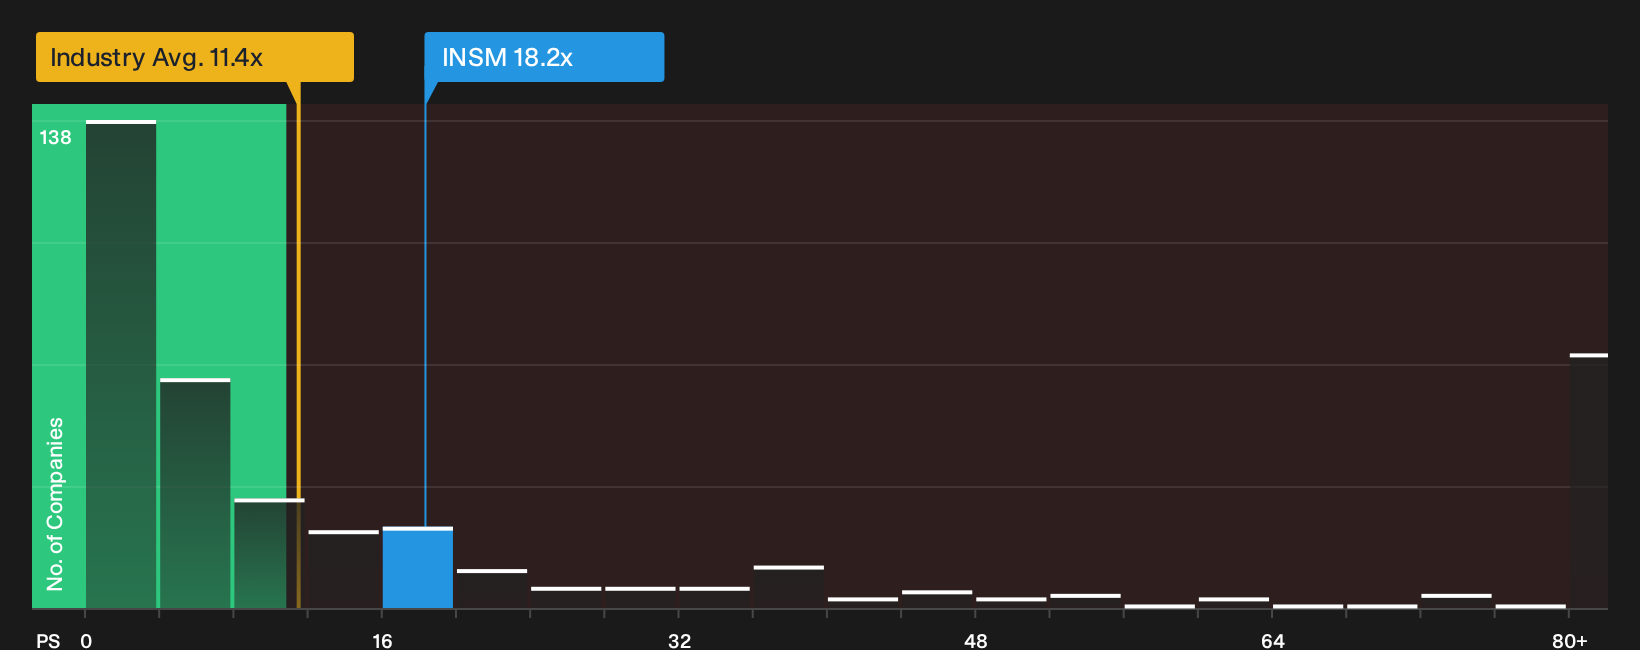
P/S is usually a useful lens for Insmed because the business is still loss making and revenue is the cleaner anchor than earnings. On this yardstick, Insmed trades on a P/S of 18.2x, compared with a Biotechs industry average of 11.4x and a peer group around 8.0x, which puts a clear premium on its current revenue line.
The fair value framework that blends Insmed's growth outlook, margins, size and risk profile points to a level that sits slightly below where the stock trades today, so the current P/S looks a touch rich rather than outright stretched. Because BRINSUPRI has only recently launched in Japan and TPIP remains in late stage development, the market is already baking in meaningful expectations for that pipeline alongside existing sales. Despite that clinical and commercial momentum, the present multiple still leaves limited room for disappointment on execution or timing, which is important for you to weigh before relying on the P/S alone as a signal. Explore the numbers behind Insmed's P/S valuation.
The Insmed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Insmed pick up where the P/S puzzle leaves off. They spell out which combinations of future growth, profit margins and earnings paths would need to occur for the stock to be worth meaningfully more or less than it is today. Each scenario ties a fair value to a particular mix of potential catalysts and risks so you can track over time which version of Insmed's story is actually unfolding in the market.
One of the top community narratives on Insmed: 52% undervalued
"The anticipated U.S. launch of brensocatib in bronchiectasis in the third quarter of 2025 is described as a major catalyst, with community members expecting it to have a meaningful impact on revenue once it hits the market…"
Discover why this Narrative puts Insmed at 52% undervalued.
One more angle on Insmed that could change how you frame it
Everything so far has focused on what Insmed looks like today, yet professional coverage also sketches out where the business might be a few years from now, giving you another reference point to weigh against the current market price. Explore where analysts expect Insmed to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com