


Analyst earnings expectations put Sherwin-Williams in focus
Fresh analyst forecasts are back in the spotlight as Sherwin-Williams (SHW) approaches its next quarterly update. The Street is looking for earnings of $3.65 per share and higher year-over-year revenue.
Attention also centers on how the Paint Stores Group, Consumer Brands Group, and Performance Coatings Group contribute to that projected performance, since these segments collectively define the company’s reach across professional, industrial, and retail customers.
Recent trading has leaned positive for Sherwin-Williams, with a 1-day share price return of 2.48% and a 30-day share price return of 5.26% taking the stock to $345.63. That short-term momentum builds on a 90-day share price return of 8.86% and a 3-year total shareholder return of 49.32%. This suggests investors have gradually been willing to pay more for its earnings potential while accepting the usual risks attached to cyclical materials exposure.
Scan how Sherwin-Williams compares with other materials stocks showing solid price action and fundamentals using our hand-picked list of solid balance sheet and fundamentals (26 results) today.
Sherwin-Williams now trades at a discount to both its analyst price target and estimated intrinsic value after a steady climb. Is that gap a genuine opportunity, or a warning that the market is still uneasy about cyclicality risk?
Most Popular Narrative: 11% Undervalued
On the most followed view, Sherwin-Williams is worth $389.09 a share, which sits above the last close at $345.63 and frames the current discount as meaningful rather than marginal.
The ongoing plan to open 80 to 100 net new Sherwin-Williams Paint Stores Group locations each year on a path toward roughly 6,000 stores, alongside pruning of underperforming sites, increases the reach of the controlled distribution network and can lift revenue and operating earnings as more professional and commercial customers are brought into the system.
See why 43 investors see Sherwin-Williams as 11% undervalued.
Result: Fair Value of $389.09 (UNDERVALUED)
Still, prolonged softness in new residential and DIY demand, along with pressure from raw material inflation, could challenge the Sherwin-Williams margin story that underpins this thesis.
Find out about the key risks to this Sherwin-Williams narrative.
Another View: Sherwin-Williams looks expensive on P/E
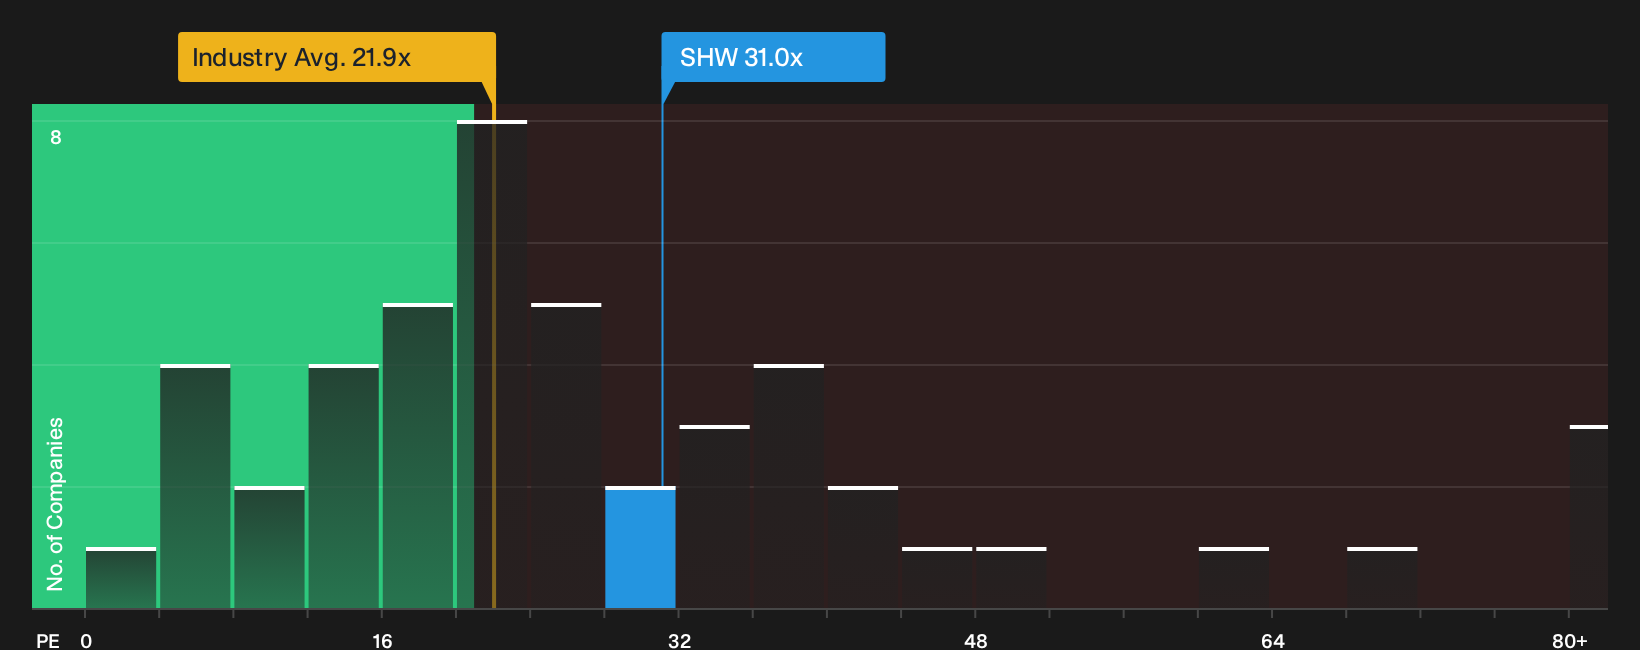
There is a catch. On a simple P/E check, Sherwin-Williams trades at about 31x earnings, while the US Chemicals industry averages 21.9x, peers sit near 21.3x, and the fair ratio is estimated at 21.6x. That rich gap raises the question of whether investors are paying early for the bullish story.
To see how that stacks up against the earnings narrative and where the valuation might settle if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Sherwin-Williams story so far. Check the numbers yourself, move quickly, and decide where you land on its 3 key rewards and 2 important warning signs
Looking for more Sherwin-Williams investment ideas?
Do not stop with Sherwin-Williams alone. Broaden your watchlist with other potential opportunities so you are not relying on a single paint and coatings story.
- Target stability first by scanning companies with stronger balance sheets and healthier fundamentals using the list of solid balance sheet and fundamentals (26 results).
- Hunt for better value by checking out a curated set of quality businesses trading below their estimated worth through the 29 high quality undervalued stocks.
- Build your income stream by reviewing dependable payout options and potential high-yield opportunities using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com