


SailPoint (SAIL) remains in focus after recent trading moves that left the stock around $20.06. Investors are weighing identity security demand against mixed share performance over the past month and the past 3 months.
The recent move in SailPoint to $20.06 comes after a mixed run, with a 90 day share price return of 34.18% contrasting with a one year total shareholder return that is down 9.76%. Short term momentum has cooled after a 1 month share price return that fell 6.13%, which hints that investors are reassessing both growth potential and risk rather than chasing the earlier rally.
Scan beyond SailPoint and review a hand picked list from 20 high quality undiscovered gems that also sit at the crossroads of software demand and shifting investor expectations.
SailPoint now trades near its recent leg higher, with mixed momentum still visible in the chart. Do you commit at this level, or wait for the valuation to offer a wider margin of comfort?
Most Popular Narrative: 8% Undervalued
SailPoint is trading at $20.06 against a widely followed fair value narrative of $21.88. The story now leans slightly in favor of upside while still asking investors to think hard about what kind of growth and profitability they are willing to underwrite.
Ongoing migration of legacy IdentityIQ customers to Identity Security Cloud, supported by flex licensing, unlocks two to three times more ARR per customer and structurally increases the subscription mix and earnings power.
Growing need to secure direct access to structured and unstructured data, and to feed identity context into SOC workflows through Observability and Insights, opens new budget pools in data and security operations, supporting long term revenue and margin expansion.
See why 7 investors see SailPoint as 8% undervalued.
Result: Fair Value of $21.88 (UNDERVALUED)
Still, the SailPoint narrative can crack if larger security platforms close the product gap, or if customers slow their shift from on premises to Identity Security Cloud.
Find out about the key risks to this SailPoint narrative.
Another View: SailPoint Through The P/S Lens
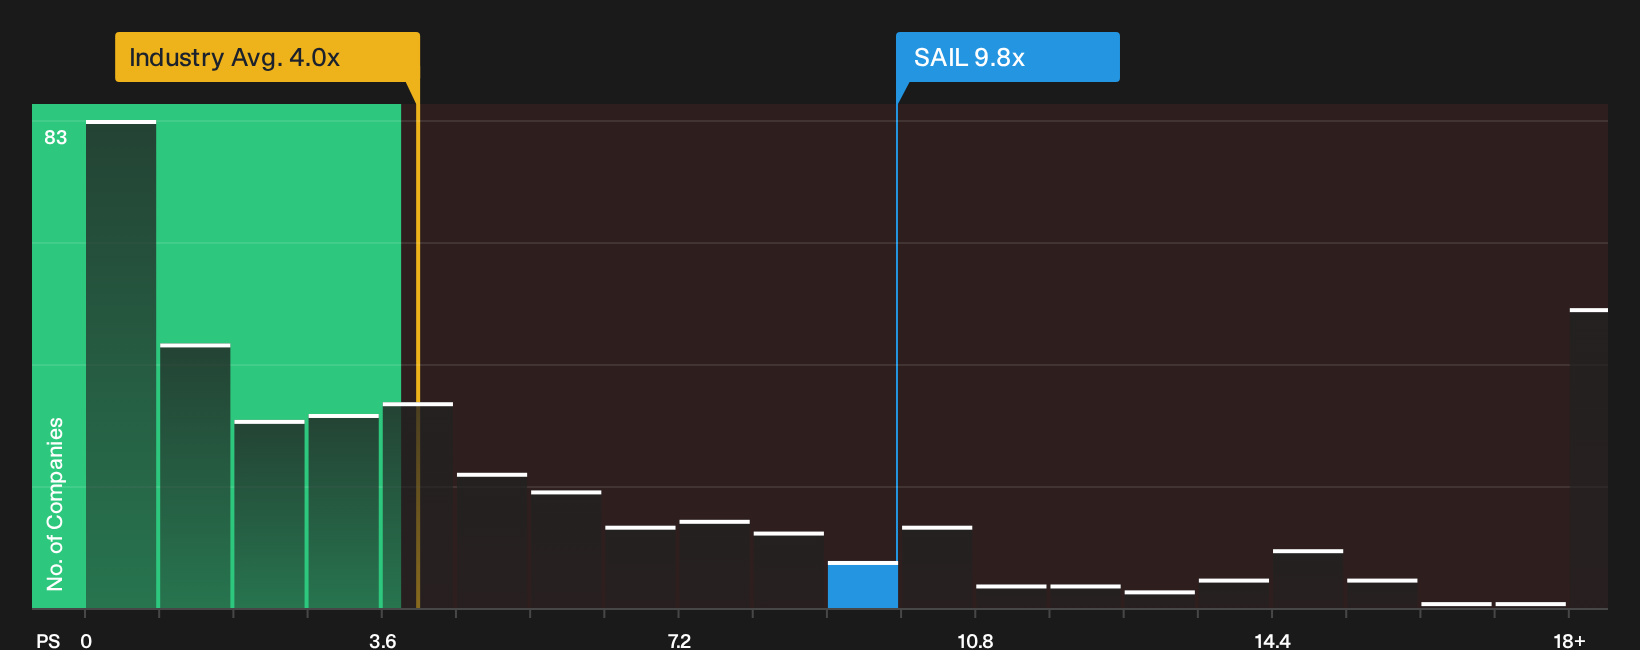
On one hand, SailPoint screens as 7% below an estimated fair value of $21.58 based on future cash flows. On the other, the P/S ratio near 9.8x sits well above the US Software group at 4x and above an implied fair ratio of 6.4x, which points to valuation risk if sentiment cools.
That kind of premium can persist for a while when investors lean into a story, but it also shrinks quickly if expectations reset. The key question is how comfortable you are paying well ahead of both peers and the fair ratio when the business is still loss making.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on SailPoint so far, right, with growth hopes rubbing up against premium pricing and real business risks. If you want to move faster than the crowd and base your stance on the underlying data instead of headlines, take a moment to weigh both sides of the story through the 2 key rewards and 1 important warning sign.
Looking for more SailPoint investment ideas?
If you stop at SailPoint, you risk missing other opportunities that fit your style. Take a few minutes to scan fresh ideas before the market moves.
- Target resilient payouts by reviewing companies in the 6 dividend fortresses that combine higher yields with a focus on income durability.
- Hunt for better value by checking the 29 high quality undervalued stocks where solid businesses trade below what their fundamentals might justify.
- Prioritise staying power by scanning the list of solid balance sheet and fundamentals (26 results) so your next idea starts with financial strength already in place.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com