


Philip Morris International has delivered a powerful run in recent years, and the share price now puts a sharper spotlight on what investors are paying for its earnings. With the stock sitting near US$201.74, the key issue is how that performance lines up with the profit engine behind it.
- Over the past 5 years, Philip Morris International has returned about 164.6%, which raises the question of how much of that gain is grounded in the strength of its earnings.
- Recent updates around smoke free products and a large investment program suggest earnings may increasingly depend on how quickly these newer categories scale and how reliably they convert into profit.
- There is a second opinion on Philip Morris International worth weighing. See what analysts think Philip Morris International's shares could be worth.
The stock's next move may depend on whether the current price can be justified by the level and quality of Philip Morris International's earnings today.
If you are weighing whether Philip Morris International's recent run still lines up with its earnings, it can help to compare that same question across 29 high quality undervalued stocks.
Is Philip Morris International Getting Expensive on Earnings?
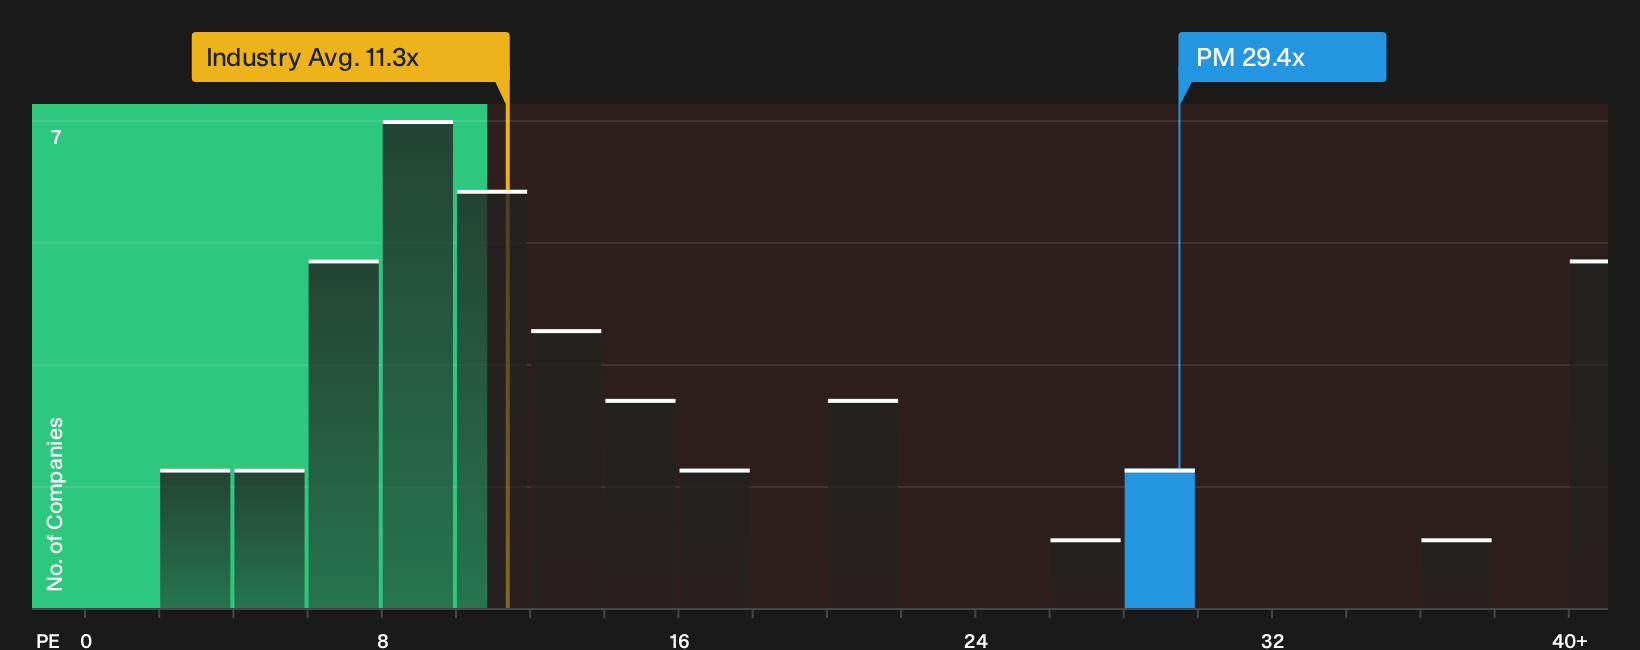
The P/E ratio is a useful yardstick for Philip Morris International because earnings per share sit at the center of how investors frame this stock. Right now the shares trade on about 29.4x earnings, which is much richer than the Tobacco industry average of roughly 11.3x and also above a peer group closer to 23.0x. That gap indicates buyers are paying a clear premium for each dollar of profit.
A more tailored fair P/E, which factors in Philip Morris International's margins, scale, sector and risk profile, sits below the current multiple. On this framework, the stock screens as overvalued. Recent Q3 results beat analyst EPS expectations and kept guidance intact, yet the P/E still runs ahead of what this model suggests as a more grounded level. Investors therefore need to decide whether the smoke free transition and related investment story justify that valuation stretch. Explore the numbers behind Philip Morris International's P/E valuation.
The Philip Morris International Narrative: What Would Justify Today's Price?
Narratives pick up where Philip Morris International's high P/E leaves you by spelling out which paths for growth, margins and earnings would need to hold for the current price to look materially higher or lower over time. They sit on Simply Wall St's Community page. Instead of a single ratio or model output, they lay out the future that number implies so you can watch how the real business performance lines up with those expectations.
Philip Morris International splits opinion, with one camp seeing enough smoke free momentum to justify the current tag and another arguing the recent quarter exposes more questions than the price allows for.
Bull case: roughly fairly valued
"The main thing that has to go right is that PMI continues to grow IQOS and ZYN within a multi category model while using combustibles as a cash engine to fund this shift..."
Discover why this Narrative puts Philip Morris International at roughly fairly valued.
Bear case: 7% overvalued
"Full-year guidance moved from a maintained range with an implied upside bias to an explicit “mid or lower half” framing, for both operating income and EPS..."
Explore why this Narrative puts Philip Morris International at 7% overvalued.
One more angle on Philip Morris International that could shift how you see the current price
There is a separate lens investors often use, which compares where the market values Philip Morris International today with where professional forecasters expect the business to be a few years from now. Explore where analysts expect Philip Morris International to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com