


Corning has turned into one of the stronger long term performers in the US tech sector, yet the recent pullback raises a sharper question for you as an investor. After such a powerful ride, the issue now is whether the current share price lines up with what the business can realistically generate in cash over time.
- Over the past 3 years the stock has gained about 390.2%, which puts a lot of weight on the idea that future cash flows will keep supporting a much higher valuation base.
- A long term supply agreement with Meta and rising prices for specialized optical fiber can reshape expectations for Corning's Optical Communications cash generation, especially if higher value data center connectivity translates into steadier and more visible inflows.
- Prefer to judge Corning on earnings? See why Corning's 56.2x P/E tells a different valuation story.
The stock's next move may depend on whether those cash flows, assessed through a Discounted Cash Flow (DCF) view, are enough to justify where Corning now trades.
If you want a second reference point while you think through Corning and its cash flows, compare it with a focused list of 55 AI infrastructure stocks.
Is Corning a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here uses Corning's current cash generation and projects it forward. Latest twelve month free cash flow sits around $2.5b, and the model assumes those cash flows keep growing rather than shrinking, with analyst and internal estimates pointing to higher levels toward the early 2030s.
At a share price of $123.99, the DCF outputs suggest Corning’s estimated intrinsic value is substantially above where the stock trades today. Because the long term Meta supply deal locks in demand for higher value optical connectivity, the recent strength in that segment helps explain why the cash flow outlook in the model is so robust relative to the current market price. Find out what Corning could be worth using our Discounted Cash Flow (DCF) estimate.
The Corning Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as the bridge from that DCF puzzle to real-world expectations by explaining which assumptions about Corning's future growth, margins and earnings would need to hold for the stock to be worth materially more or less than the current price. They are located on the Community page so you can track how each clearly defined story, with its own view of catalysts and risks, matches what actually unfolds over time.
One of the top community narratives on Corning: 35% undervalued
"The main thing that has to go right is that Corning converts its large optical and solar order book, customer prepayments and long duration supply agreements into the Springboard 20 30 40 plan outcomes…"
Discover why this Narrative puts Corning at 35% undervalued.
One more piece of the Corning story to check
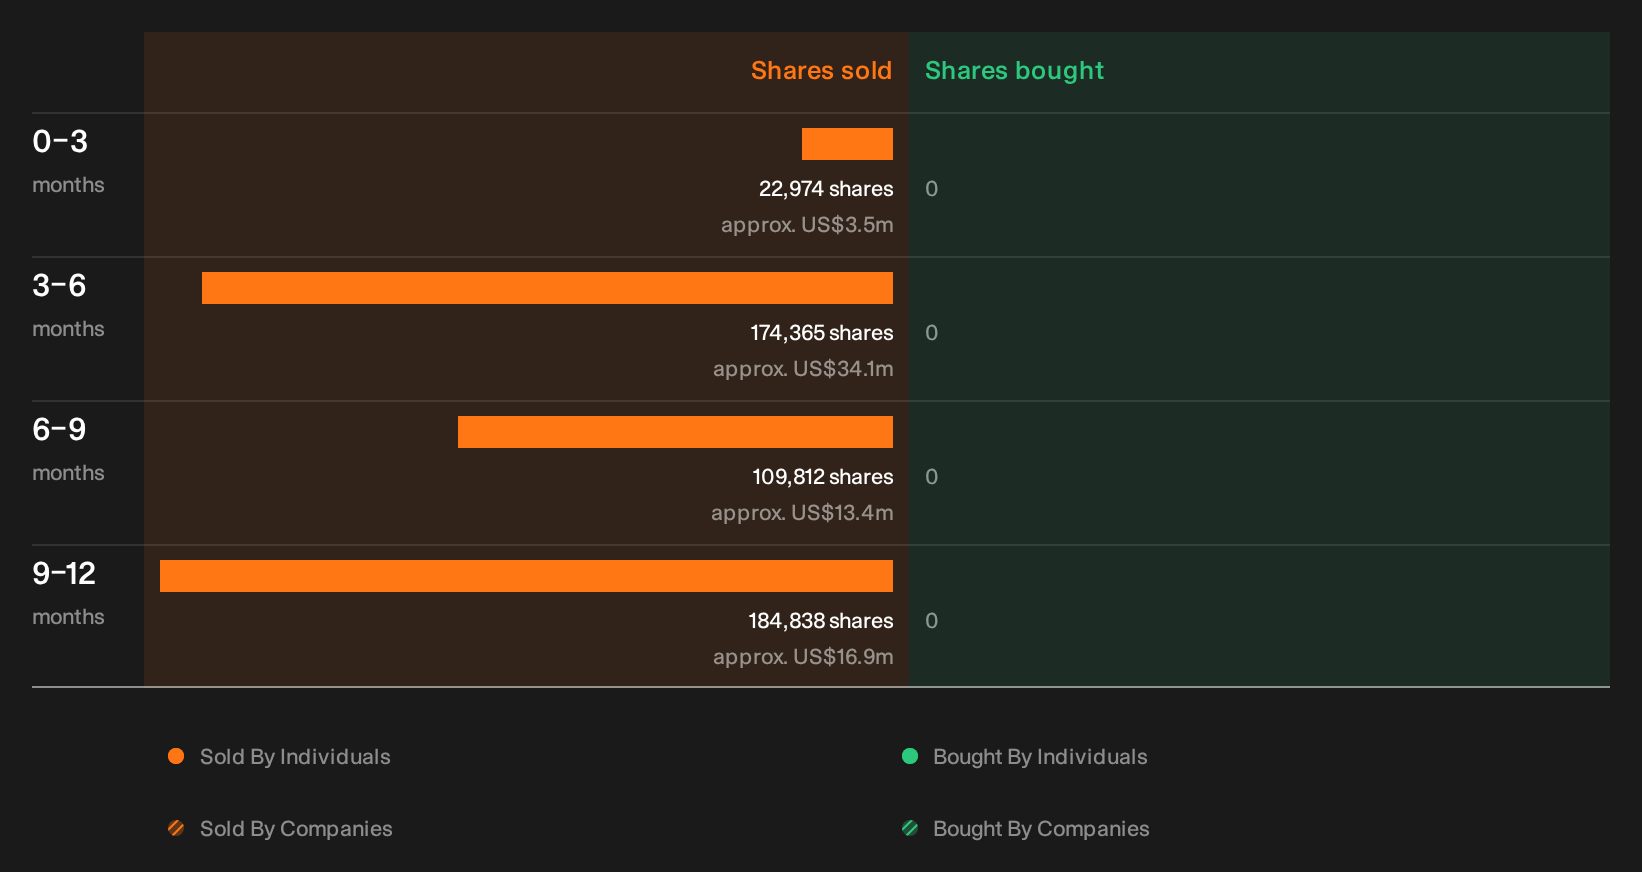
Cash flow models tell one story about Corning, but recent transactions by people inside the business tell another. The specific sellers, sizes and possible signals are waiting for you to inspect. See the recent insider selling flagged for Corning.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com