


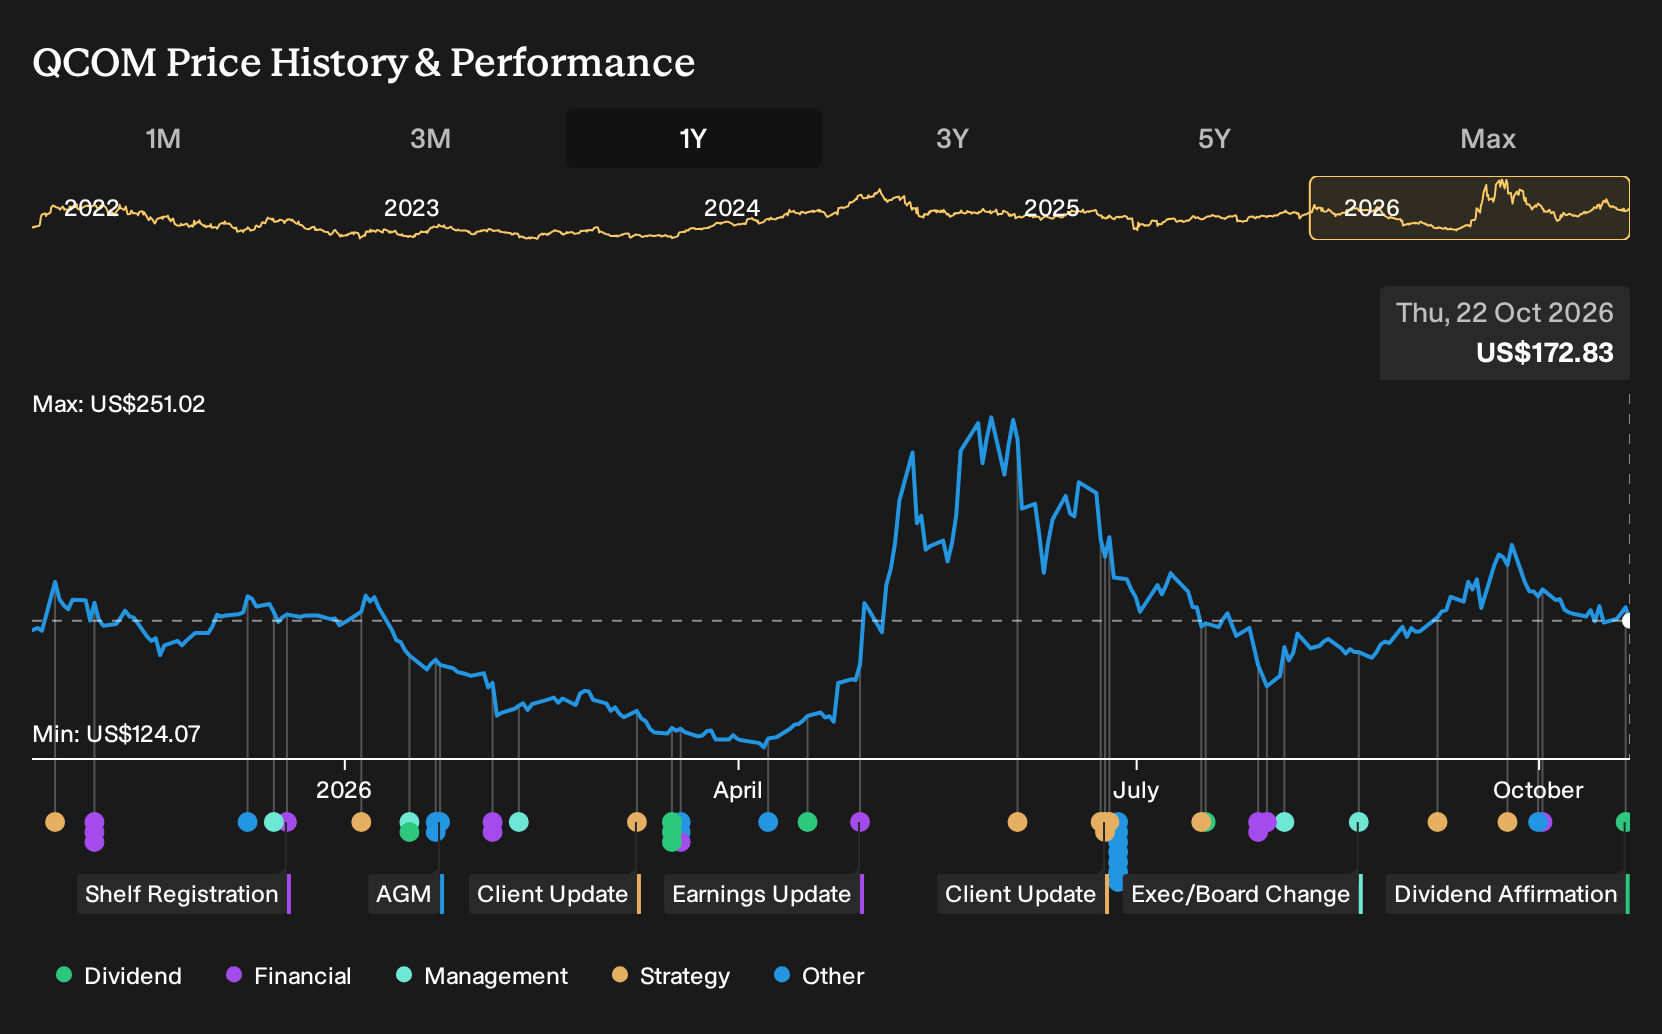
- Qualcomm confirmed a quarterly cash dividend of $0.92 per share, payable on December 17, 2026, to investors of record on December 3.
- The dividend affirmation arrives as Qualcomm faces sector wide pressure from supply chain constraints and questions around the pace of AI related chip spending.
- The next step is to see how Qualcomm's reaffirmed dividend interacts with renewed semiconductor volatility to shape the broader investment narrative.
QUALCOMM Investment Narrative Recap
For an investor to remain with QUALCOMM, the core belief is that management can continue shifting the business toward AI-centric computing, automotive and IoT, while keeping smartphone exposure at a manageable level. The reaffirmed US$0.92 dividend signals no immediate change to capital returns, but it does not materially alter the near-term story on its own.
The key short-term catalyst is execution on upcoming earnings and AI-related design ramps in areas such as data center and automotive, particularly given sector-wide supply constraints and softer handset demand in the background. The biggest operational risk remains concentrated exposure to smartphones and potential execution issues in new AI and compute programs.
The Liquid AI partnership with Qualcomm for AI-powered in-car assistants is one of the more relevant developments alongside the dividend decision. It is directly connected to the effort to grow automotive chip and software revenue, using Snapdragon-based platforms as the hardware foundation for more capable voice assistants and deeper vehicle integration.
For you as an investor, that project highlights how future catalysts may increasingly come from non-handset segments rather than traditional smartphone cycles. It also underscores an execution test. Automotive design wins and software-intensive deployments need to arrive at scale and on schedule, or spending on these programs could weigh on profitability without delivering the intended diversification.
QUALCOMM's analyst narrative points to US$60.0b in revenue and US$11.5b in earnings by 2029, based on an assumed 10.8% yearly revenue growth rate and an earnings increase of about US$2.2b from US$9.3b today.
Uncover why QUALCOMM's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Qualcomm analysts lean hard into one catalyst, which the baseline treats more cautiously. They focus on the AWS agreement and broader AI data center push, with forecasts reaching US$66.9b of revenue and US$11.8b of earnings by 2029. Those views were set before this dividend announcement, so you may want to see how they evolve as fresh information lands.
Explore 6 other QUALCOMM fair value estimates, including one that suggests as much as 74% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your QUALCOMM research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking For More Investment Ideas Beyond QUALCOMM?
Once you have a view on QUALCOMM, it can help to set it alongside other opportunities using the Simply Wall St Screener, so you can see how different businesses line up on quality, income and risk.
- If you are hunting for mispriced opportunities with solid fundamentals, compare QUALCOMM with a curated set of 29 high quality undervalued stocks that may warrant a closer look.
- For readers who care most about steady income, stack QUALCOMM's payout against a group of 6 dividend fortresses and see which ones better match your yield and stability preferences.
- When capital preservation is front of mind, place QUALCOMM next to a selection of 30 resilient stocks with low risk scores and judge whether its risk profile still fits your comfort zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com