


ANZ Group Holdings (ASX:ANZ) is in focus after a shareholder resolution pressed for tougher climate transition rules, while the Suncorp Bank mortgage migration is reshaping offset features and repayment settings for a large borrower cohort.
The climate resolution and Suncorp mortgage transition arrive while ANZ Group Holdings trades at A$40.04, with a 30 day share price return of 5.84% and a year to date share price gain of 9.94% that sits alongside a 1 year total shareholder return of 14.24% and a very strong 3 year total shareholder return of around 90%. Together, these figures point to momentum that has been building rather than fading as investors reassess both the growth opportunities and the risks around regulation, funding and customer churn.
Scan how other banks and financials are pricing in similar regulatory and mortgage pressures by checking our hand picked 6 resilient stocks with low risk scores alongside ANZ Group Holdings.
After a near 10% gain year to date and with climate and mortgage questions growing louder, ANZ Group Holdings now forces a harder look. Does the current valuation still compensate you for those risks?
Most Popular Narrative: 24% Overvalued
ANZ Group Holdings last closed at A$40.04, while the most followed narrative pegs fair value closer to A$32.18, which frames recent share price strength as a stretch rather than a bargain.
At A$32.162 per share, ANZ (ASX: ANZ) appears reasonably valued based on its current operating performance. Cash earnings per share were 126.1 cents for the six months to 31 March 2026. Annualising this figure implies approximately 252 cents per share and a price-to-earnings multiple of around 12.8 times. The most recent 83 cent interim dividend, together with the preceding 83 cent final dividend, represents a trailing cash yield of approximately 5.2% at the assessed price, before considering the partial franking credits.
See why 9 investors see ANZ Group Holdings as 24% overvalued.
Result: Fair Value of A$32.18 (OVERVALUED)
Still, sharper climate commitments or a tougher outcome from the Suncorp Bank integration could pressure ANZ Group Holdings if funding costs or customer churn turn out differently than expected.
Find out about the key risks to this ANZ Group Holdings narrative.
Another View: Our DCF Model On ANZ Group Holdings
The user narrative sees ANZ Group Holdings as about 24% overvalued at A$40.04 against a fair value of A$32.18. Our SWS DCF model tells a quieter story, with ANZ trading only 0.8% below its future cash flow value of A$40.38. This raises a simple question: Is the market leaning too heavily on headline multiples and short term sentiment, or is the DCF giving more credit to cash generation than you are comfortable with?
Look into how the SWS DCF model arrives at its fair value.
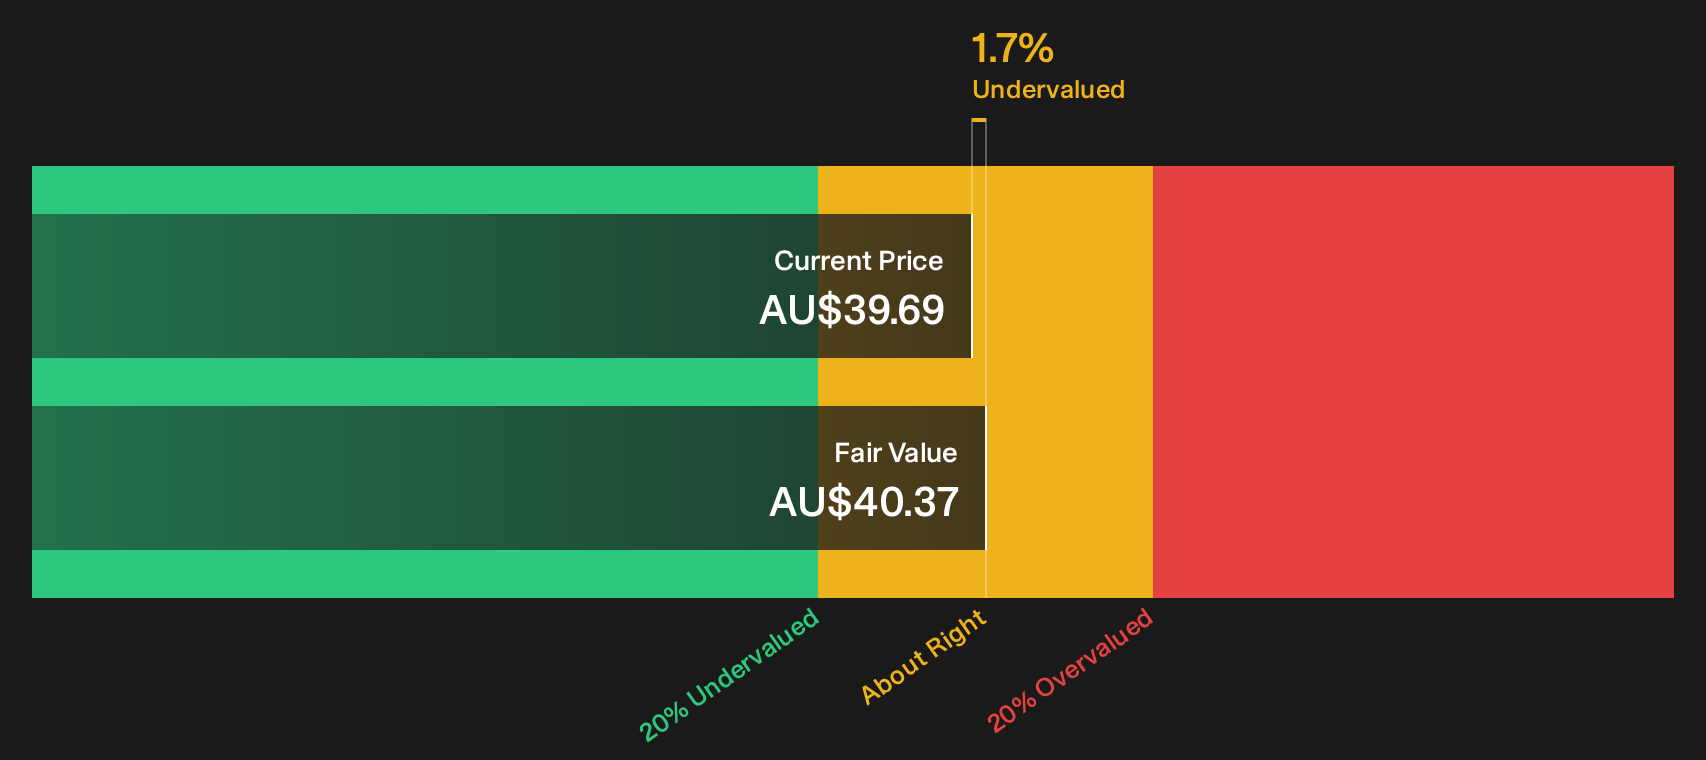
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ANZ Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern feels familiar, use it as a prompt to move fast and stress test ANZ Group Holdings against your own criteria. To weigh those cross currents with structured data, start by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ANZ Group Holdings?
If ANZ Group Holdings sits near the top of your watchlist, this is the moment to widen the field and pressure test alternatives before the next set of headlines lands.
- Target strong balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (12 results) that can anchor the more volatile parts of your portfolio.
- Spot potential value plays early by reviewing a focused 15 high quality undiscovered gems that filters for quality businesses still flying under most radars.
- Build a cash flow engine by lining up reliable income ideas through a purpose built 5 dividend fortresses designed for investors who care about yield and resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com