


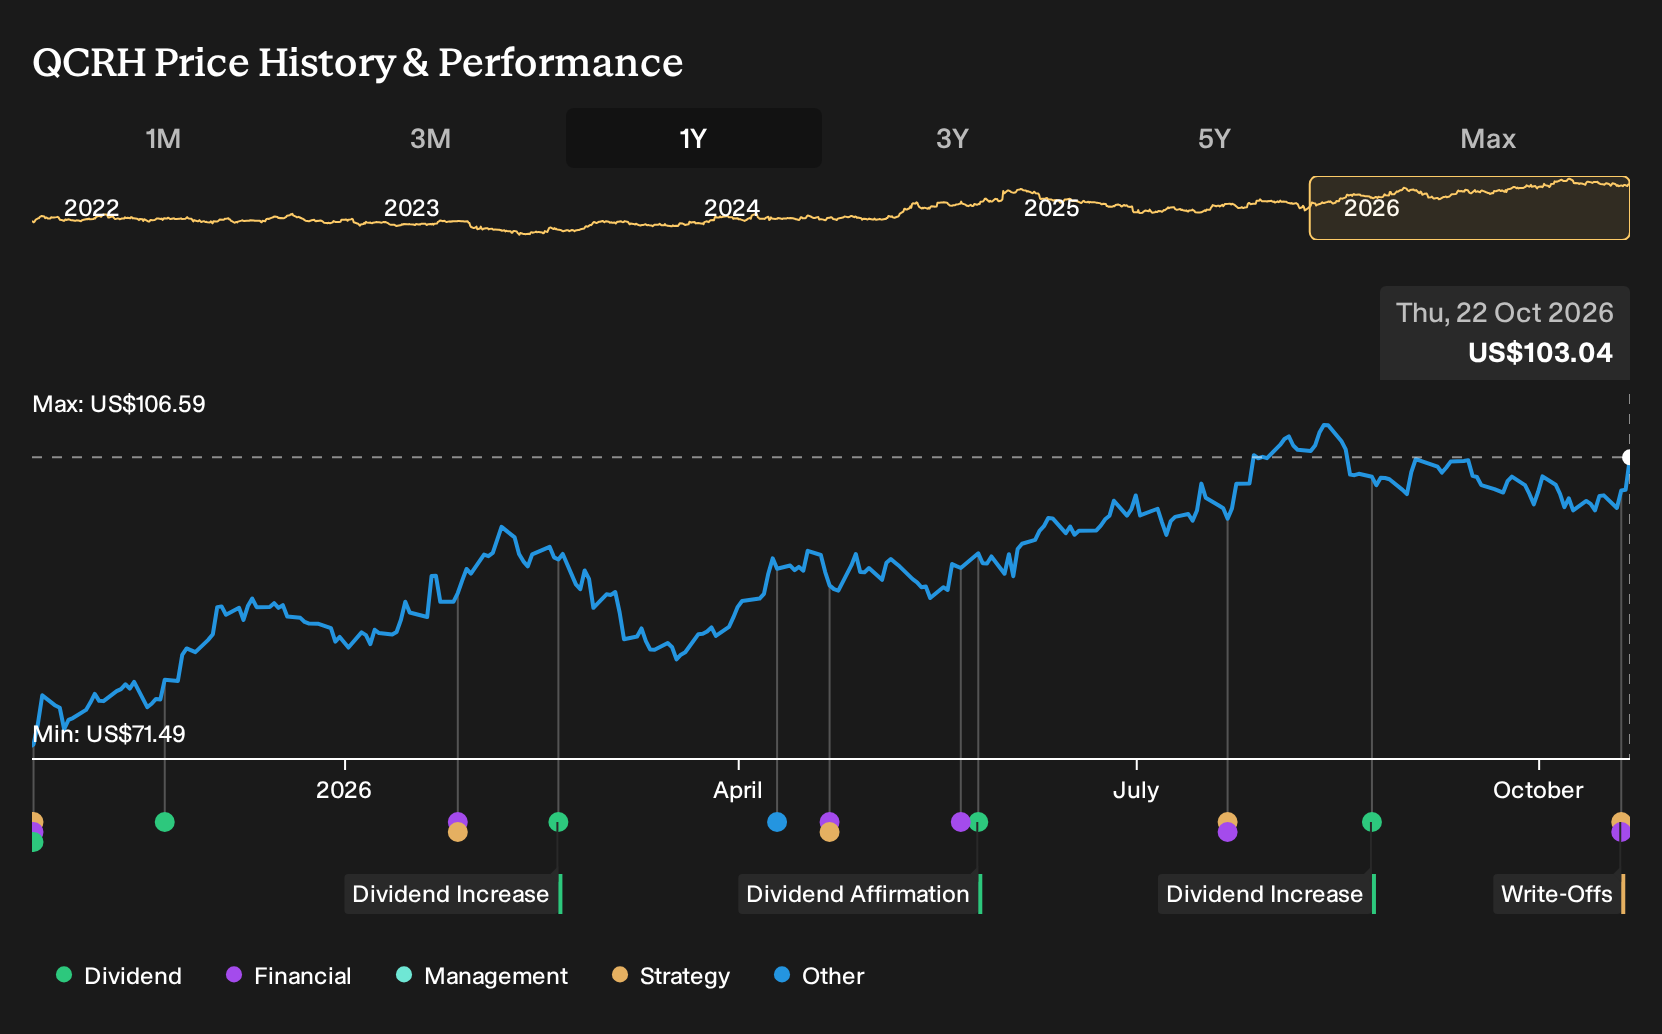
- QCR Holdings reported third quarter 2026 net interest income of US$68.69 million and net income of US$36.43 million, with basic EPS from continuing operations of US$2.23 and net charge offs of US$3.1 million, the lowest level it recorded so far in 2026.
- The bank continues to rely on margin strength, fee income and lower credit losses from the m2 portfolio winddown. In addition, reaffirmed capital markets revenue guidance indicates that management is still committing resources to LIHTC lending, securitizations and related advisory activity.
- We will now look at how QCR Holdings' record quarterly EPS and lower net charge offs might influence the broader investment narrative.
Scan how QCR Holdings’ credit trends and fee strength compare to other banks by jumping into a hand picked set of 30 resilient stocks with low risk scores with similar balance sheet discipline and earnings profiles.
QCR Holdings Investment Narrative Recap
To own QCR Holdings, you need to believe that the bank can keep turning its margin strength, fee businesses and digital investments into consistent earnings while managing credit costs and regulatory thresholds. The latest quarter supports that story. Record EPS from continuing operations and the lowest net charge offs of 2026 point to a fairly clean operating backdrop.
The key short term catalyst is execution on loan growth and fee income, especially in LIHTC and capital markets, without letting expenses run ahead of revenue. The biggest risk still looks like operational missteps in digital transformation or complex LIHTC transactions. This earnings print does not remove those issues, but it does not worsen them either.
The reaffirmed guidance for US$60 million to US$70 million of capital markets revenue over the next year ties directly into this quarter’s print. Management is signalling that the LIHTC lending and securitization engine that helped QCR Holdings deliver strong fee income in Q3 is expected to remain an important earnings driver.
For you as a shareholder, that guidance cuts both ways. It underlines a clear earnings catalyst if QCR Holdings executes on those pipelines, but it also concentrates risk around transaction timing, legal costs and the prior example of a US$1.3 million loss on an LIHTC deal. The investment case hinges on that platform scaling without repeat surprises.
What The Analyst Consensus Implies For QCR Holdings
QCR Holdings' narrative projects US$460.3 million in revenue and US$154.3 million in earnings by 2029. This rests on analysts expecting 6.7% yearly revenue growth and an earnings increase of US$12.3 million from the current US$142.0 million level.
Uncover how QCR Holdings' fair value indicates a 7% potential upside to its current price that may not last much longer.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QCR Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for QCR Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QCR Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond QCR Holdings?
Once you have an initial view on QCR Holdings, it often helps to line it up against other companies with different return profiles, risk levels and income characteristics using the Simply Wall St Screener.
- Prefer steadier balance sheets and fewer unpleasant surprises in credit quality? Compare QCR Holdings with a list of solid balance sheet and fundamentals (26 results) that share a similar focus on financial resilience.
- Hunting for potential mispriced opportunities instead of just following consensus? Scan a curated 29 high quality undervalued stocks that may warrant a closer look on your watchlist.
- Looking to complement a bank holding with income focused ideas? Filter for 6 dividend fortresses that might suit an investor who prioritizes regular cash returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com