


Energy infrastructure used to be boring. Now it is on the front line of geopolitics, climate rules and capital flows, as storage tanks, pipelines and LNG terminals sit between stressed supply chains and rising energy security worries. That mix creates pressure, but also openings for investors who can sort resilient operators from potential value traps. This article walks through three globally listed energy infrastructure stocks exposed to these new forces and what that might mean for your watchlist.
The stocks covered next are just a sample, and the full screen surfaced 23 more energy infrastructure operators with equally compelling stories that do not fit into a short article. To go straight to the broader opportunity set, use the Global Energy Infrastructure & Storage Operators screener to identify, filter and analyze the highest conviction ideas in this theme.
Mullen Group (TSX:MTL)
Mullen Group runs trucking, warehousing and specialized industrial services across Canada and the U.S., moving everything from parcels to heavy energy equipment along key overland routes.
Mullen Group plays into the energy infrastructure theme through its overland freight and specialized services that keep fuel, equipment and construction materials moving between pipelines, terminals and onshore projects. With a market value of about CA$2.8b, the stock gives investors exposure to energy supply chain logistics, where one unseen pressure on funding costs could meaningfully sway margins and future expansion plans.
Those swings in funding costs and expansion plans make it worth checking the 3 key rewards and 2 important warning signs so you can see what might be masking or magnifying returns.

Gas Malaysia Berhad (KLSE:GASMSIA)
Gas Malaysia Berhad runs natural gas and LPG pipelines and last mile delivery across Peninsular Malaysia, making it a direct play on energy infrastructure and security rather than spot prices. It generated about MYR6.9b from Natural Gas & LPG in 2026 and carries a market value near MYR6.7b.
Gas Malaysia Berhad gives you exposure to regulated gas infrastructure where demand and network volumes are tied to industrial energy needs and security concerns, not day to day price swings. Strong ROE and a 4.55% yield point to a utility style profile; however, the picture can change if funding costs rise or if cash generation tightens relative to that payout.
If you want to see whether that payout is masking strain or headroom, go straight to the Gas Malaysia Berhad financial health report for the full picture on Gas Malaysia Berhad.

Bintulu Port Holdings Berhad (KLSE:BIPORT)
Bintulu Port Holdings Berhad runs LNG, oil and bulk fuel terminals across Malaysia and Brunei, making it a direct play on energy export and storage infrastructure. Port operations contribute about MYR822 million of revenue, with bulking services adding MYR55 million, and the group carries a roughly MYR2.5b market value.
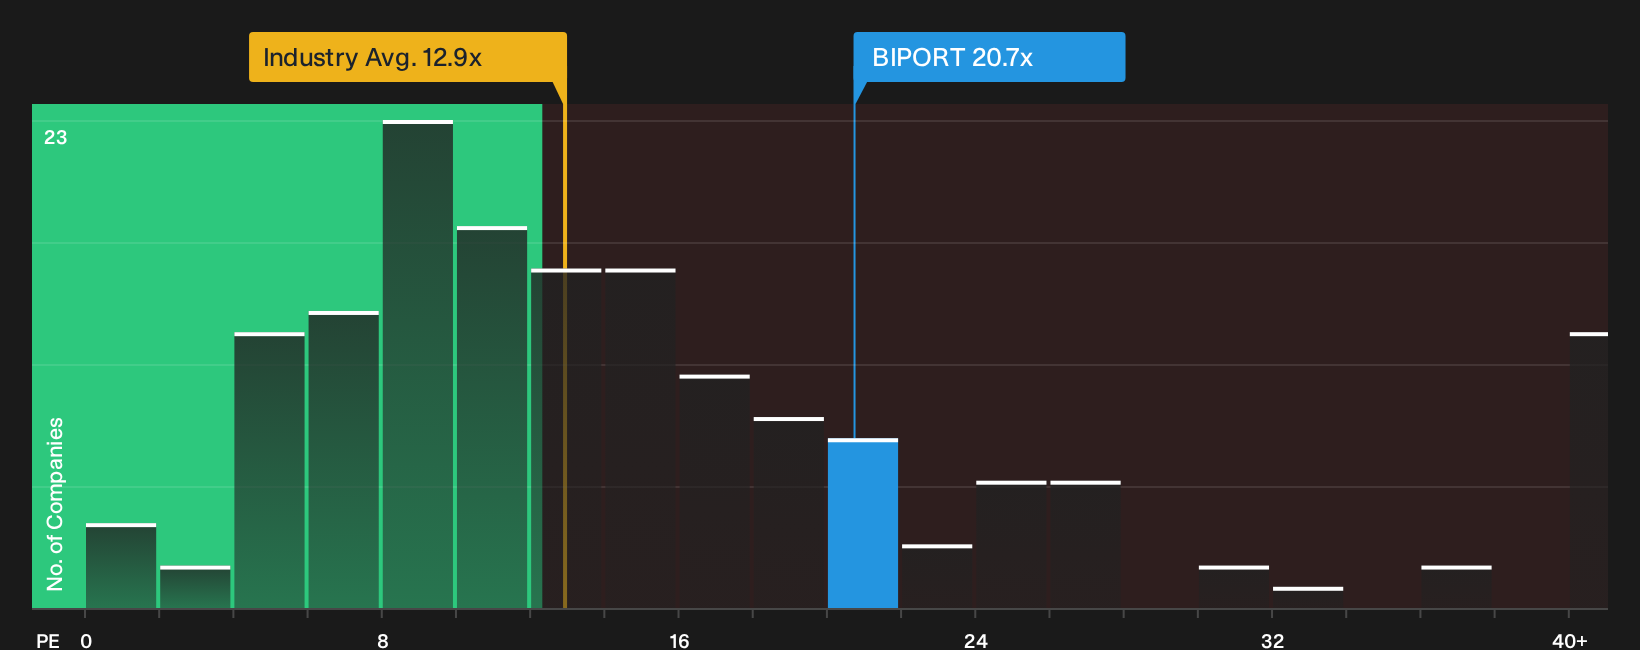
Bintulu Port Holdings Berhad links directly into LNG and fuel flows, with most income tied to port operations that handle energy cargoes and related storage. That theme exposure comes with mixed signals, including premium P/E pricing and softer margins. Investor interest may depend on how one largely unseen factor, namely funding costs and throughput dynamics, evolves over time.
Those shifting funding and throughput pressures make it worth reading the 2 key rewards and 1 important warning sign before deciding whether Bintulu Port Holdings Berhad is quietly compounding or masking strain.
Seeking Fresh Alternatives Before Others Do
New themes move fast. Breakout momentum, flying valuations and dropping entry windows can get away from you before the crowd even looks. Scan fresh ideas while it matters and get in early.
- Spot cash generative opportunities that pair strong balance sheets with sensible valuations by running the list of solid balance sheet and fundamentals (7 results) before they drift onto every watchlist.
- Target future-facing miners by checking the 33 best rare earth metal stocks while many investors are still caught reacting to yesterday’s commodities story.
- Follow the infrastructure and electrification trend by screening the 42 power grid technology and infrastructure stocks to identify potential candidates that may still be under the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com