


Oil has suddenly moved back to the center of the story, with Brent crude around $114 and fresh supply scares from Saudi infrastructure threats, Libyan outages, and rising U.S.-Iran friction. That kind of squeeze can punish some parts of the market and create sharp pricing power for others, which is where the fear of missing out kicks in. This article breaks down 3 integrated oil and gas producers that are directly exposed to this news shock, and explains how the same headlines could signal opportunity or risk for your portfolio.
The three integrated producers below are just a starting sample, and the full screen highlighted 10 more large oil and gas groups with equally compelling stories that do not fit into a short article. To see the wider field, analyze and identify your own highest conviction ideas directly in the Global Integrated Oil & Gas Producers screener.
Hindustan Petroleum (NSEI:HINDPETRO)
Hindustan Petroleum slots into this integrated producers screen as a large refiner and marketer with meaningful upstream and gas exposure, giving you a single stock levered to how crude prices feed through to refining margins and fuel demand in India.
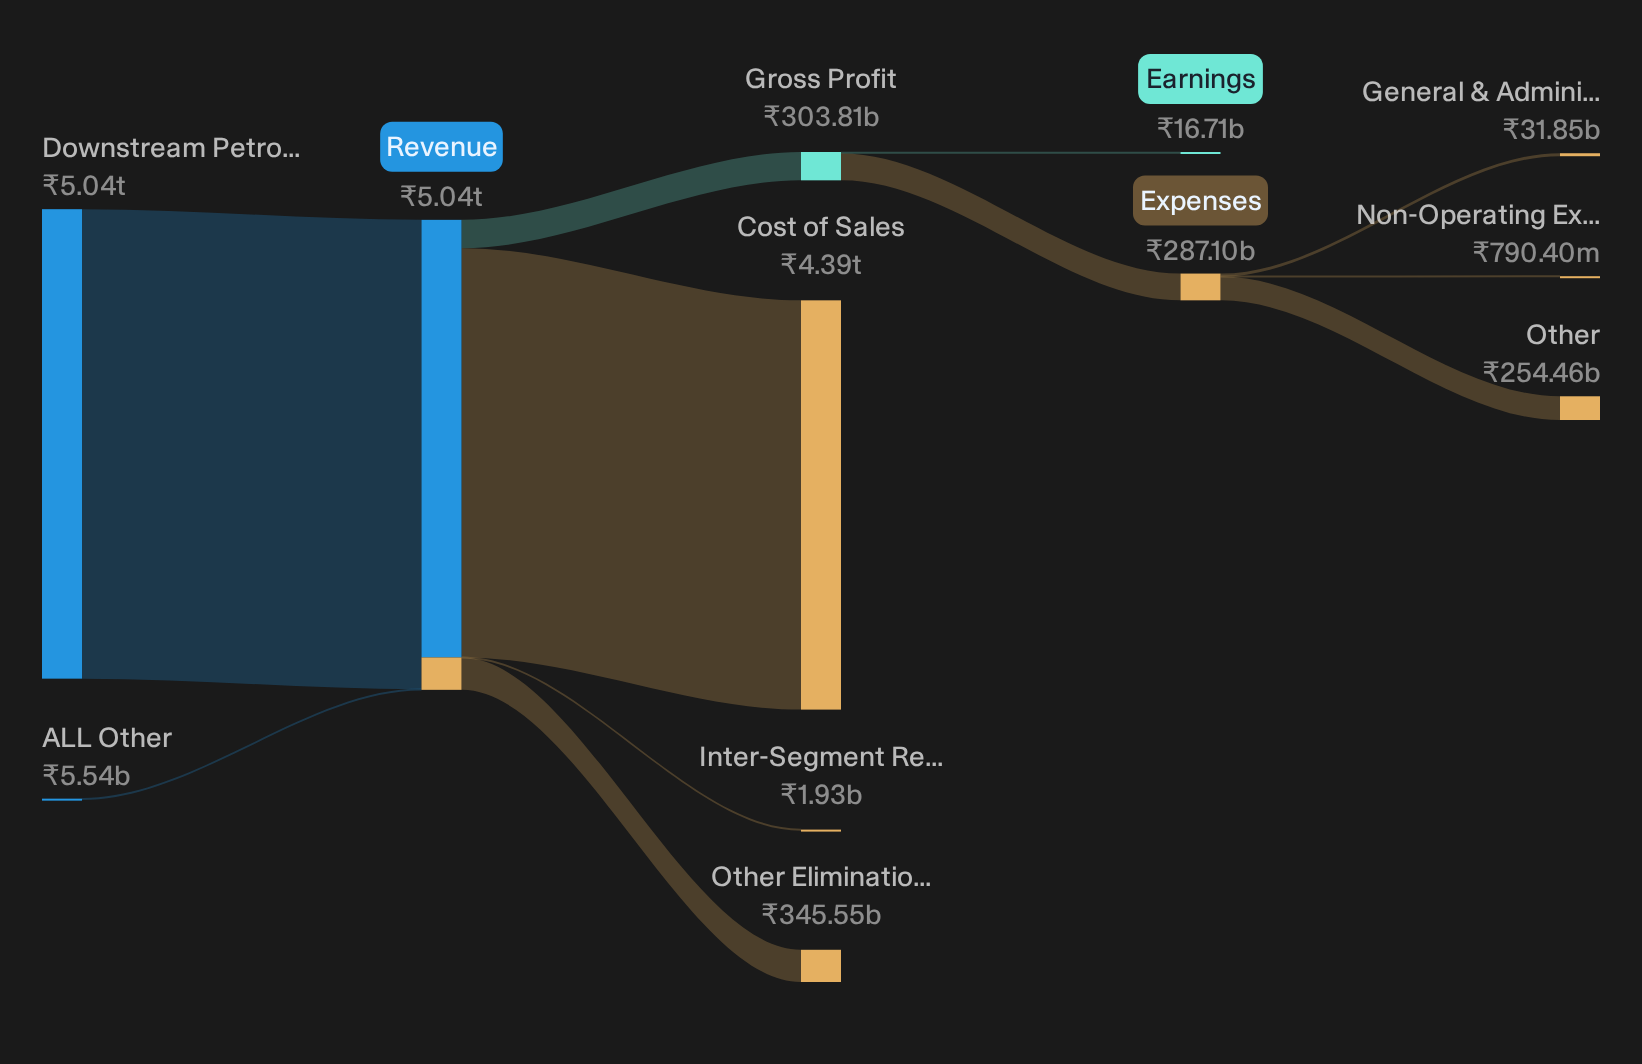
Hindustan Petroleum runs refineries, fuel retail, LPG distribution and broader energy services, with almost all revenue coming from the Downstream Petroleum segment at about ₹5,035,378 million, while the smaller All Other segment adds around ₹5,535 million, and the group carries a roughly ₹725.2b market cap.
Aggressive execution of capacity expansion and complex refinery upgrades is now moving into the monetisation phase, with the Vizag residue upgradation facility commissioned and the Rajasthan refinery running at around 60% utilisation and guided to reach full refining capacity in Q3 FY27. This points to higher distillate yields and a larger contribution to Hindustan Petroleum revenue and EBITDA as these assets stabilise.
What really matters next is how one unresolved pressure shapes the gap between headline crack spreads and the net margins Hindustan Petroleum can actually keep.
If that margin squeeze is what you are watching, the full narrative for Hindustan Petroleum explains how Hindustan Petroleum could see that pressure either ease or intensify as new projects ramp up.
Yantai Jereh Oilfield Services Group (SZSE:002353)
Yantai Jereh Oilfield Services Group links into the Global Integrated Oil & Gas Producers theme as a support player to upstream activity, providing equipment, engineering services, and digital solutions to oil and gas fields worldwide, with a market cap of about CN¥91.2b.
Yantai Jereh Oilfield Services Group gives you geared exposure to higher crude through oilfield spending. It is backed by forecast double digit revenue and earnings growth and a small dividend yield. What really matters is how one unseen pressure shapes the balance between premium growth expectations and the price paid for it.
That growth premium is only half the story, so review the 3 key rewards and 1 important warning sign to see how the upside for Yantai Jereh Oilfield Services Group could be capped or could accelerate.

Chennai Petroleum (BSE:500110)
Chennai Petroleum is a refining focused arm of India’s integrated oil ecosystem, tied closely to the Global Integrated Oil & Gas Producers theme through its crude buying and fuel selling role. It earns about ₹761.971b from its Petroleum Sector and carries a market value near ₹216.54b.
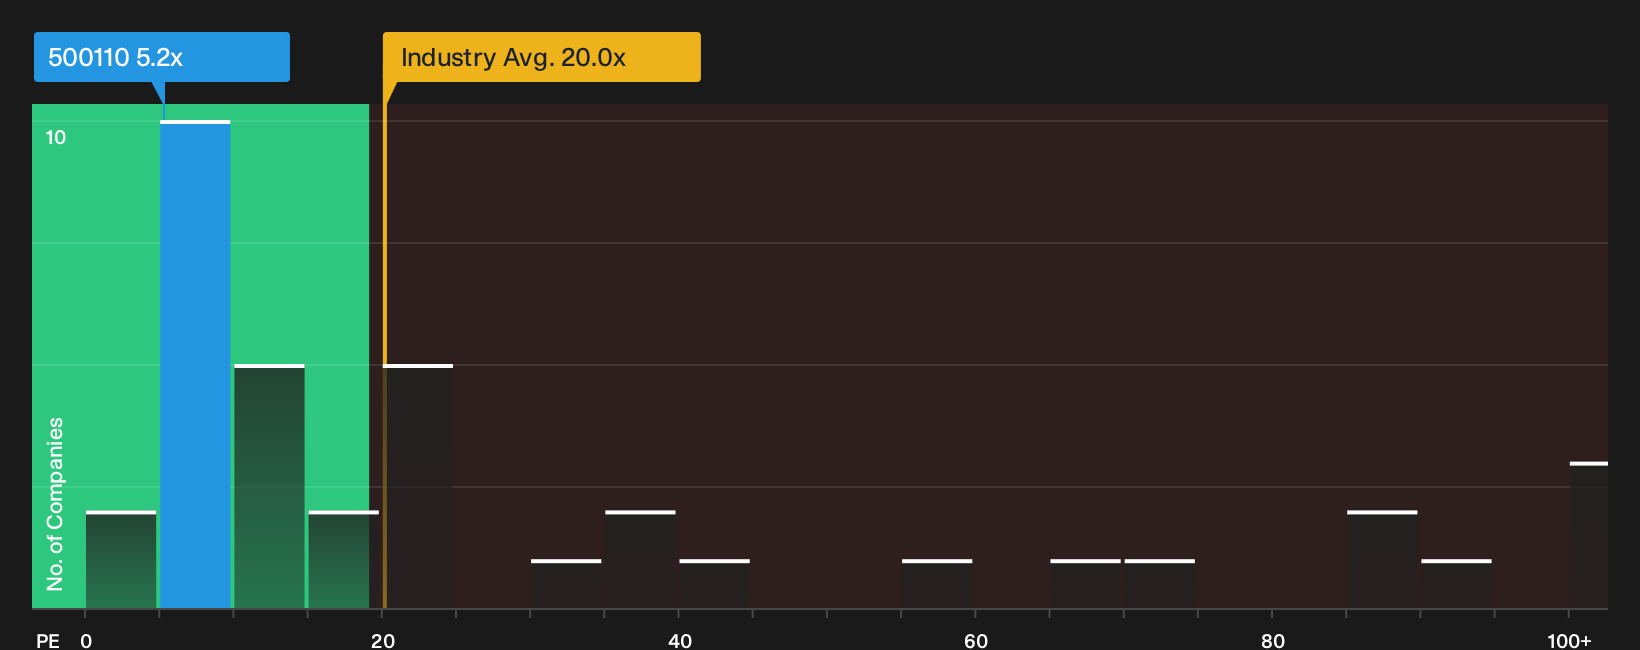
Refining is the whole story for Chennai Petroleum, with crude costs on one side and petrol, diesel and petrochemical pricing on the other. This fits cleanly with a screen built around large integrated energy producers. Profitability has improved and the P/E near 5.2x reflects a refiner that currently trades on a relatively low multiple, with valuation sensitive to changes in assumptions about refining conditions.
That valuation sensitivity is exactly why the 4 key rewards and 2 important warning signs could be useful if you want to see what might re rate Chennai Petroleum next.
Seeking Alternatives Before The Window Closes?
Fresh ideas move first. Breakout stories gain momentum, weak links start dropping, and the best setups get caught early under the radar for now, so consider acting before conditions change.
- Target income that can carry a portfolio through rough patches by using the 226 dividend fortresses before yields are influenced by later entrants.
- Track the companies building tomorrow’s AI infrastructure and use the 55 AI infrastructure stocks while these enablers are still attracting limited attention from many investors.
- Look for growth while still considering balance sheet strength by scanning the list of solid balance sheet and fundamentals (204 results) before any increase in momentum draws in more short term capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com