


GATX has rewarded long term shareholders, yet the recent share price of US$167.50 raises a practical question for anyone looking at the railcar lessor today. Is the current valuation fully explained by the earnings power of the business, or has the market moved ahead of what its profits suggest?
- Over the past 5 years, GATX has returned 91.3%, which puts real pressure on the question of whether the present earnings base can sustain that kind of wealth creation.
- The company relies on long term leases and asset intensive railcar ownership, which can support more predictable income but also ties valuation closely to how efficiently those assets translate into ongoing earnings.
- The analysts covering GATX have run their own numbers. See what analysts think GATX's shares could be worth.
For investors, the debate is whether GATX's current share price is appropriately linked to what its earnings currently justify.
If you are evaluating whether GATX's earnings justify its current price and want a broader context, it may be useful to compare it with 29 high quality undervalued stocks.
Is GATX Fairly Priced on Earnings?
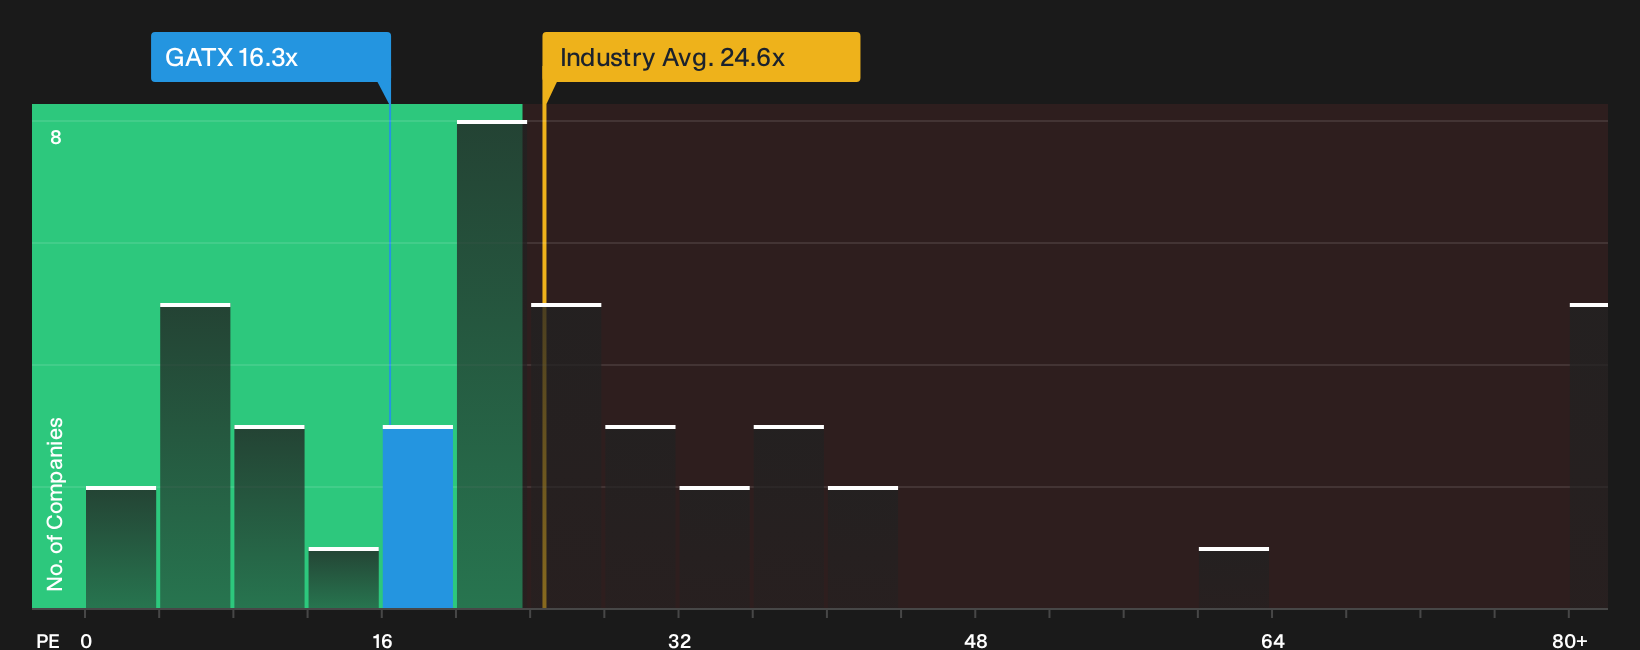
The P/E ratio fits GATX because earnings are a central way investors judge a leasing intensive railcar business. On this measure, GATX trades on about 16.3x earnings, which is well below the Trade Distributors industry average of roughly 24.6x and also under the peer group average near 39.0x. That puts a lot of weight on the question of whether the market is assigning a discount despite the long term leasing profile and capital heavy model.
The fair multiple implied by a more tailored model that factors in GATX's growth profile, profitability, size and risk points to a level only slightly above where the shares trade now, so the current 16.3x sits close on that yardstick rather than at an extreme premium or discount. For anyone weighing an entry point, the key judgement is whether the earnings stream behind that ratio feels durable enough to justify paying roughly this multiple of profits. Explore the numbers behind GATX's P/E valuation.
The GATX Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation question leaves off for GATX by explaining which potential paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today. Each scenario links a grounded fair value estimate to a specific mix of catalysts and risks for GATX's business, allowing you to track over time which version of the story aligns most closely with reality on Simply Wall St's Community page.
One of the top community narratives on GATX: 24% undervalued
"Sustained tightness in North American railcar supply, with GATX reporting around 98% utilization, an 82.6% renewal success rate, mid teens Lease Price Index gains and multi year average renewal terms…"
Discover why this Narrative puts GATX at 24% undervalued.
One more piece of GATX worth checking
The railcar portfolio and earnings multiple tell only part of the story, because the people steering GATX and the way their pay is structured can heavily shape future decisions and risk. See who runs GATX and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com