


Workday stock: AI push and bond financing reshape the story
Workday (WDAY) has rolled out a headless Trusted Agent Platform, new AI agents across HR and finance, fresh integrations with Anthropic and others, as well as multi tranche senior notes that reshape its funding mix.
Recent trading has been brisk for Workday, with the share price delivering a 55.16% 90 day share price return and an 11.56% 30 day gain to reach US$209.99. However, total shareholder return over five years is still down 26.77%, which indicates that momentum has picked up lately even as longer term holders remain underwater.
The cluster of AI product launches and the US$2.5b senior notes offering give investors fresh information to weigh. As a result, the recent share price strength likely reflects shifting expectations about Workday's cash generation profile and the risk attached to its heavier AI and bond financed playbook.
Scan how Workday's AI and bond financed pivot compares to other software players pushing hard into agentic workflows using the hand picked 38 profitable AI stocks that aren't just burning cash.
For Workday, the sharp rebound after years of weak long term returns raises a simple issue. Is the price now tracking business progress on AI and bonds, or a mood swing that the numbers will not support next?
Most Popular Narrative: 62% Undervalued
Against Workday's last close at $209.99, the most followed valuation story pegs fair value far higher, and ties that gap directly to cash generation and AI traction.
The core thesis is simple: three independent data sources, contracted backlog, realized free cash flow, and forward guidance, all moved in the same direction this quarter. That kind of triangulated confirmation is harder to dismiss than any single metric on its own.
See why 17 investors see Workday as 62% undervalued.
Result: Fair Value of $550.10 (UNDERVALUED)
Still, the Workday story can break if AI agent uptake stalls inside that base of 11,500 customers or if margin targets, such as 30.5%, start sliding backwards.
Find out about the key risks to this Workday narrative.
Another View: What Workday’s P/E Ratio Is Saying
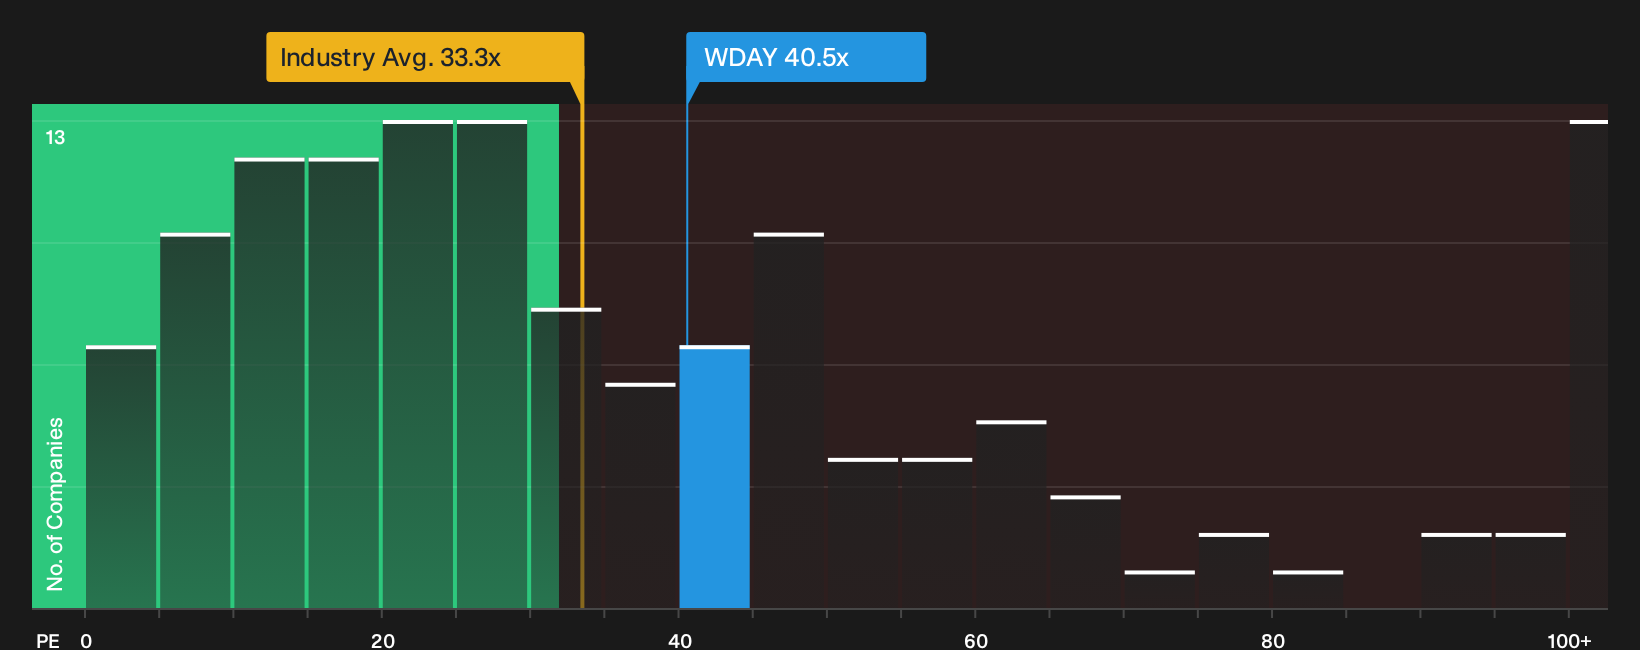
The DCF heavy narrative paints Workday as deeply undervalued. The market’s preferred quick check tells a rougher story. At a P/E of 40.5x, the stock trades richer than the US Software group on 33.3x, above peers at 32.9x, and even above a fair ratio of 37.4x.
That premium hints at less margin for error if growth expectations soften or AI adoption cools. A move closer to the fair ratio or peer levels would put pressure on the share price before any fundamentals change. Which lens do you want to trust when those expectations are tested next?
To see how this earnings based view could evolve if sentiment or growth assumptions change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big claims on valuation and AI momentum can pull you in fast. Check the full picture now and weigh the upside yourself with 3 key rewards
Looking for more investment ideas beyond Workday?
If Workday has sharpened your focus on quality and valuation, you can use that same mindset to scan a wider field of opportunities by applying a few targeted screens.
- Zero in on quality at a discount by reviewing companies on the 29 high quality undervalued stocks that match strong fundamentals with attractive pricing.
- Prioritise resilience and sleep better at night by checking out the 30 resilient stocks with low risk scores that filters for businesses with lower overall risk scores.
- Get ahead of the crowd by tracking the 20 high quality undiscovered gems that highlight underfollowed companies with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com