


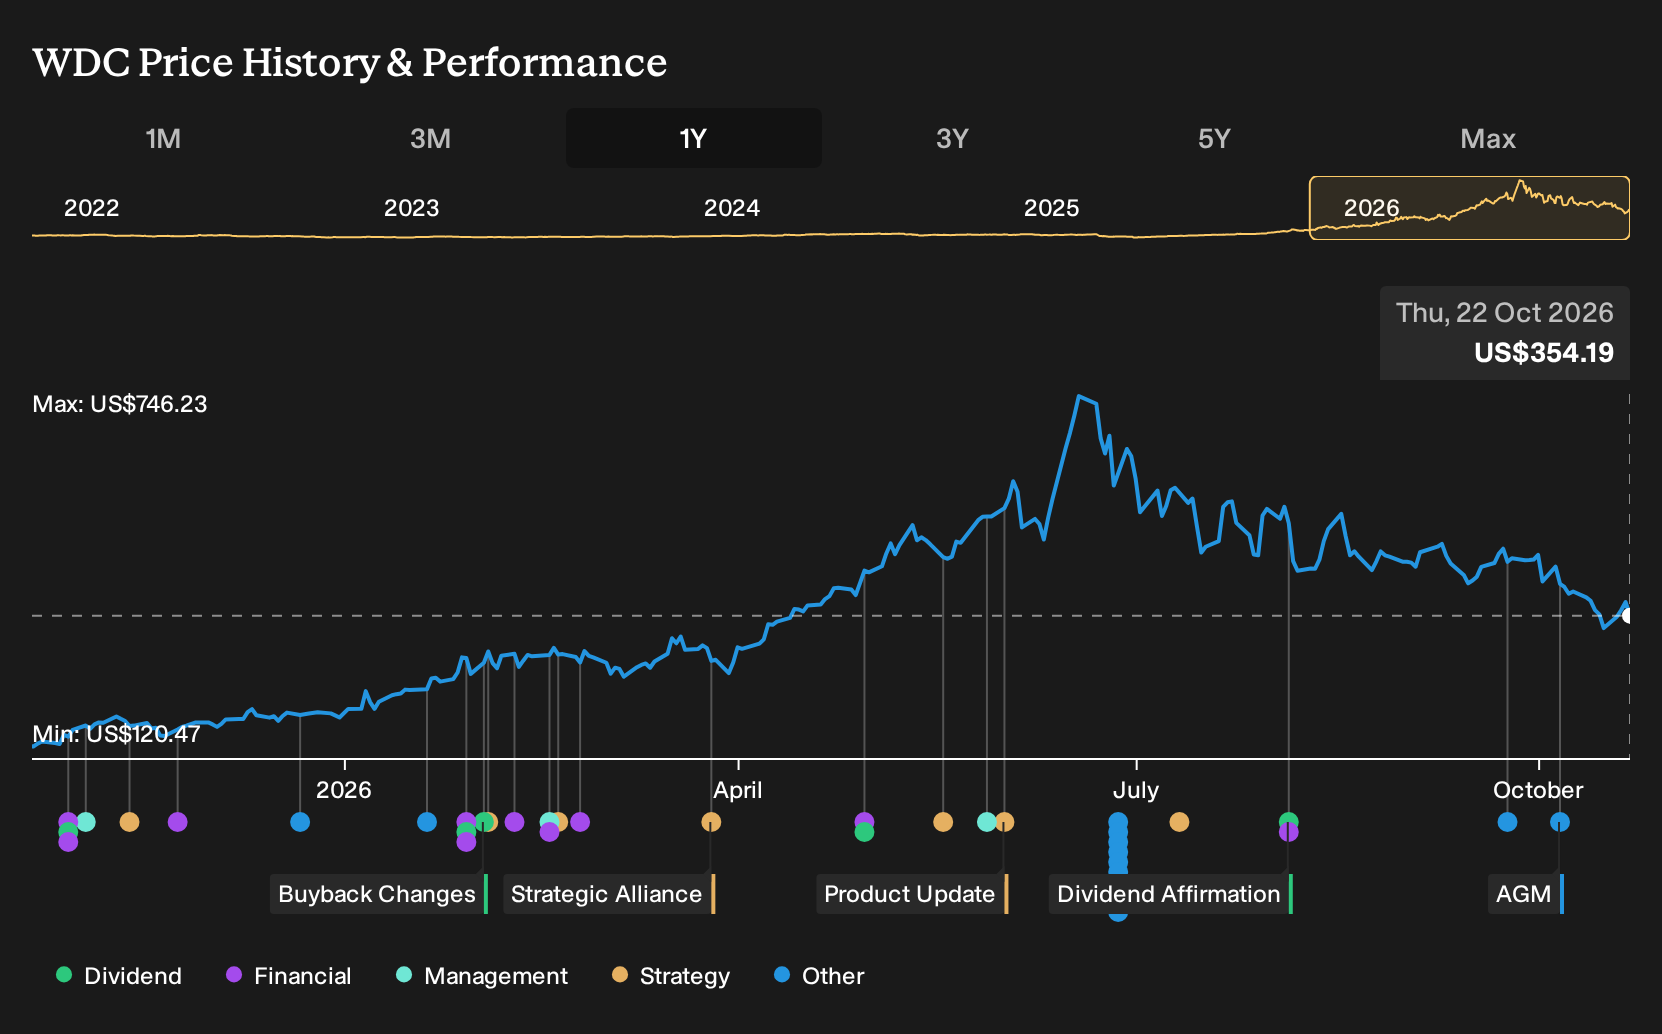
- Western Digital reported fiscal Q1 2027 results on 22 October 2026 with sales of US$4.38b, net income of US$1.78b and basic earnings per share from continuing operations of US$4.86, alongside a 17% increase in its quarterly dividend to US$0.175 per share.
- The combination of strong quarterly profitability, higher forward revenue and earnings guidance, and a larger dividend indicates that Western Digital is responding to robust demand for its storage products while also committing cash to shareholders.
- The focus now turns to how Western Digital's Q1 earnings beat and raised dividend may influence its broader investment narrative and risk profile.
Scan how Western Digital's earnings beat and dividend hike compare with peers by reviewing the hand picked 55 AI infrastructure stocks powering cloud and AI storage demand.
Western Digital Investment Narrative Recap
For Western Digital, the core belief is that cloud, AI and enterprise customers keep leaning on very high capacity HDDs and that the firm executes on its roadmap from ePMR and UltraSMR into HAMR without eroding economics. The latest quarter, with US$4.38b in sales and US$4.86 in basic EPS from continuing operations, reinforces that demand is present today.
The key short term catalyst is continued proof that pricing per terabyte and mix toward higher capacity drives can support margins during the HAMR transition. The biggest risk is still execution and cost control as 44TB HAMR ramps against an already active competitor. The new results and guidance directly tie into both.
The single announcement that matters most right now is Western Digital’s fiscal Q1 2027 report and its stronger forward guidance. Revenue of US$4.38b and basic EPS of US$4.86 came in above prior expectations, while the outlook for fiscal Q2 points to higher projected revenue and improved non GAAP profitability.
For you as an investor, that earnings beat, combined with a 17% dividend increase to US$0.175 per share, feeds into the catalyst that AI and cloud storage demand translates into cash generation, even as capital spending rises for HAMR and higher density products. It also sits alongside the risk that any softer future guidance or HAMR hiccups could quickly reprice the stock after such a strong run.
Western Digital Consensus Forecasts And Valuation Setup
Analysts are effectively sketching a much larger Western Digital by the end of the decade, with revenue forecasts of US$31.9b and earnings projected at US$16.0b by 2029. This outlook assumes yearly top line expansion of 35.2% and an earnings increase of about US$6.7b from US$9.3b today to that US$16.0b consensus level.
Uncover why Western Digital's fair value indicates an 84% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Western Digital’s capital intensity front and center. The most cautious analysts were working off revenue expectations of about US$30.2b and earnings of roughly US$14.6b by 2029, which is below consensus. That sets up a more conservative story. Use this earnings beat and dividend hike as a chance to compare those competing narratives for yourself.
Explore 6 other Western Digital fair value estimates, including one that suggests there could be as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Western Digital research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Western Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Digital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Western Digital?
Once Western Digital is on your radar, it can help to widen the lens and look at other opportunities that match different risk and return preferences using the Simply Wall St Screener.
- If you want potential upside backed by strong fundamentals and valuation support, scan a curated 29 high quality undervalued stocks that may align with a long term buy and hold mindset.
- For readers who care most about resilience and capital preservation, filter for a 30 resilient stocks with low risk scores that score well on stability and financial strength.
- When the goal is to pair quality with underfollowed opportunities, uncover a 20 high quality undiscovered gems that might not yet be heavily covered by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com