


Pinterest (PINS) is under pressure after a securities class action over alleged misstatements on tariffs and advertising, just as Q2 2026 showed revenue growth paired with a swing to net loss and ongoing profitability questions.
Recent trading tells a mixed story for Pinterest. The stock has surged, with a 30 day share price return of 24.69%, yet the year to date share price return is down 13.67% and the 1 year total shareholder return has declined 31.45%. This suggests short term momentum against a weaker longer term record as investors reassess growth potential and legal risk after the new credit facility and the class action filing.
Stress test your Pinterest thesis against other media and internet platforms by scanning a curated 20 high quality undiscovered gems that may be flying under the radar with stronger fundamentals.
Pinterest has just ripped higher while fresh legal and profitability questions hang over the story. Does that recent 30 day surge still leave enough upside in the risk reward for new buyers on valuation grounds?
Most Popular Narrative: 21% Undervalued
On the most followed narrative, Pinterest screens as undervalued, with a fair value estimate of $29.05 against a last close of $22.93. This places the current price meaningfully below that implied level, while the legal overhang and recent loss keep debate alive.
Accelerated international user growth, combined with the current situation where over 80% of users are outside UCAN but account for only roughly 20% of monetization, leaves a wide gap for Pinterest to address through its multiyear sales and go-to-market transformation. This strategy targets improved revenue and profitability from under-monetized regions.
See why 114 investors see Pinterest as 21% undervalued.
Result: Fair Value of $29.05 (UNDERVALUED)
Still, Pinterest’s reliance on under-monetized international users and rising competition for ad budgets from offerings like ChatGPT Ads could quickly put pressure on this undervaluation narrative.
Find out about the key risks to this Pinterest narrative.
Another Take On Pinterest’s Valuation
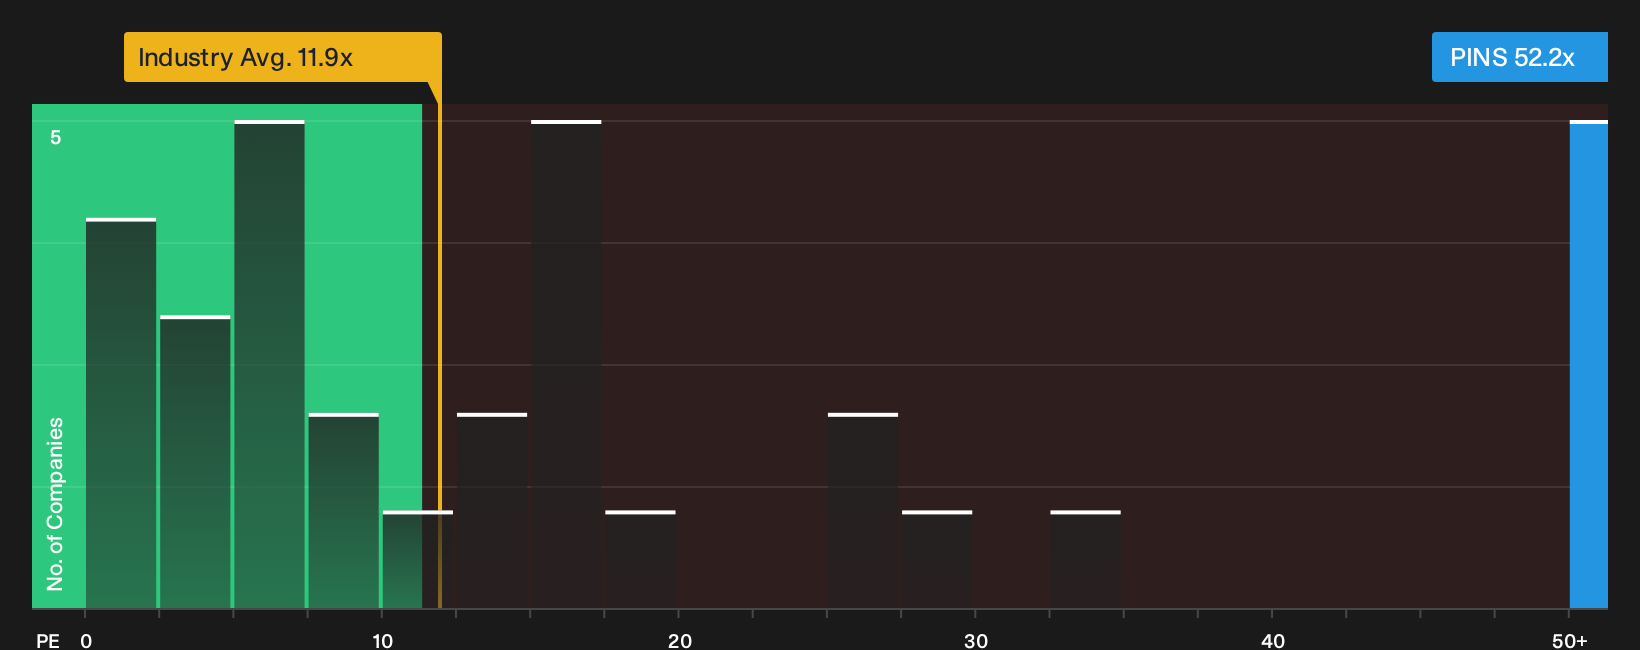
On price multiples, Pinterest tells a very different story from the 21% undervalued fair value narrative. The stock trades on a P/E of 52.2x versus 25.3x for peers and 11.9x for the wider US Interactive Media and Services group, while the fair ratio sits at 29.1x. That gap points to real valuation risk if sentiment on growth or legal outcomes cools, so how comfortable are you paying a premium this steep?
Before leaning on earnings multiples alone, sense check how this premium lines up with your own expectations for Pinterest’s future cash generation and competitive position, then See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Pinterest are clear enough already, so move quickly, pull up the full dataset, then weigh the 2 key rewards and 2 important warning signs against your own judgment.
Looking for more Pinterest investment ideas beyond this stock?
If you stop with Pinterest, you risk missing other opportunities that better fit your goals, risk comfort, and income needs across different corners of the market.
- Target potential mispricing by scanning a curated pool of quality opportunities through the 29 high quality undervalued stocks.
- Strengthen capital preservation by focusing on businesses with robust finances sourced from the list of solid balance sheet and fundamentals (26 results).
- Build a steadier income stream by shortlisting cash return candidates filtered via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com