


- Sonova Holding used its EUHA congress media briefing to showcase Roger On Sphere, an AI-driven remote microphone, and Integro CI, a new cochlear implant sound processor family with TÜV approval and initial launches in key European markets.
- The rollout of AI-powered Roger On Sphere and Integro CI points to heavier investment in advanced hearing tech platforms that could influence Sonova Holding's product mix, capital needs and competitive positioning in hearing care and implants.
- We will now explore how Sonova Holding's AI based Roger On Sphere launch may reshape the investment narrative investors use to judge it.
Scan how AI driven hearing tech is reshaping opportunity by comparing Sonova Holding with a curated set of 127 healthcare AI stocks that are moving on similar themes in healthcare and assistive technology.
Sonova Holding Investment Narrative Recap
To own Sonova Holding, you need to be comfortable with a hearing care leader that leans heavily on AI platforms while running an integrated wholesale and retail model. The key near term swing factor remains execution on higher margin product families and the CHF 90 million operations savings plan. The EUHA launches support that narrative rather than change it.
The biggest operational risk still sits in demand and pricing for Audiological Care and cochlear implants, especially in Europe, and in currency pressure from a strong Swiss franc. Roger On Sphere and Integro CI may help competitive positioning, but they do not remove reimbursement, FX or lead generation risks.
Among the announcements, the Integro CI cochlear implant portfolio looks most relevant for current catalysts, because analysts already focus on lifting profitability in the Cochlear Implants segment after prior revenue pressure. A new processor family with TÜV approval and early European launches directly targets that weaker part of the group.
Integro CI ties into the existing thesis that new features in implants could support sales and earnings, while also testing Sonova Holding’s ability to sell a more integrated two ear system through its retail network. Execution, regulatory approvals in further markets and actual uptake will matter far more than the product headlines themselves.
Sonova Holding’s analyst narrative points to revenue of CHF 4.4b and earnings of CHF 775.8 million by 2029. These projections are based on forecast annual top line growth of 6.8% and an earnings increase of about CHF 238.7 million from CHF 537.1 million today.
Uncover why Sonova Holding's fair value indicates an 11% potential downside to its current price that leaves little room for error.
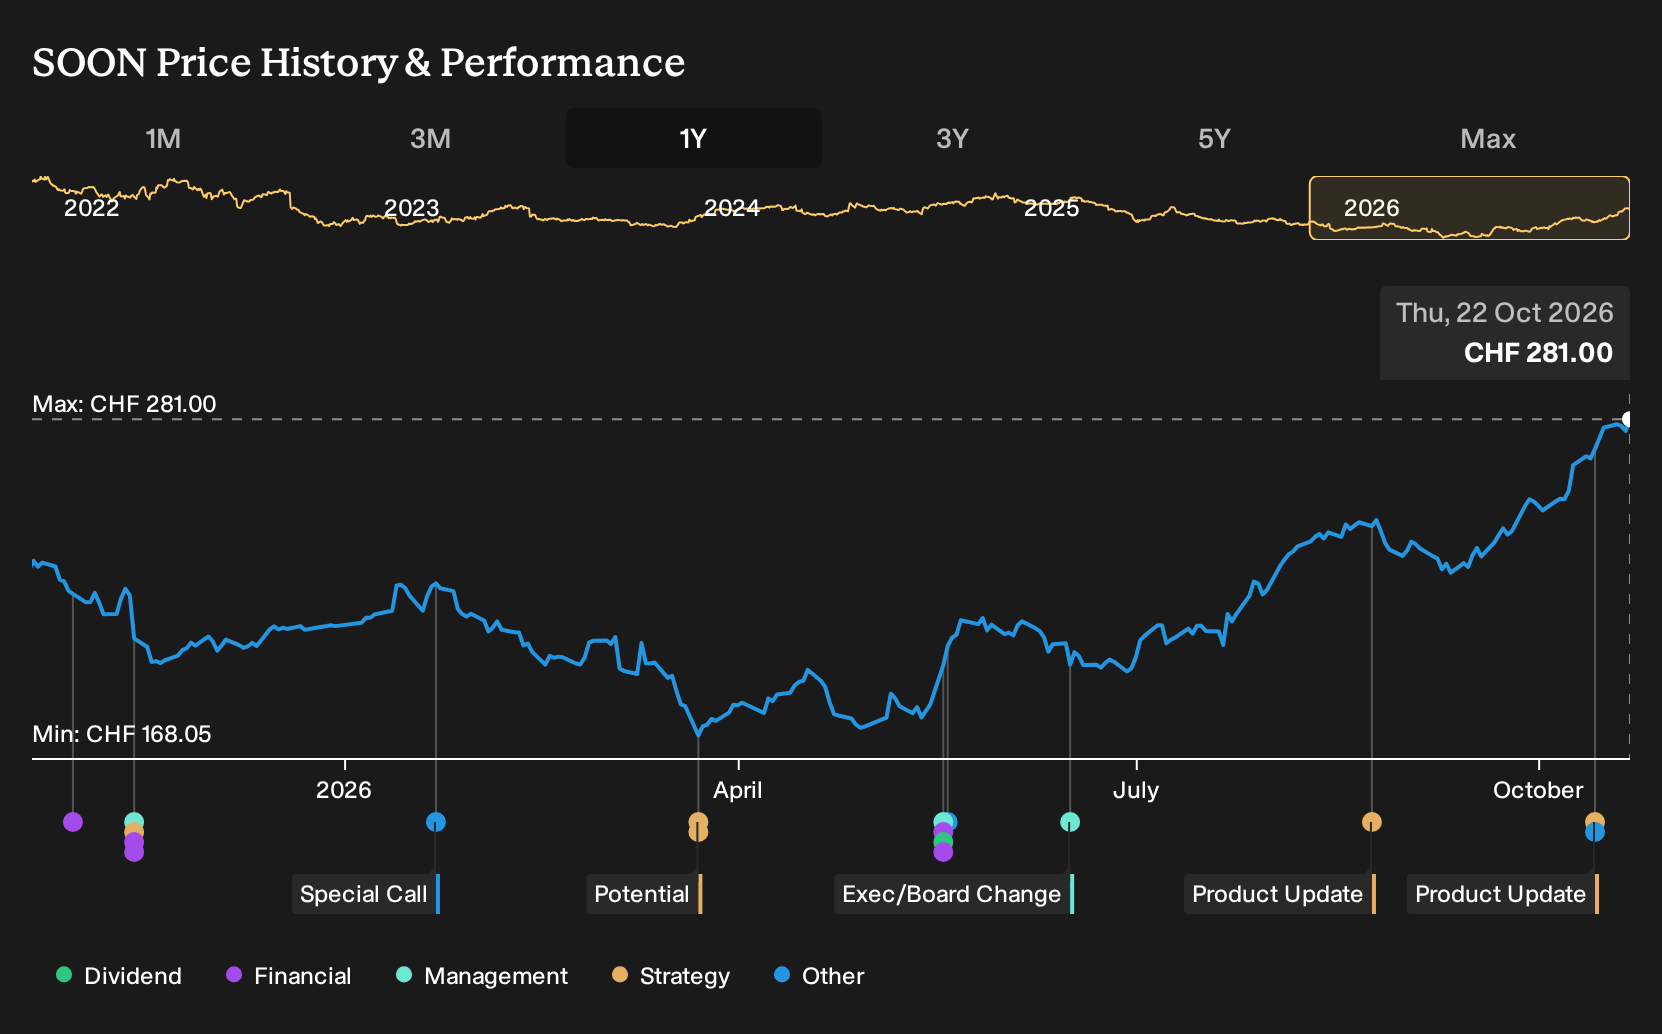
Exploring Other Perspectives
One alternate view does not focus on Sonova Holding’s new AI hardware at all. It zooms in on earnings power if the hearing care platform scales smoothly. The most optimistic analysts were already pencilling in CHF 4.7b of revenue and CHF 902.2 million of earnings by 2029. That is far above consensus, and the fresh EUHA launches may eventually push these narratives further apart.
Explore 3 other Sonova Holding fair value estimates, including one that suggests as much as 69% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sonova Holding research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sonova Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonova Holding's overall financial health at a glance.
Looking for more investment ideas beyond Sonova Holding?
Once you have a handle on Sonova Holding, it can help to widen the lens and compare it with other stocks that match your risk profile and income goals.
- For investors who care most about resilience and capital preservation, consider starting with a curated set of 224 resilient stocks with low risk scores that pair financial strength with lower volatility scores.
- If balance sheet quality is your first filter, sharpen your shortlist by scanning a list of solid balance sheet and fundamentals (204 results) that already screens for robust finances and fundamentals.
- If you are looking for future compounders with cleaner stories and not crowded trades, then a focused group of 618 high quality undiscovered gems can surface candidates that might still be off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com