


Uranium Energy has seen its share price fall back sharply over the past year, yet over a longer horizon the gains remain sizeable. This puts fresh focus on what investors are really paying for relative to its book value. After a stretch of heavy news around its role in the U.S. nuclear fuel supply chain, the question now is how that story lines up with the assets on its balance sheet.
- Over the past 5 years the stock has returned 94.3%. This makes the gap or alignment between that move and Uranium Energy's underlying book value a key issue.
- The creation of a National Security Advisory Council and progress on uranium conversion and in situ recovery projects may support expectations for how efficiently the business can turn its asset base into future earnings and cash flow.
- There is a second opinion on Uranium Energy worth weighing. See what analysts think Uranium Energy's shares could be worth.
The issue now is whether Uranium Energy's current share price is adequately supported by its book value when set against the industry average.
If you want to pressure test Uranium Energy's book value story against other nuclear fuel plays, widen the lens with 16 nuclear energy infrastructure stocks.
Does Uranium Energy Look Pricey on Book Value?
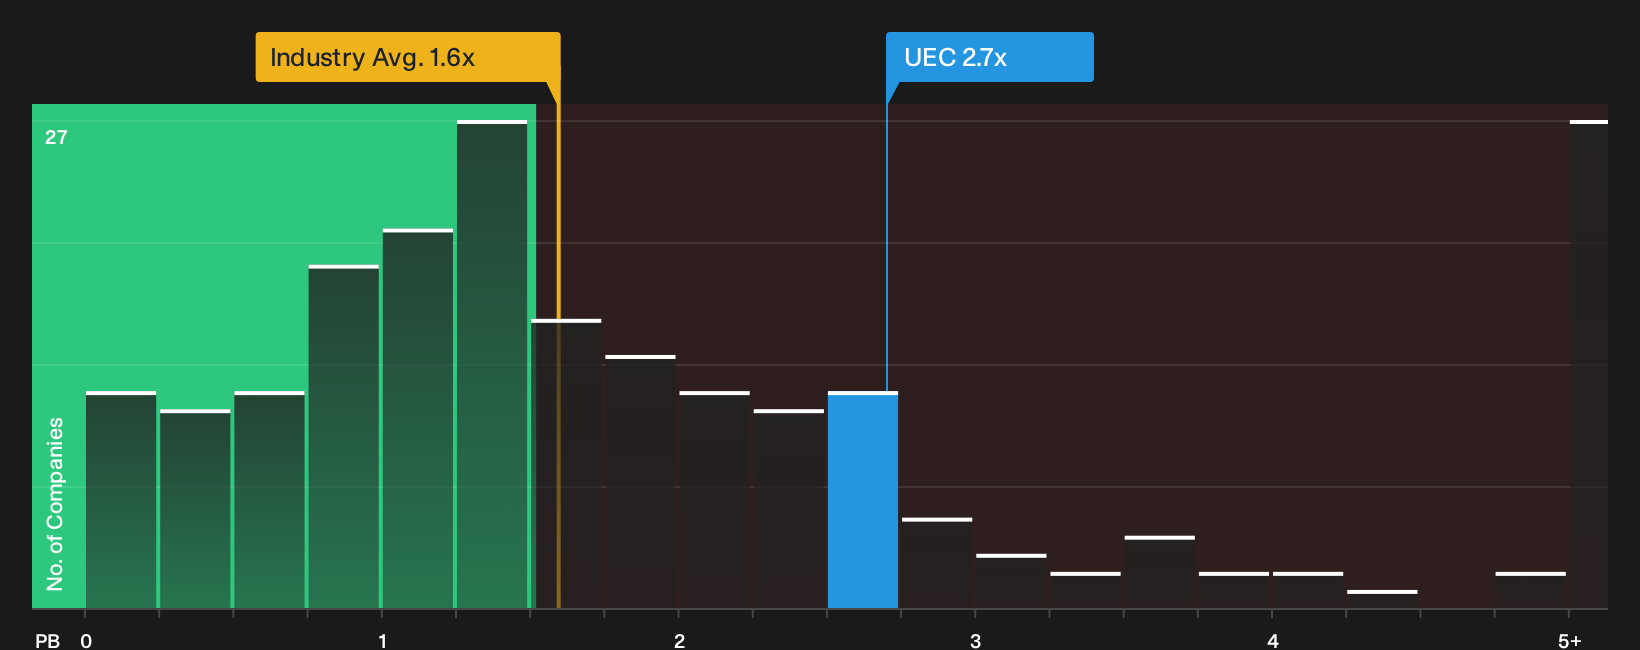
P/B fits Uranium Energy because the business is still building out assets and book value gives you a cleaner anchor than loss-making earnings. The stock trades on a P/B of about 2.7x, compared with an oil and gas industry average near 1.6x and a peer group around 1.6x, so buyers are paying a clear premium to the sector for each dollar of equity on the balance sheet.
The recent push into uranium conversion, including the new National Security Advisory Council, helps explain why some investors may be willing to pay that higher multiple. However, the gap still points to Uranium Energy looking overvalued against typical book value benchmarks. For you as a shareholder or potential buyer, the key question is whether the asset base and future projects can justify paying almost 70% more than the sector norm on this simple balance sheet yardstick. Explore the numbers behind Uranium Energy's P/B valuation.
The Uranium Energy Narrative: What Would Justify Today's Price?
Narratives on Uranium Energy pick up where the book value puzzle leaves off by spelling out which paths for growth, margins and future earnings would need to unfold for the current valuation to look either stretched or conservative. Each scenario ties a fair value estimate to a clear view of Uranium Energy's potential catalysts and risks so you can track over time which broad version of events seems to be taking shape on Simply Wall St's Community page.
One of the top community narratives on Uranium Energy: 55% undervalued
"Launch of United States Uranium Refining and Conversion Corp positions UEC as the only American producer with both uranium and UF6 capabilities..."
Discover why this Narrative puts Uranium Energy at 55% undervalued.
One more Uranium Energy clue before you make a call
There is a whole other lens on Uranium Energy that sits outside book value, rooted in where professional analysts think this business could be a few years from now, and how that compares with the current price. Explore where analysts expect Uranium Energy to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com