


In October 2026, global markets have been marked by a notable shift as investors rotate away from large-cap growth stocks, driven by concerns over AI-related investments and rising inflation pressures. With the Russell 2000 Index experiencing a decline of 3.05% amidst these market dynamics, small-cap stocks with insider buying may present intriguing opportunities for those seeking value-oriented investments in today's volatile environment.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.2x | 0.2x | 47.55% | ★★★★★☆ |
| Timbercreek Financial | 16.7x | 9.7x | 38.52% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.7x | 0.9x | 41.27% | ★★★★★☆ |
| Centurion | 15.7x | 3.0x | 20.37% | ★★★★☆☆ |
| Diversified Royalty | 24.9x | 9.9x | 47.38% | ★★★★☆☆ |
| Franchise Brands | 27.2x | 2.0x | 47.68% | ★★★★☆☆ |
| Linc | 12.1x | 12.6x | 34.03% | ★★★★☆☆ |
| Sagicor Financial | 6.7x | 0.5x | -80.24% | ★★★★☆☆ |
| Meitu | 14.8x | 3.1x | 39.41% | ★★★☆☆☆ |
| Pizza Pizza Royalty | 11.7x | 9.0x | 39.37% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
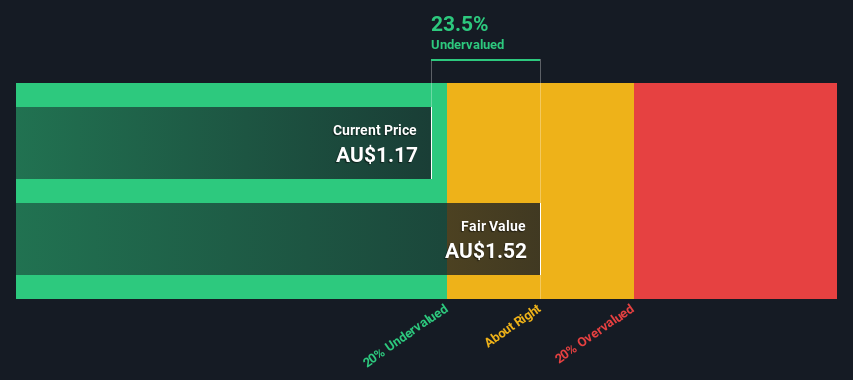
Storage King Group (ASX:SKG)
Simply Wall St Value Rating: ★★★★★☆
Overview: Storage King Group operates in the self-storage industry, providing rental and merchandising services with a focus on offering secure storage solutions, and has a market capitalization of A$1.75 billion.
Operations: The company generates revenue primarily through rental and merchandising, with recent figures reaching A$247.53 million. The cost of goods sold (COGS) was A$54.44 million, contributing to a gross profit margin of 78.01%. Operating expenses totaled A$77.26 million and non-operating expenses were at -A$38.49 million, impacting the net income margin which stood at 62.34%.
PE: 9.2x
Storage King Group, a smaller player in its sector, recently reported sales of A$224.67 million for the year ending June 2026, with revenue slightly up at A$247.42 million compared to last year. Despite a decline in net income to A$154.32 million and earnings per share dropping to A$0.1174, insider confidence is evident through recent share purchases by management within the past quarter. The company relies solely on external borrowing for funding, which adds risk but also indicates potential upside if managed effectively amidst forecasted revenue growth of 7.13% annually over three years despite expected earnings declines.
- Dive into the specifics of Storage King Group here with our thorough valuation report.
Understand Storage King Group's track record by examining our Past report.
Queen's Road Capital Investment (TSX:QRC)
Simply Wall St Value Rating: ★★★★☆☆
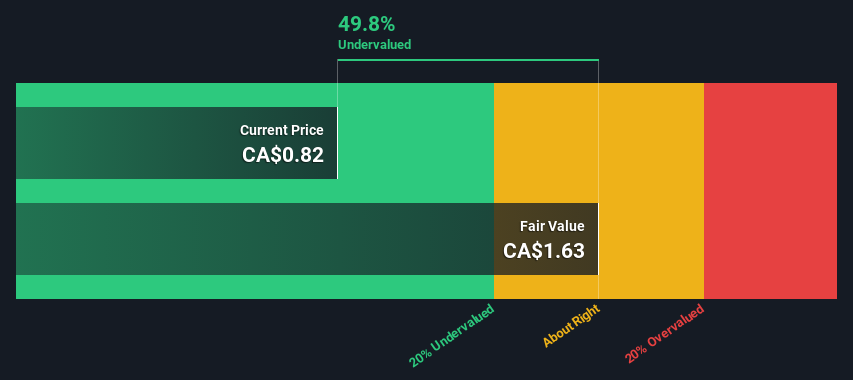
Overview: Queen's Road Capital Investment focuses on the selection, acquisition, and management of investments, with a market capitalization of approximately C$0.29 billion.
Operations: The company primarily generates revenue through the selection, acquisition, and management of investments. It has consistently achieved a gross profit margin of 100%, indicating that its revenue equals its gross profit. Operating expenses have varied over time, with recent figures showing $7.33 million in operating costs for the period ending May 31, 2026. Net income margins have fluctuated significantly, reaching as high as 98.48% in early 2026 but also experiencing negative values during certain periods.
PE: 2.3x
Queen's Road Capital Investment, a smaller company in the investment sector, has caught attention with insider confidence shown through share purchases between January and September 2026. Despite relying on external borrowing for funding, which carries higher risk compared to customer deposits, the firm maintains high-quality earnings driven by substantial non-cash components. This dynamic positions it as an intriguing option for those seeking potential growth within this segment of the market.
Sienna Senior Living (TSX:SIA)
Simply Wall St Value Rating: ★★★☆☆☆
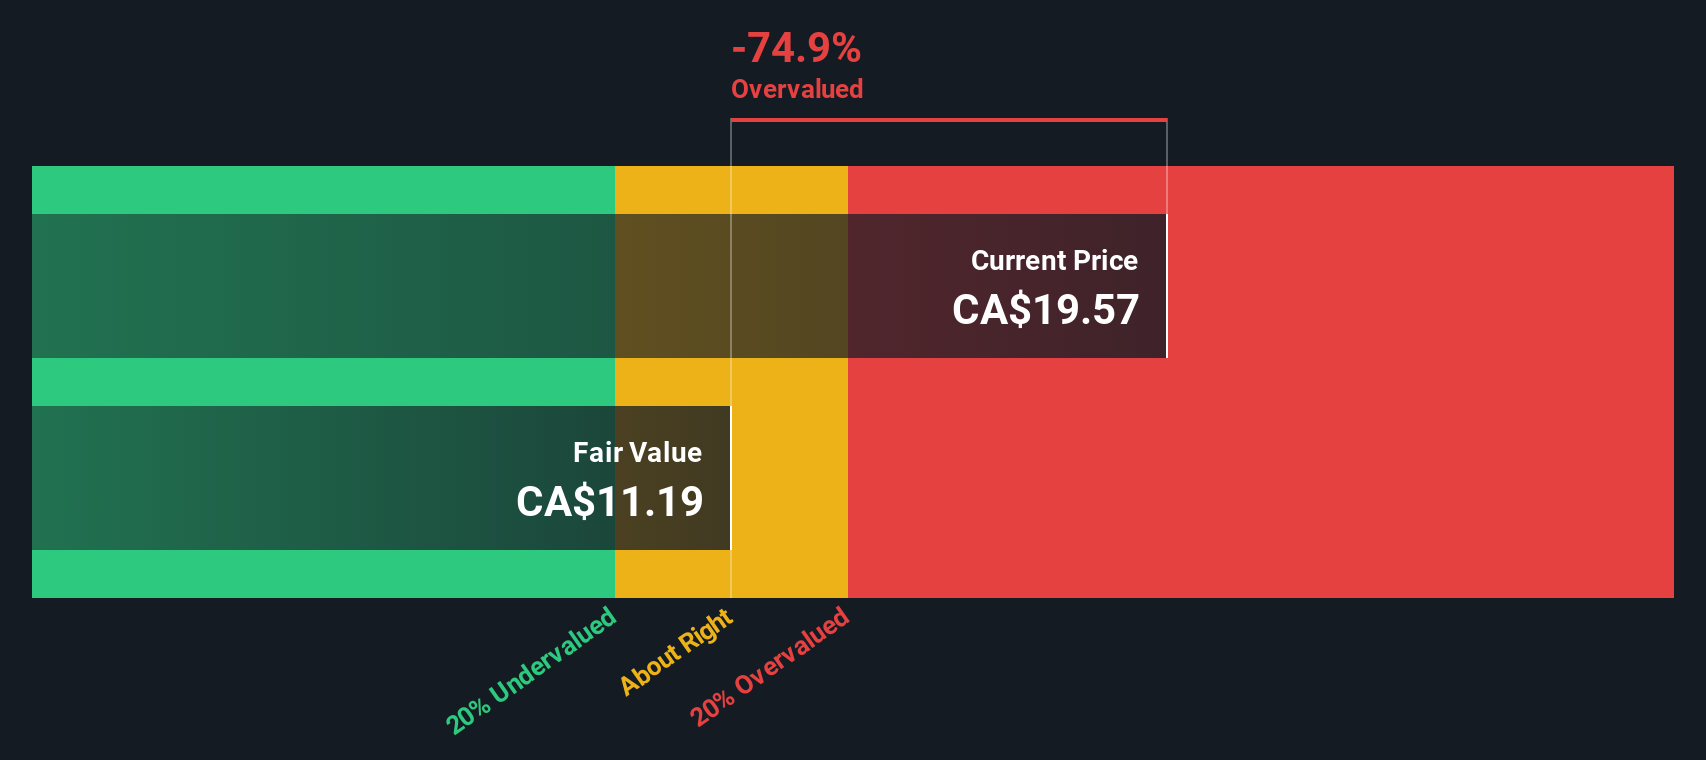
Overview: Sienna Senior Living operates as a provider of senior living and long-term care services, with a focus on retirement and long-term care facilities, and has a market capitalization of approximately CA$1.53 billion.
Operations: The primary revenue streams include Long-Term Care (LTC) and Retirement segments, contributing significantly to the total revenue. The gross profit margin has shown variability, with recent figures around 20.90%. Operating expenses and cost of goods sold are substantial components of the company's financials, impacting overall profitability.
PE: 43.7x
Sienna Senior Living, a smaller company in the healthcare sector, is expanding its footprint with the acquisition of Stonemont On the Park for CAD 170.7 million, adding to CAD 1.2 billion in assets since 2025. Despite relying on external borrowing for funding, they maintain steady dividends at CAD 0.936 annually per share and report rising revenues—up to CAD 277 million in Q2 from last year's CAD 244 million—demonstrating resilience and growth potential amidst financial challenges.
Turning Ideas Into Actions
- Investigate our full lineup of 121 Undervalued Global Small Caps With Insider Buying right here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com