


DiamondRock Hospitality (DRH) recently set a new 52 week high after four straight quarters of earnings beats, putting the hotel focused REIT's capital recycling and ROI projects firmly in the spotlight for investors.
That new high caps a powerful run for DiamondRock Hospitality, with a year to date share price return of 52.25% and a 1 year total shareholder return of 84.85%. This signals strong momentum even after a 4.56% 7 day share price gain and a modest 0.36% pullback in the last session.
Scan for other REITs showing similar price strength and earnings surprise patterns as DiamondRock Hospitality using our curated 29 high quality undervalued stocks.
After a move like this from DiamondRock Hospitality, the real tension is simple: Is the recent surge already pricing in the good news, or does the current valuation still leave room for patient buyers to wait on a better entry?
Most Popular Narrative: 1% Undervalued
On the most followed view, DiamondRock Hospitality screens as slightly undervalued, with a fair value estimate of $14.04 against a last close of $13.89, which puts the recent price strength in context rather than contradicting it.
The multiyear plan to invest 7% to 9% of annual revenue, or about $80 million to $100 million per year, into lower intensity but ROI focused projects such as L’Auberge de Sedona and The Dagny aims to keep capital needs below peer levels while still targeting double digit EBITDA yields. This can support free cash flow and FFO per share.
See why 2 investors see DiamondRock Hospitality as 1% undervalued.
Result: Fair Value of $14.04 (UNDERVALUED)
Still, higher labor costs in markets like New York and the risk that asset sales outpace attractive reinvestment options could put pressure on DiamondRock Hospitality’s margins and cash generation story.
Find out about the key risks to this DiamondRock Hospitality narrative.
Another View: What The P/E Says About DiamondRock Hospitality
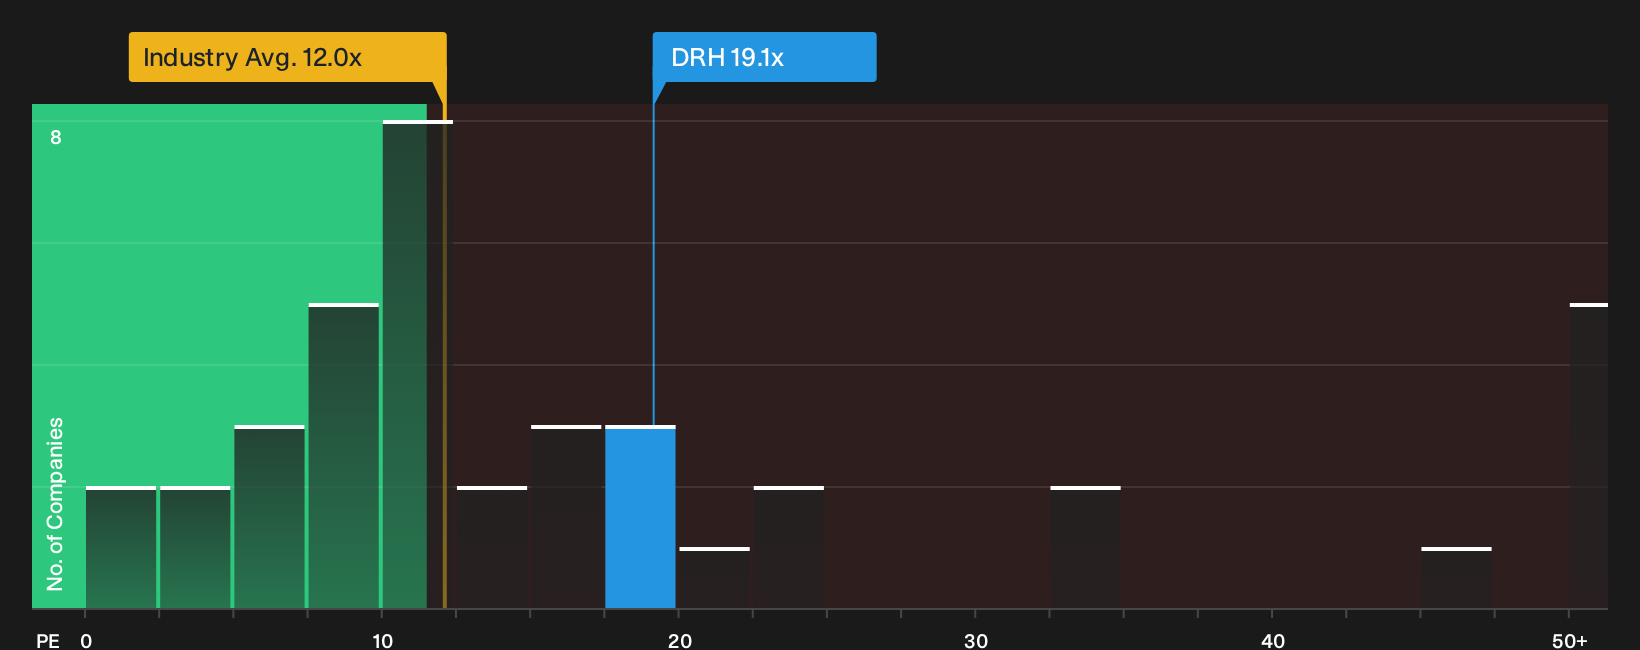
On a simple earnings multiple, DiamondRock Hospitality looks less generous. The stock trades at a P/E of 19.1x compared with 12.1x for the global Hotel and Resort REITs industry, even though the fair ratio for DRH is estimated at 28.9x. That premium to peers, and gap to the fair ratio, leaves you weighing valuation risk against potential upside if sentiment shifts toward that higher multiple.
For a closer look at how this earnings based view stacks up against a fuller valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of the DiamondRock Hospitality story so far. Act while the data is fresh, and weigh the 2 key rewards and 3 important warning signs against your own view.
Looking for more investment ideas beyond DiamondRock Hospitality?
If DiamondRock Hospitality has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Spot potential value plays early by scanning the 29 high quality undervalued stocks that pair quality fundamentals with prices that still look reasonable.
- Stabilize your income stream by reviewing the 6 dividend fortresses that focus on higher yielding payouts with supporting fundamentals.
- Strengthen your downside protection by checking the 30 resilient stocks with low risk scores that screen for resilient balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com