


Oil has pushed above $113 a barrel as investors rethink how much they are paying for big tech and AI giants. That combination of higher energy costs and shaken confidence in large platforms has turned attention to smaller Australian AI stocks that are not priced for perfection and have room to prove themselves. This article highlights three AI focused small caps from our screener that merit a closer look.
The three stocks covered below are just a small sample, and the full AI small caps screen has surfaced 7 more companies with equally compelling narratives that are not included in this article. To identify and analyze the highest conviction early stage AI plays, head straight into the AI Small Caps screener.
Pureprofile (ASX:PPL)
Overview: Pureprofile is a data and insights group whose Datarubico AI platform uses machine learning and automation to deliver self-serve audience intelligence, alongside broader market research and brand measurement services for marketers and agencies.
Operations: Pureprofile generates A$65 million from Data & Insights, with A$37 million from Australasia, A$14 million from the United States, and A$14 million from Europe.
Market Cap: A$32.5 million
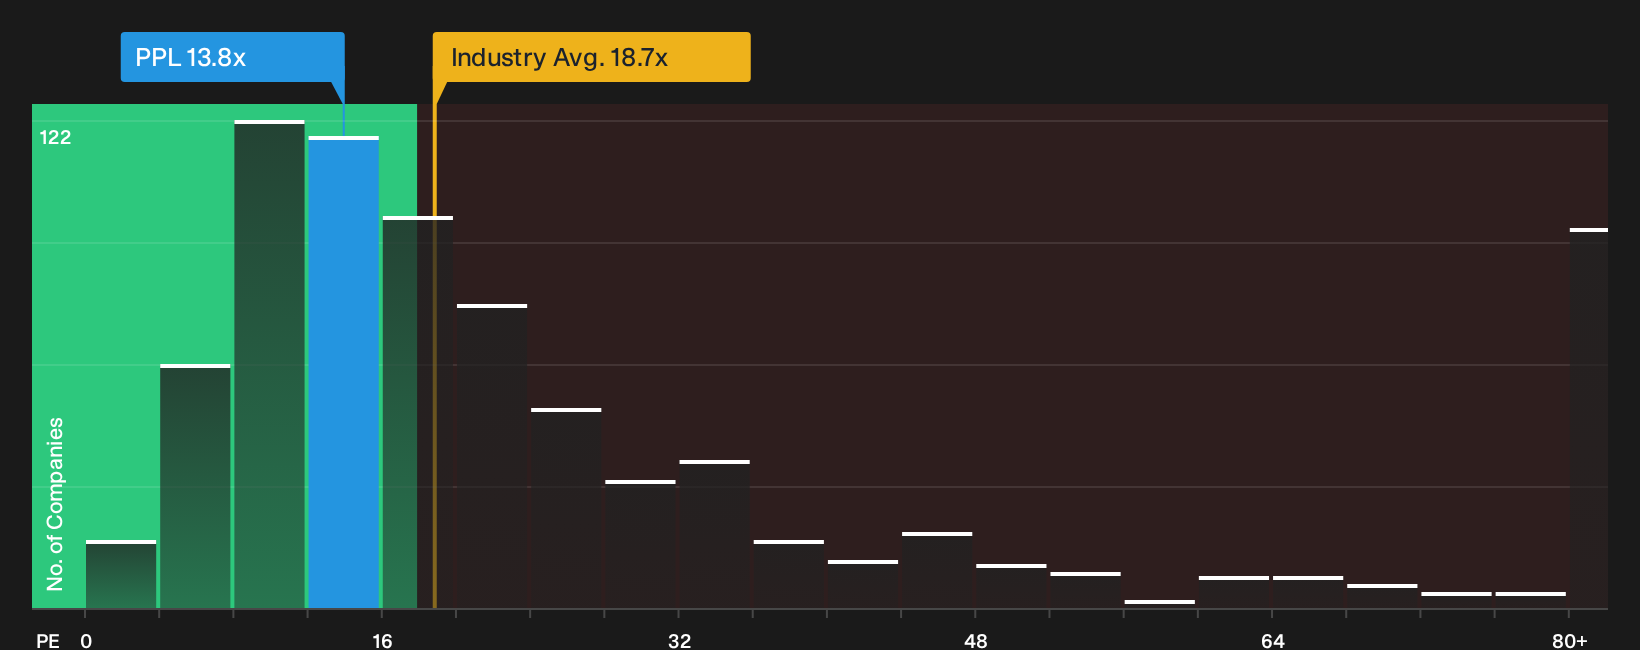
Puredataprofile provides direct exposure to AI in market research, with the Datarubico platform supported by A$65.03 million of FY2026 sales and net income of A$2.26 million at a P/E of about 13.8x. The appeal is that this AI engine operates within a broader insights business, although margins and growth will depend on how one currently unseen pressure develops.
That pressure point is exactly what the 4 key rewards and 1 important warning sign could be masking for Pureprofile, especially if the AI engine scales faster than expected.
Dicker Data (ASX:DDR)
Overview: Dicker Data is a wholesale distributor that supplies AI capable hardware, Copilot+ PCs, software, and cloud solutions to Australian and New Zealand enterprises.
Operations: The business generates about A$2.73b from wholesale computer peripherals, with roughly A$2.36b from Australia and A$373 million from New Zealand.
Market Cap: A$2.69b
Dicker Data matters for this AI Small Caps screen because its distribution engine already pushes AI ready servers, GPUs, and Copilot+ PCs into enterprise projects where machine learning and data intelligence workloads are actually being switched on.
"Expansion into AI infrastructure and solutions, including the delivery of Australia's first AI factory in partnership with Dell and further AI pipeline opportunities, aligns the company with accelerating enterprise digital transformation and creates substantial upside for advanced solutions revenue, especially as AI adoption grows across Australia and New Zealand.
The real test comes from how that growing mix of advanced AI infrastructure affects Dicker Data’s margins if one key assumption on deal quality shifts.
If that assumption proves too cautious or too bold, the full narrative for Dicker Data explains how Dicker Data’s AI pipeline could either accelerate or stall from this point.

Data#3 (ASX:DTL)
Overview: Data#3 is an Australian IT solutions provider that rolls Microsoft 365 Copilot, AI analytics, and security into customer projects.
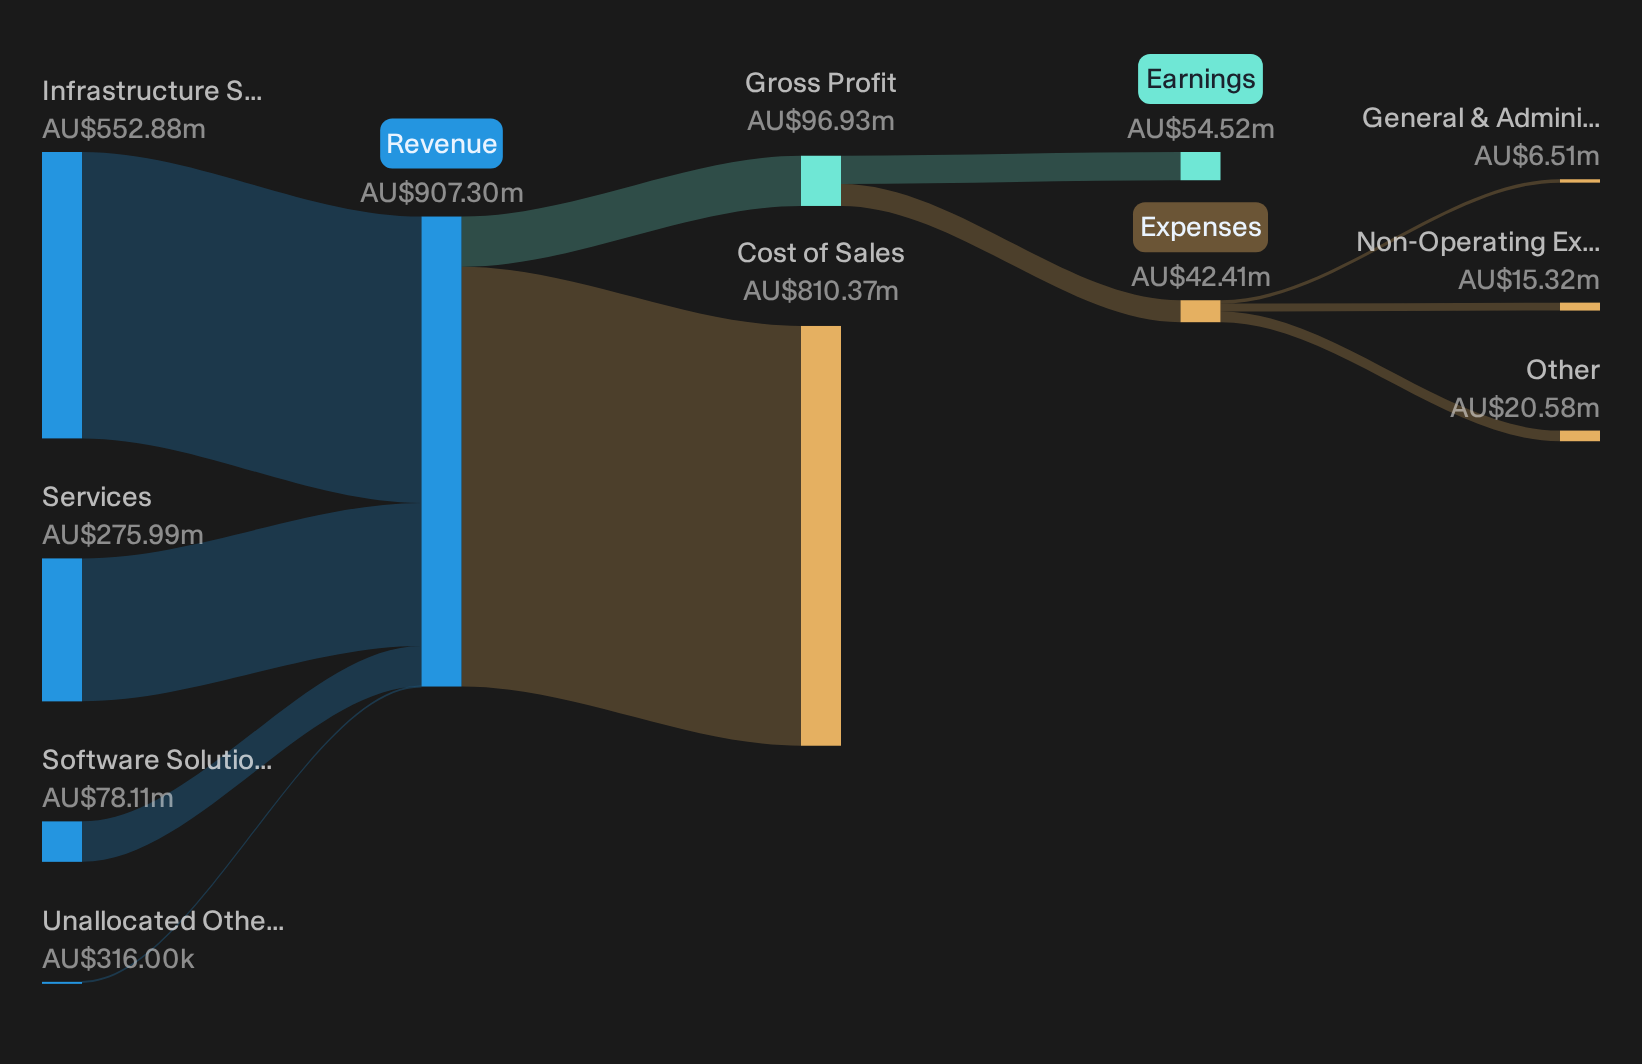
Operations: Data#3 generates about A$553 million from Infrastructure Solutions, A$276 million from Services, and A$78 million from Software Solutions, almost entirely in Australia.
Market Cap: A$2.05b
Data#3 plugs directly into the AI Small Caps theme because its Copilot rollouts and AI analytics projects push applied machine learning into hospitals, classrooms, and government departments rather than just selling underlying tools.
"The accelerating shift by customers to multiyear subscription and as-a-service models (evidenced by recurring revenue increasing to 69% and rapid expansion in Device-as-a-Service) positions Data#3 for higher, more stable, and predictable revenue and margin growth over time as the mix continues to improve.
What really matters now is how quickly one evolving mix inside those AI focused contracts shapes margins and repeat demand.
As that contract mix shifts, the full narrative for Data#3 shows where Data#3’s AI momentum could accelerate, stall, or quietly rerate expectations over the next phase.
Curious About What You Might Be Missing?
Fresh opportunities can move from quiet to breakout quickly. Momentum shifts, stories start flying, and slow reactions get caught on the wrong side. Check the data while it matters and get in early.
- Scan for sturdy compounders with room to run by working through a curated list of solid balance sheet and fundamentals (12 results) that keeps financial resilience front and center for your watchlist.
- Spot potential high-yield anchors before yields start dropping by sorting through the hand picked 6 dividend fortresses that screens for income with staying power.
- Track early crypto themed moves while they remain under the radar for now by filtering opportunities through the focused 18 cryptocurrency and blockchain stocks tailored for this space.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com