


Universal Insurance Holdings (UVE) just posted third quarter and year to date results, giving investors fresh numbers on revenue, earnings and profitability as of September 30, 2026.
Universal Insurance Holdings has seen momentum build through 2026, with a 12.48% 1 month share price return and a 52.63% year to date share price return. Total shareholder return over 5 years sits above 300%, suggesting investors are reacting strongly to recent earnings and ongoing execution on its diversification efforts.
Capitalize on Universal Insurance Holdings' momentum by scanning a curated 20 high quality undiscovered gems that share similar quality traits and are still flying under most investors' radar.After a near 53% year-to-date surge and strong recent earnings, is Universal Insurance Holdings already priced for success, or do the current numbers still leave meaningful upside on the table as valuation comes into focus next?
Most Popular Narrative: 10% Overvalued
Universal Insurance Holdings closed at $48.40 while the most followed valuation narrative pegs fair value at $44.00, so the shares sit modestly above that estimate and put more weight on execution than the model does. The framework behind that view leans heavily on how UVE manages reinsurance, technology spend and buybacks through the cycle.
Recent strong premium growth outside Florida (+25.4% year-over-year) alongside higher overall policies in force demonstrate the company's success diversifying geographically, which reduces concentration risk and may help stabilize and support revenue and earnings.
The company is capturing higher premiums due to increases in property values and inflation adjustments, which aligns with broader rising reconstruction and replacement costs. This may help drive top-line growth and support total revenue.
See why 6 investors see Universal Insurance Holdings as 10% overvalued.
Result: Fair Value of $44 (OVERVALUED)
Still, that narrative can crack if higher ceded premium costs and expense ratios keep pressuring profitability, or if competition in Florida further erodes Universal Insurance Holdings' core premium base.
Find out about the key risks to this Universal Insurance Holdings narrative.
Another Look At Universal Insurance Holdings’ Valuation
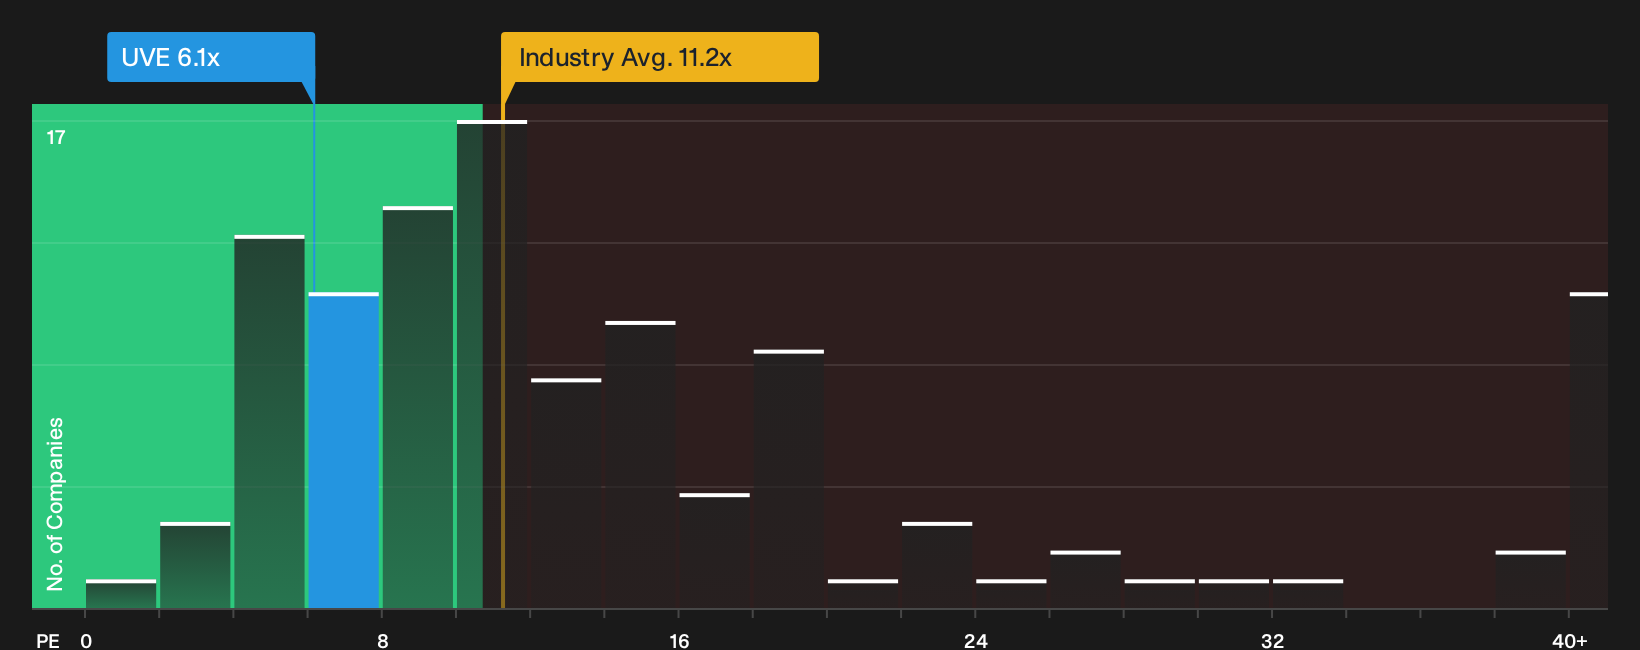
The narrative crowd sees Universal Insurance Holdings as roughly 10% overvalued at $48.40 versus a $44.00 fair value. The market’s own P/E story points the other way. UVE trades on 6.1x earnings, compared with 21x for peers and a fair ratio of 6.9x based on regression analysis.
That gap suggests investors are either discounting the analyst growth fears too heavily or attaching extra risk to UVE that peers do not carry. Which side of that spread do you think is mispriced?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Universal Insurance Holdings so far, with both concern and optimism in play. Consider moving quickly and weighing the data yourself using 4 key rewards and 2 important warning signs.
Looking for more Universal Insurance Holdings style ideas?
Do not stop your research with Universal Insurance Holdings. The next opportunity rarely waits for investors who only watch from the sidelines.
- Target higher potential upside by scanning a curated list of 29 high quality undervalued stocks that combine quality fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (26 results) so you focus on businesses with stronger finances and less fragile capital structures.
- Strengthen your income playbook by hunting through a set of 6 dividend fortresses that aim to pair meaningful yields with underlying financial support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com