


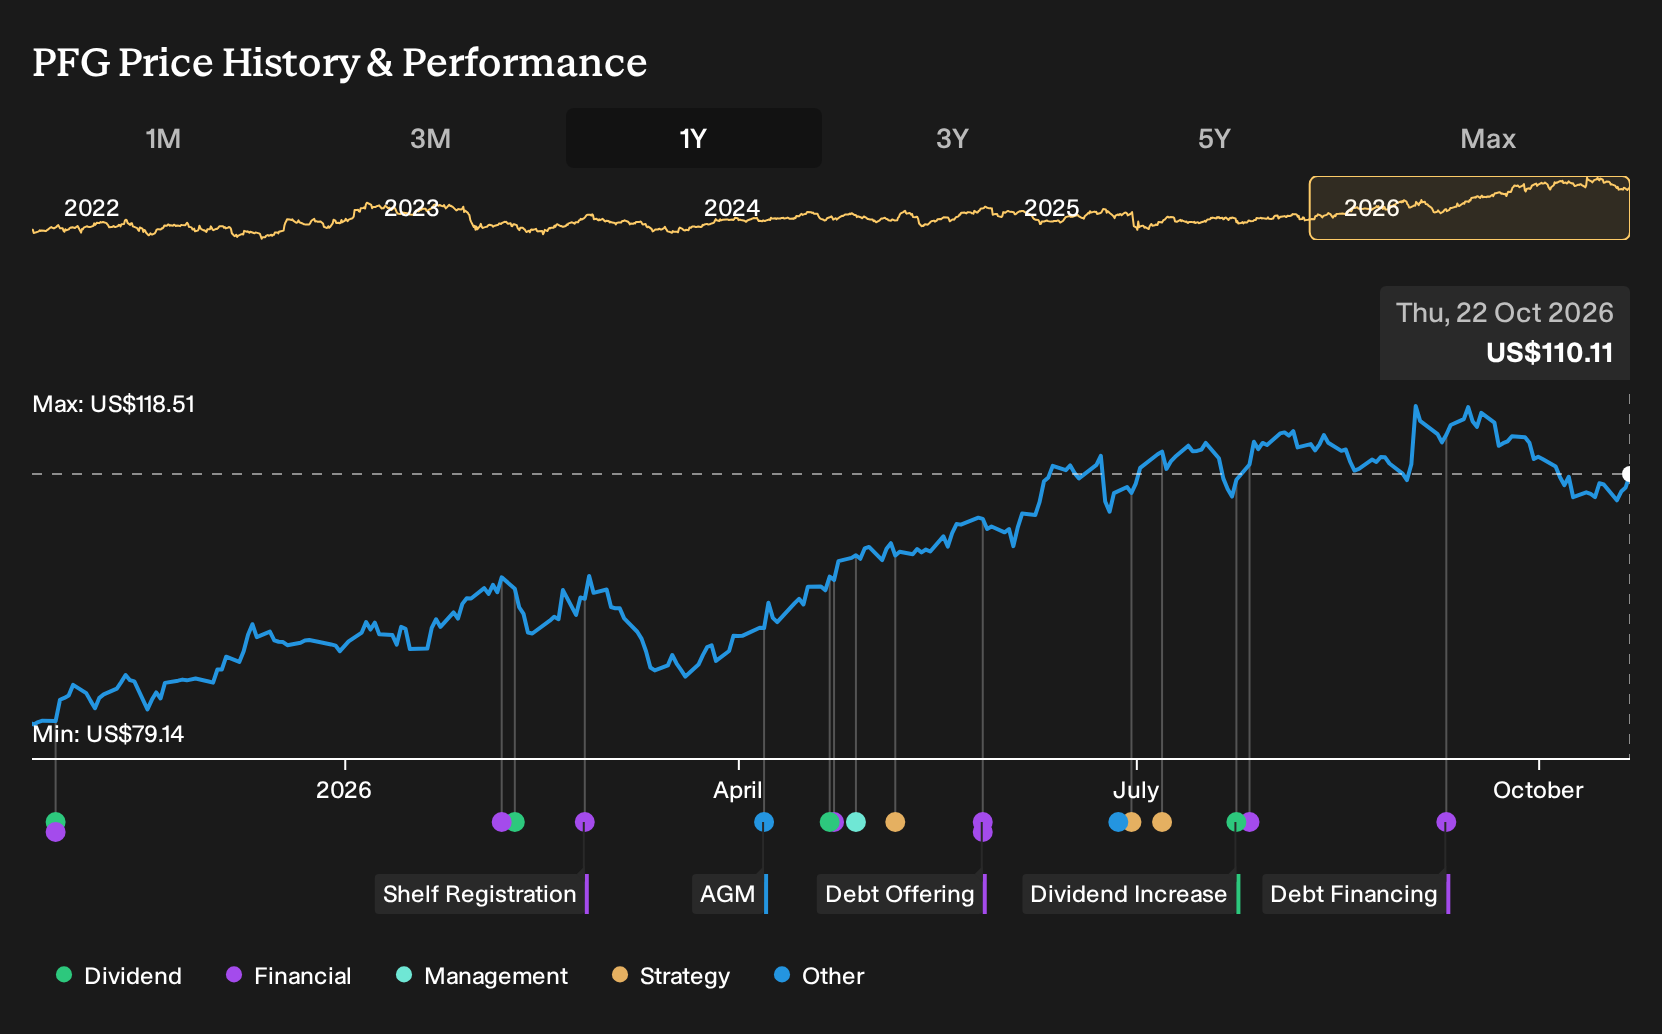
If you had bought Principal Financial Group on 22 October 2025 and simply left it alone, the result was striking. Investors who held Principal Financial Group over the past year are up 43.4%, including dividends. That outcome now sits alongside a year of strong earnings headlines, dividend hikes and the Beam Benefits deal. The real puzzle is what early buyers were weighing back at the start, given the split between bullish growth hopes and warnings about volatile fee income.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Principal Financial Group harder to judge, start where the gap is still open and scan 29 high quality undervalued stocks.
The Two Principal Financial Group Stories Investors Had To Weigh
The shares cost US$79.14 at the start, and Principal Financial Group sat between two very different stories about how its future might unfold.
The bullish narrative pinned fair value at US$86.02 and leaned on retirement and global asset management expansion, including a push into Mexico and Southeast Asia, as well as a shift toward higher fee mandates.
The bearish case put fair value at US$72 and focused on market volatility pressuring fee revenue in retirement and asset management, while expense control was expected to support profit margins.
What The Principal Financial Group Results Put To The Test
The Beam Benefits acquisition and Q2 2026 report gave Principal Financial Group fresh support for the growth story around small and mid-sized employers, retirement income products and fee-based assets, yet the numbers were less clean. Revenue moved from US$3,671.3m in Q2 2025 to US$3,905.8m in Q2 2026 while net income slipped and net margin fell, so the evidence cut both ways.
The key lesson is simple. When a growth plan leans on fee and benefit expansion, track segment revenue, net margin and the size of new platforms, then test whether each deal or product launch shows up in those figures over time.
What Principal Financial Group’s Price Already Assumes
Principal Financial Group now trades at US$110 after a 43.4% total return over the past year. The selected Narrative’s Fair Value sits below the current price, which frames today’s debate less around past execution and more around what the next stretch of earnings and flows needs to deliver.
The Narrative leans on strong cost control, solid underwriting and capital returns, yet questions how resilient fee income and margins are if active equity outflows or mix shifts persist. A buyer at US$110 effectively has to assess whether margin strength and private markets growth can keep offsetting fee pressure and softer net flows.
"Key Takeaways: Bearish analysts expect Principal Financial Group’s earnings growth to slow as continued market volatility and ongoing net outflows in certain active equity strategies pressure fee revenue and profitability. The main thing that has to go right is that Principal Financial Group continues to translate its cost discipline and underwriting results in Specialty Benefits and Benefits and Protection into sustained margin strength, even while funding technology and AI investments."
The price and this Narrative do not agree. → Uncover what this Narrative says Principal Financial Group is actually worth
Looking Beyond Principal’s Playbook
Principal shows how retirement, benefits and asset management can work together. You can still ask what else those same customer needs might support.
Employers buying group benefits from Principal also need property, liability and health cover. Another large insurer concentrates on those protection lines and related services.
This other player is pushing AI into underwriting, marketing and claims handling. Faster decisions and cheaper processing directly target loss and expense ratios.
It is also leaning into health and long term savings products, plus third party investing. If those areas keep drawing attention, your watchlist might stretch beyond Principal.
One Narrative has already put a figure on it. → Uncover the company trading 26% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com