


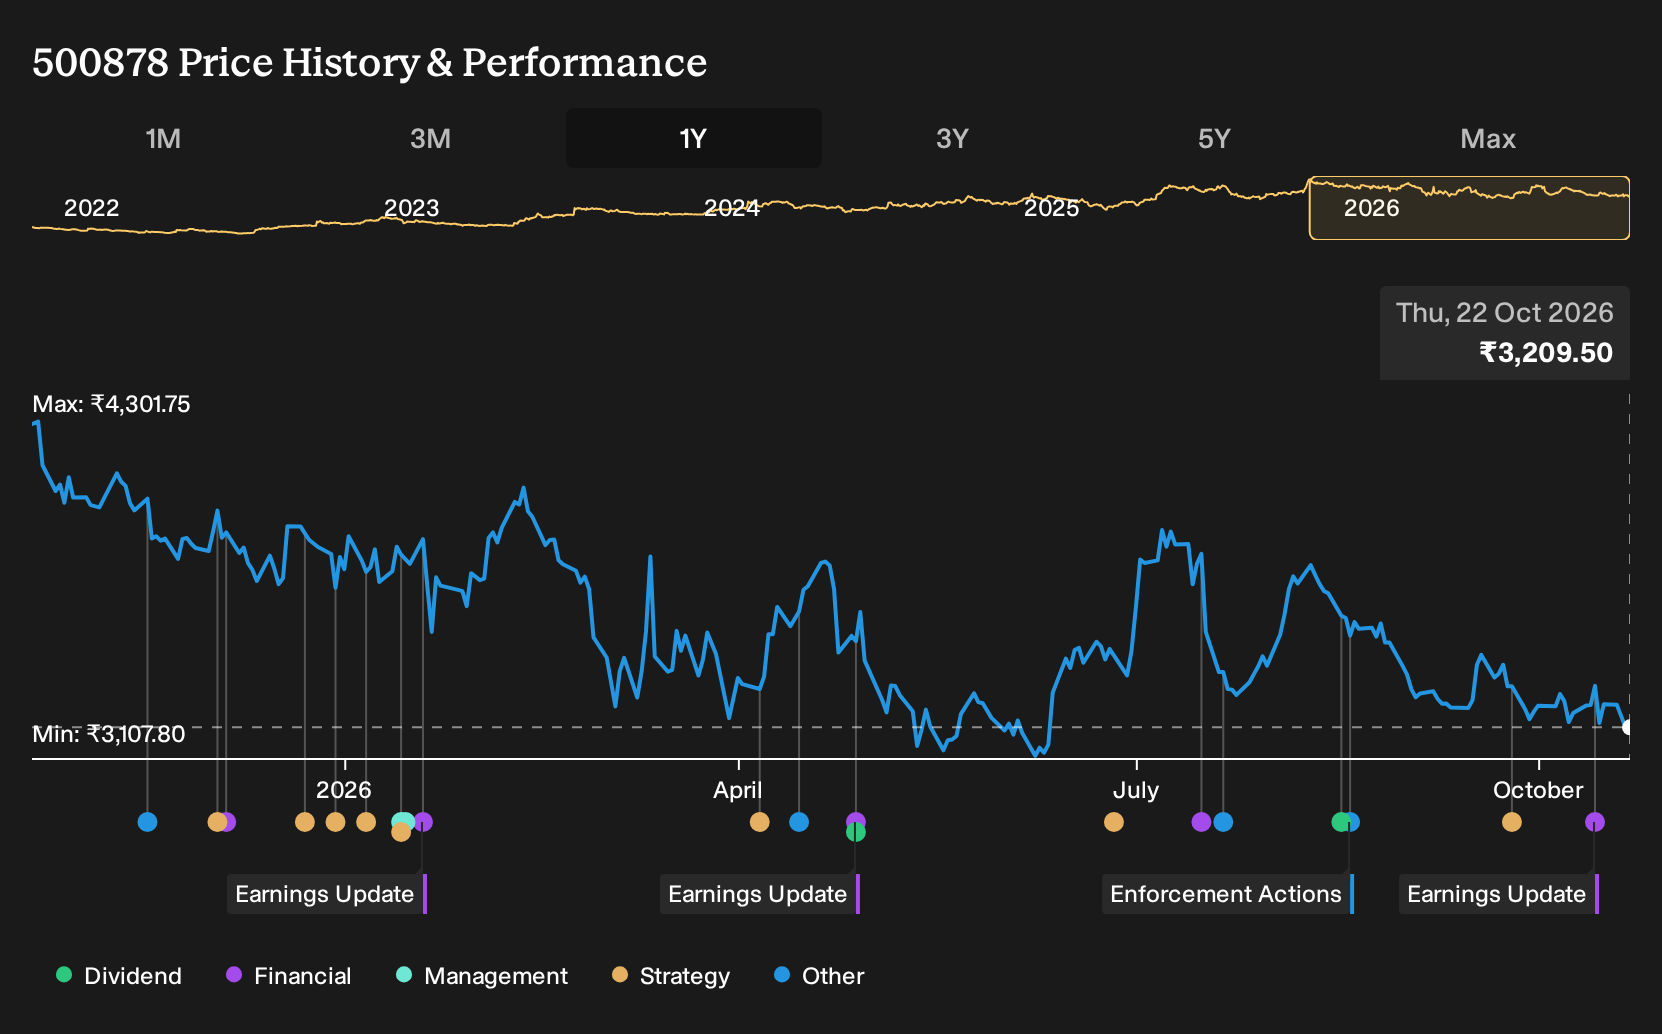
If you only glanced at CEAT’s growing revenue and expanding international story, a weak outcome on your brokerage screen might feel baffling. For CEAT shareholders, the loss over the past year was 24.6%, including dividends. At the same time, the latest quarterly report showed higher sales alongside a sharply lower net margin. If that mix of top-line strength and profit compression was already on the horizon in late 2025, what did investors miss about this business?
CEAT has already moved. See which of 190 high quality undervalued stocks still trade below our estimates.
What CEAT Investors Were Really Debating Back Then
The shares cost ₹4,288 at the start of the period. CEAT holders effectively had to choose between an ambitious international expansion story and a more cautious read on what the business could deliver.
The bullish narrative pointed to a Fair Value of ₹4,600, a notional price built on assumptions of strong export growth after the Camso integration and faster margin expansion from premium EV and high-tech tires.
The more restrained view anchored on a Fair Value of ₹3,963. This was based on expected 11% revenue growth and 5.9% profit margins, but with clear concerns about raw material swings and export tariff risks.
What The Results Put To The Test For CEAT
The clearest datapoint came from CEAT’s later quarterly figures. Revenue moved from ₹37,726.5m in Q2 2026 to ₹47,620m in Q2 2027, which lined up more neatly with the optimistic case that focused on export and premium segment momentum. Net income told a different story and directly pushed back on the margin upgrade argument.
Profit slipped from ₹1,859.5m to ₹1,120m and net margin went from 4.9% to 2.4%, which supported the cautious thesis on profitability. The takeaway for any other stock is simple: when a bullish story rests on margin expansion, track net margin and absolute earnings in each result and compare them with the original target rather than the share price reaction.
What Today’s CEAT Price Asks You To Believe
CEAT now trades at ₹3,210, well below where this story started and below where the selected Narrative’s Fair Value sits, according to that analysis rather than hard fact.
The argument leans on EV exposure, a richer premium mix and international expansion. For the Narrative’s higher figure to hold, CEAT would need to execute its capex and CAMSO buildout and lift premium and EV oriented volumes toward profitable utilization.
"The main requirement for this thesis is CEAT successfully executing its heavy capex and international buildout, including scaling premium and EV oriented volumes while lifting underutilised CAMSO and OHT capacity toward profitable levels despite ongoing raw material volatility and higher debt."
One Narrative disagrees with today's price. → See where this Narrative says CEAT should trade
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 44% below our estimate - targets oncology planners needing hardware-neutral treatment design and data systems.
- Company 2 - 30% below our estimate - expands enterprise B2B and video tools built around proprietary artificial intelligence capabilities.
- Company 3 - 37% below our estimate - handles intricate cross-disciplinary mandates combining AI, compliance, safety and legal-risk analysis.
That is three of the list. See all 204 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com