


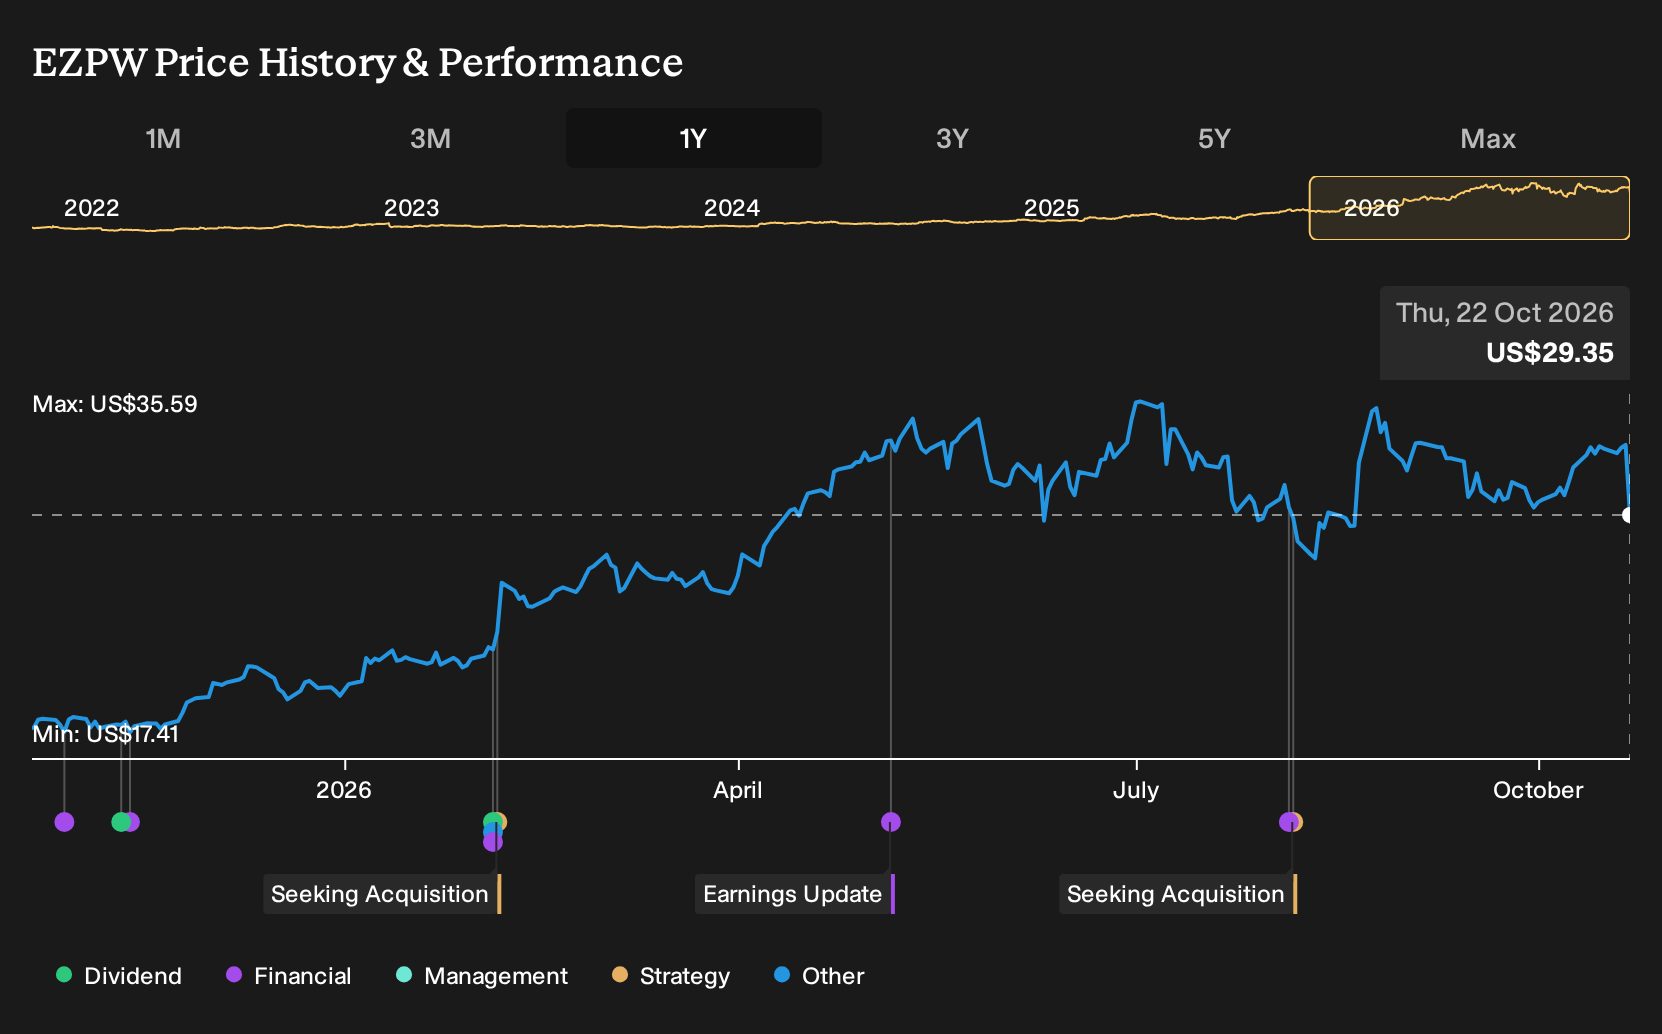
- EZCORP, a major pawn lender in the United States and Mexico, saw investor attention shift after sector peer FirstCash reported record third quarter pawn revenue growth and a higher dividend while gold prices moved lower, raising questions about collateral values and scrap gold income for the whole industry.
- The key tension for EZCORP is that investor focus swung back to gold price sensitivity at the same time analysts are framing its long term story around core pawn profitability and less reliance on scrap margins.
- The next step is to analyze how this sector wide reaction to weaker gold prices could reshape EZCORP's investment narrative for long term holders.
EZCORP Investment Narrative Recap
To own EZCORP, you need to believe its pawn operations in the U.S. and Latin America can keep doing the heavy lifting as scrap gold margins normalize and gold price sensitivity keeps resurfacing. The near term swing factor is how well store level pawn profitability holds up if collateral values soften while consumer demand for quick credit stays firm.
The biggest risk right now is that expansion costs and integration work from past deals meet weaker scrap economics at the same time. If newer locations in Mexico and Guatemala take longer to ramp, higher labor and overhead can pressure margins, and the recent gold driven sector reset makes that trade off more visible.
The most relevant reference point is the current earnings expectations for the September 2026 quarter. Consensus looks for EPS of US$0.40 and revenue of US$422.4 million, both higher than the prior year period. That sets a clear bar for how effectively EZCORP is converting loan demand and merchandise sales into profit in the current pawn cycle.
For you as a shareholder, that upcoming report is the practical catalyst. It gives fresh evidence on whether store growth in Latin America, tighter scrap margins and higher operating costs are combining into a healthy earnings profile or starting to squeeze profitability, and it will color how investors treat any future swings in gold prices around the pawn story.
EZCORP's current earnings of US$158.3 million are projected by analysts to reach US$216.4 million by 2029, implying revenue of US$2.0b in that year. This assumes 8.7% yearly revenue growth and an earnings increase of about US$58 million from today.
Uncover how EZCORP's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Another way to look at EZCORP is through the bearish focus on scrap margins. The most cautious analysts already saw limited upside even while penciling in about US$2.1b of revenue and US$220.9 million of earnings by 2029. After the gold driven sector move, that cautious view could either harden or soften, and you are seeing how far expert opinions can stretch.
Explore 4 other EZCORP fair value estimates, including one that suggests as much as 22% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EZCORP research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for EZCORP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EZCORP's overall financial health at a glance.
Looking for more investment ideas beyond EZCORP?
Once the EZCORP story is clear in your mind, the next move is to widen your watchlist and compare it with other potential opportunities using the Simply Wall St Screener.
- If you want potential value with quality behind it, scan through 29 high quality undervalued stocks and see which companies match your preferred mix of fundamentals and price.
- For investors who care most about resilience, filter for stability first by checking out the 30 resilient stocks with low risk scores and see which businesses keep risk scores in check.
- When balance sheet strength is your non negotiable starting point, shortlist candidates through the list of solid balance sheet and fundamentals (26 results) and compare their financial foundations side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com