


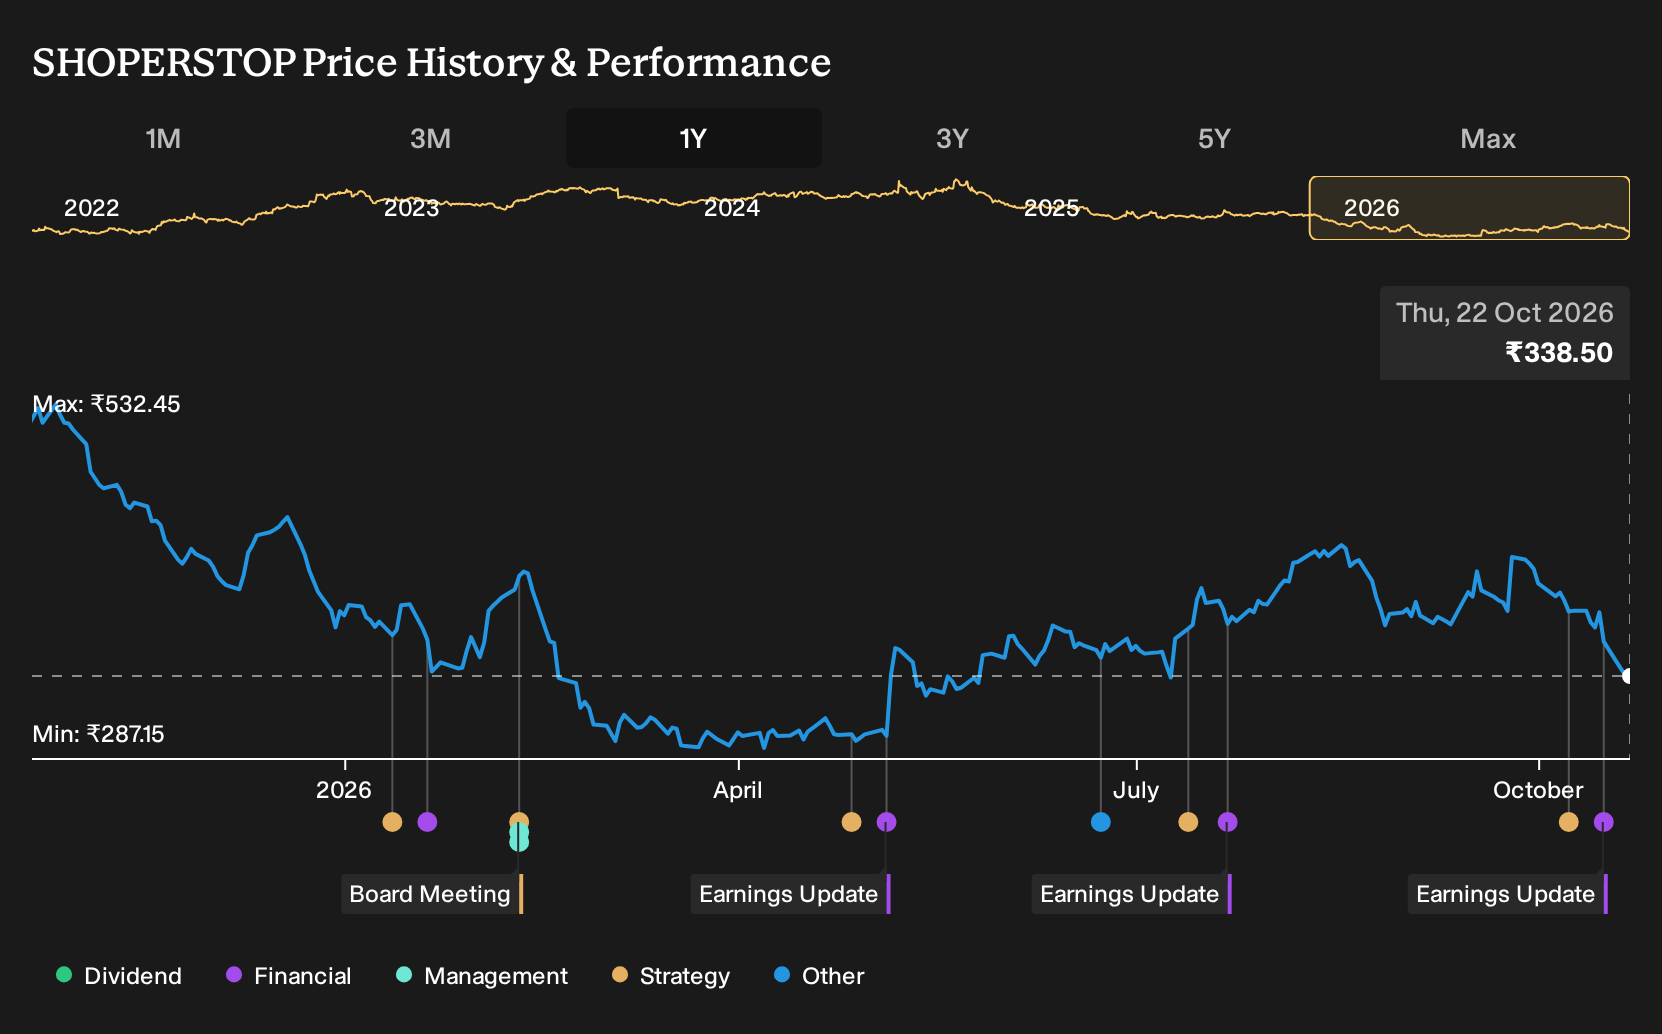
If you backed Shoppers Stop on the promise of premium formats, digital upgrades and loyalty-driven beauty sales, the payoff has been uncomfortable. Investors who held Shoppers Stop over the past year are down 36.1%, including dividends. Recent results show revenue and net profit both higher than a year ago, which only sharpens the question. If the bullish case assumed rising margins, stronger omni-channel execution and better operating leverage, which of those specific expectations did reality fail to fully support?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made Shoppers Stop harder to judge, start where the gap is still open and scan 190 high quality undervalued stocks.
The Two Shoppers Stop Stories Investors Had To Weigh
At the start of the period, Shoppers Stop shares cost ₹519, and investors had to decide which story about the future felt more convincing.
On the bullish side, the Narrative put Fair Value at ₹807. It rested on premiumization, targeted campaigns and private brands supporting higher margins, along with an expectation that omni-channel expansion and new city entries would lift digital sales and recurring earnings quality.
The bearish view argued for Fair Value of ₹327. That camp focused on accelerating online competition straining in-store revenue, and on large Intune rollouts keeping depreciation, interest costs and consolidated margins under pressure.
What The Shoppers Stop Results Actually Tested
The clearest fact is that Shoppers Stop shifted from a loss of ₹201.1m in Q2 2026 to a profit of ₹31.1m in Q2 2027, which lent some support to the optimistic profitability story. Net margin moved from a loss of 1.6% to a slim 0.2% profit, so the stronger margin assumption was only partly backed and still looks fragile.
The big swing factor was profit quality. For any other retailer you compare, track whether improving margin forecasts are appearing in reported net income and net margin, not just in revenue lines or store rollout plans.
What You Would Be Paying For In Shoppers Stop Today
Shoppers Stop now trades at ₹338, with the selected Narrative’s Fair Value sitting above that quote rather than below it. The current thesis leans on premium and non apparel categories, beauty distribution and omni channel execution, as well as tighter working capital discipline.
For the past year’s 36.1% fall to look like opportunity instead of warning, a buyer at today’s price would need confidence that renovation led productivity, premium ticket additions and beauty distribution can collectively support a stronger long term earnings profile.
"The thesis on Shoppers Stop has been reviewed and reaffirmed, with the focus shifting from premiumization and omni-channel build out toward store renovation productivity, higher ticket categories, beauty distribution and working capital discipline as the key drivers of the story."
The price and this Narrative do not agree. → Uncover what this Narrative says Shoppers Stop is actually worth
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 43% below our estimate - targets everyday athletes as sports fashion expands into higher margin performance apparel.
- Company 2 - 35% below our estimate - converts subsea project prospects into shorter cycle contracts and services agreements.
- Company 3 - 50% below our estimate - brings higher grade ore into the mill to raise output and efficiency.
Those are three of them. See the full list of 204 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com