


Britain is heading into another winter with some of Europe’s highest energy costs, and households are feeling it every month when the bill lands. That keeps reliable low carbon power sources firmly in the spotlight for long term investors. Nuclear focused UK stocks linked to uranium, fuel services and reactors sit right in this conversation. This article highlights three options from our nuclear energy screener that may be worth a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium producers, fuel enrichment providers and nuclear reactor operators. However, if you want the names that matter most, these 16 nuclear renaissance stocks are the strongest companies we've found.
Rolls-Royce Holdings (LSE:RR.)
Rolls-Royce Holdings is best known for large civil jet engines, yet its Defence arm, which designs and supplies nuclear reactors and propulsion systems for submarines, is what ties it directly into the nuclear energy theme that this screener focuses on.
Rolls-Royce generates £11.8b from Civil Aerospace, £5.5b from Power Systems and £5.0b from Defence, and the group’s nuclear submarine propulsion work sits inside that Defence activity. The business is a heavyweight in UK industry with a market value around £104.5b.
For nuclear focused investors, Rolls-Royce Holdings offers a rare mix of civil aviation, defence and nuclear propulsion expertise, with the real swing factor coming from how its power and Defence activities play out over the next phase of the cycle.
"A significant portion of current narrative and valuation appears premised on Power Systems segment growth, particularly the data center power generation boom, continuing at near-peak rates (20%+ per year) as cloud and AI infrastructure expand."
What happens if a single assumption about future power demand quietly shifts will matter a great deal for long term earnings quality.
That is exactly what sits at the heart of the full narrative for Rolls-Royce Holdings, which examines how power demand assumptions, Defence exposure and capital needs could be decoupling beneath the surface.

National Atomic Company Kazatomprom JSC (LSE:KAP)
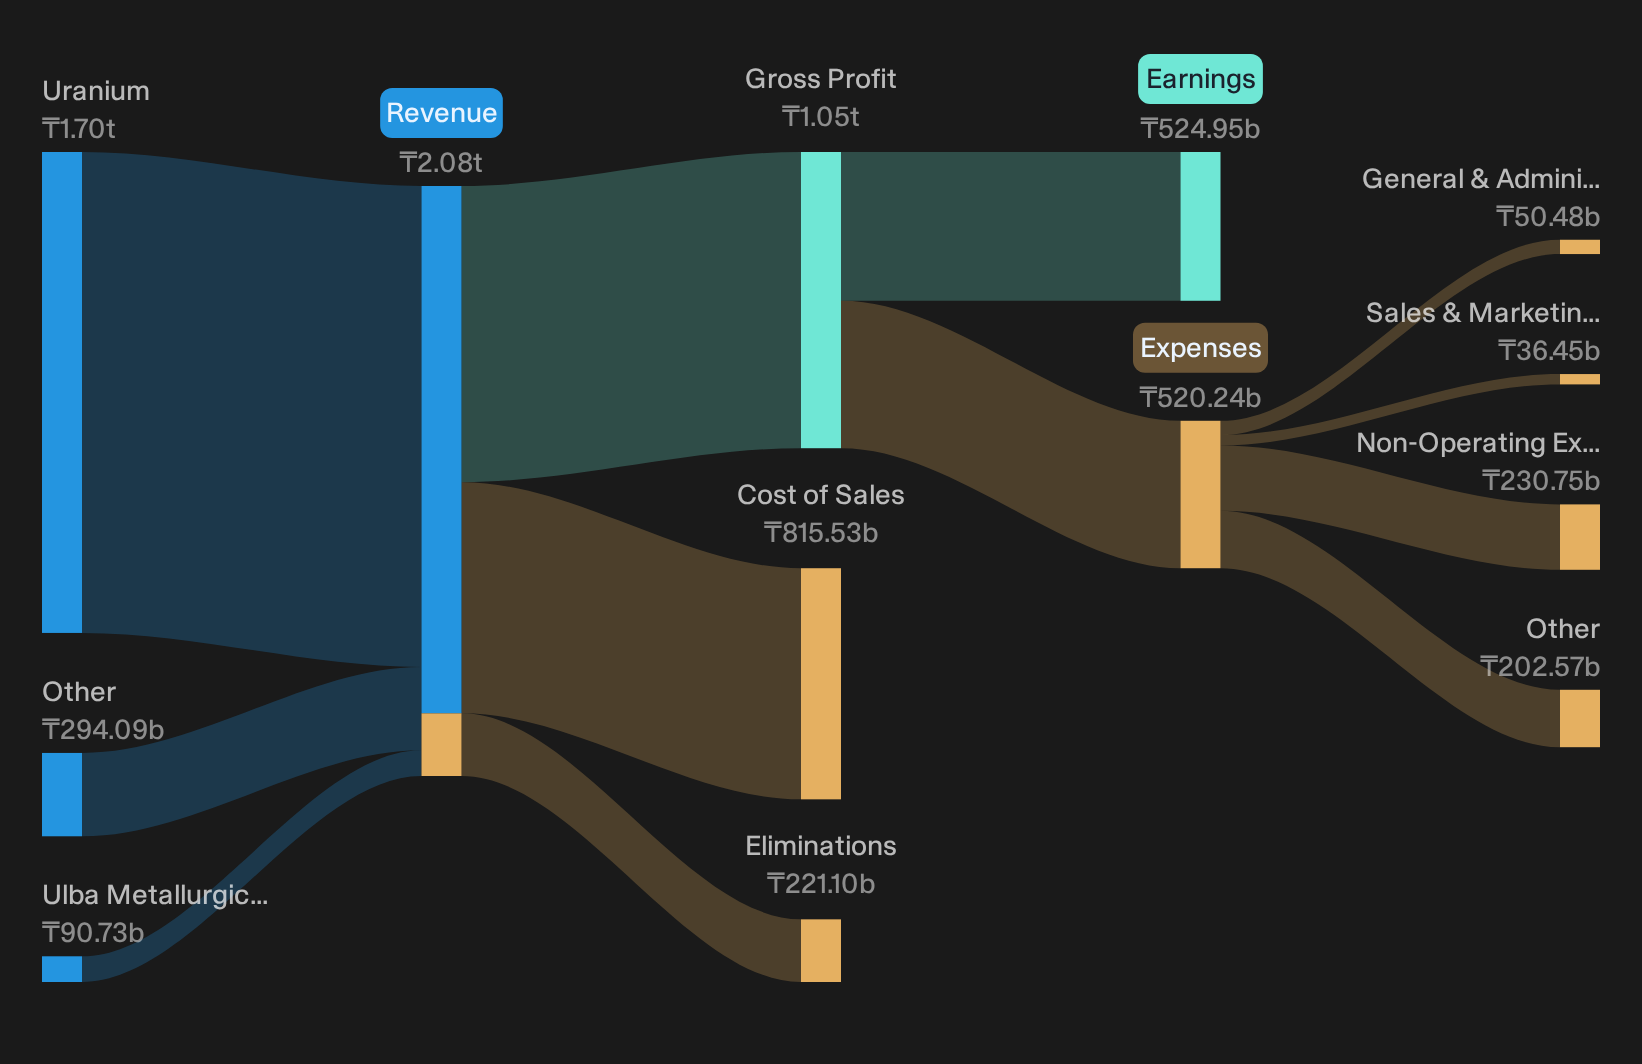
National Atomic Company Kazatomprom JSC is a uranium producer at the centre of the fuel cycle, with its uranium segment generating about KZT 1,697.0b of revenue alongside smaller contributions from Ulba Metallurgical Plant and other services, and a market value of roughly US$16.2b.
Kazatomprom provides direct exposure to the fuel that keeps nuclear reactors running, with its uranium mining and processing business playing a central role within a broader mix of metals and industrial services.
"Global structural undersupply of uranium driven by increasing nuclear build-outs, plant lifespan extensions, and a lag in bringing new projects online is supporting a multi-year demand upcycle, positioning Kazatomprom for sustained pricing power and higher sales volumes, positive for revenue and margin growth."
What matters now is how one less visible cost pressure ultimately feeds through to those margins that investors are monitoring.
That quiet pressure on profitability is exactly what the full narrative for National Atomic Company Kazatomprom JSC unpacks, showing how Kazatomprom could turn cost risks into accelerating leverage on the uranium cycle.
Centrica (LSE:CNA)
Centrica gives you exposure to nuclear-generated power through its nuclear plants and trading desk, layered onto a much broader energy and services platform. That mix matters for this screener because it blends low carbon generation with everyday utility cash flows.
Centrica is an integrated utility that supplies gas and electricity, runs energy services, trades power including nuclear output, and develops infrastructure like storage and solar. Retail activities bring in about £16.3b of revenue, optimisation adds roughly £6.0b, infrastructure contributes around £1.6b, and the group has a market value of about £6.8b.
"Centrica's expanding investment in regulated, low-carbon generation assets (notably the Sizewell C nuclear project), combined with opportunities in potential nuclear life extensions and carbon storage (Morecambe Net Zero), positions the company to capture stable, long-duration, inflation-linked returns amid accelerating decarbonization policies. This supports predictable revenue and enhanced margins over the long term."
What happens if a single assumption about how fast this low carbon build-out converts into steady cash returns quietly shifts will matter a lot.
If that timing risk is on your mind, the full narrative for Centrica lays out how Centrica could turn nuclear extensions and carbon storage into accelerating, inflation linked cash flows.

Curious About Alternative Opportunities?
Fresh ideas move first. Breakout stories, real momentum, and under the radar potential often get caught by early screens before the crowd. Do not wait, get in early.
- Target steadier compounding by reviewing hand picked 4 dividend fortresses that focus on durable cash flows while payout potential still looks attractive, before yields start dropping.
- Ride structural tech momentum by checking carefully filtered 55 AI infrastructure stocks that support data centers, chips and connectivity while these pipelines are still flying under broad market attention.
- Hunt for scarce resources by scanning curated 33 best rare earth metal stocks tied to electrification and advanced manufacturing while pricing power and supply constraints still matter most.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com