


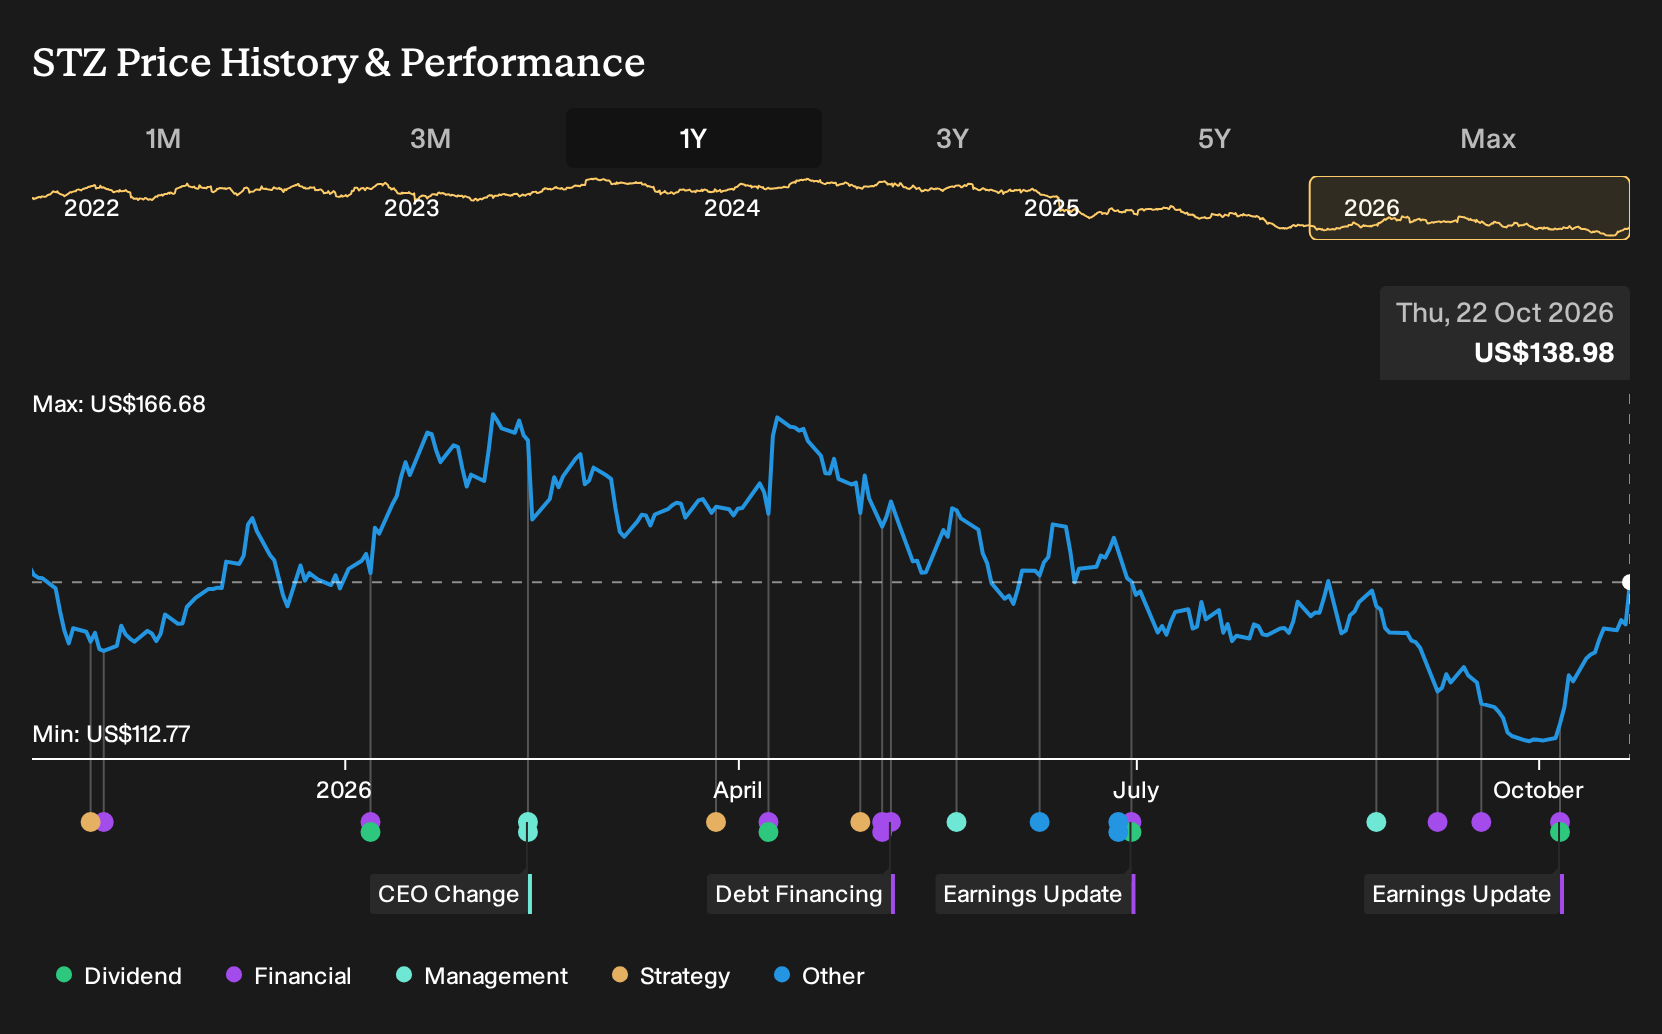
- Constellation Brands management reported that pricing is expected to be flat in fiscal 2027, while a new Veracruz facility is projected to add about $75 million of annual depreciation from fiscal 2028, creating a cost headwind despite a recent quarterly beat and beer dollar share gains.
- The tension between higher marketing investment that appears to be driving share gains and constrained pricing power highlights how future margins could be squeezed even as brand momentum continues in the beer business.
- We will now examine how Constellation Brands' margin pressure from flat pricing interacts with the existing investment narrative around its beer focus.
Scan how Constellation Brands' margin story compares with other potential opportunities by reviewing our hand-picked 29 high quality undervalued stocks, which pair solid fundamentals with more room on pricing and costs.
Constellation Brands Investment Narrative Recap
To own Constellation Brands, you need to believe the beer portfolio can keep pulling most of the weight while management holds margins together through efficiency and mix, not just higher prices. The latest update points in the opposite direction for near term relief. Flat pricing in fiscal 2027, combined with rising depreciation from Veracruz starting fiscal 2028, means less help from pricing and more pressure from costs.
The near term swing factor is whether marketing driven share gains in beer offset that squeeze. The biggest risk is that consumer demand, especially among stretched Hispanic households in key states, softens further just as cost headwinds from Veracruz and weaker Wine & Spirits profitability lean on group earnings.
The Veracruz brewery update is the clearest recent operational marker tied to this story. Management now expects about US$75 million in extra annual depreciation from fiscal 2028, which directly lifts the fixed cost base. That matters because Constellation Brands is already leaning on past US$600 million of savings in procurement, logistics and operations to support net margins.
For you as an investor, this puts more weight on execution in beer. Volume growth from brands like Modelo Especial and Pacifico, plus any eventual recovery in Wine & Spirits margins from the current 5% to 6% range, become the key offsets to that new cost load. If those pillars underperform, the margin narrative that underpins the current Constellation Brands investment case starts to look more fragile.
Constellation Brands' current earnings of US$1.9b are set against analyst forecasts that revenues will reach US$9.5b and earnings will be US$2.1b by 2029, implying 1.2% yearly revenue growth and an earnings increase of about US$0.2b from today.
Uncover how Constellation Brands' fair value indicates a 9% potential increase from its current price before investors close that valuation gap.
Exploring Other Perspectives
One alternate view focuses on Veracruz fixed costs as the real swing factor for Constellation Brands. The most cautious analysts were already modeling revenues of about US$8.8b and earnings near US$1.7b by 2029, well below consensus. That more pessimistic margin story could shift again after this latest flat pricing update, so compare both narratives yourself.
Explore 6 other Constellation Brands fair value estimates, including one that suggests there may be as much as 29% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Constellation Brands research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Constellation Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Constellation Brands' overall financial health at a glance.
Looking For More Ideas Beyond Constellation Brands?
If the Constellation Brands story leaves you weighing risk against reward, it can help to line it up next to other businesses with different income profiles, balance sheets, and dividend records. The Simply Wall St Screener lets you do exactly that in a structured way.
- For investors who want potential upside without ignoring quality, scan a carefully filtered set of value opportunities through 29 high quality undervalued stocks that pair earnings strength with room for sentiment to catch up.
- If capital preservation and steadier profiles matter more to you, focus on 30 resilient stocks with low risk scores and narrow in on businesses that score well on financial resilience and volatility.
- When you want to broaden the watchlist with companies that have cleaner finances, use the list of solid balance sheet and fundamentals (26 results) to surface candidates with relatively strong balance sheets and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com