


Linde (NasdaqGS:LIN) has just expanded its long-term industrial gas supply to Tata Steel’s Kalinganagar complex, doubling on-site capacity and tying the business more closely to India’s growing steel and regional merchant gas demand.
Recent trading reflects that backdrop. Linde’s share price has gained 8.7% over the past month and 18.9% year to date, while its 1 year total shareholder return of 16.0% and 5 year total shareholder return of 71.1% point to momentum that has built steadily rather than in short bursts.
Scan beyond Linde’s recent run and see how other industrial heavyweights with strong cash generation and global footprints line up in the list of solid balance sheet and fundamentals (26 results).
Linde has already rewarded patience this year, yet the Tata Steel expansion and long-term contract backlog keep reshaping the story. Has the recent surge priced that in, or does the valuation still leave meaningful upside on the table?
Most Popular Narrative: 6% Undervalued
Linde closed at $510.36, compared with the most followed narrative fair value of $544.40. This frames the current project build out and contract wins through a slightly undervalued lens rather than an overheated one.
Linde's position supplying ultra high purity gases to large advanced node semiconductor complexes in Arizona and Taiwan, backed by about US$1.8b of recent investment and strong AI related electronics demand, points to rising project start ups. These can convert the current backlog into higher sale of gas revenue and earnings over time.
See why 119 investors see Linde as 6% undervalued.
Result: Fair Value of $544 (UNDERVALUED)
Still, Linde’s story can change quickly if European industrial demand weakens further or the troubled U.S. homecare unit continues to weigh on regional profitability.
Find out about the key risks to this Linde narrative.
Another View On Linde’s Valuation
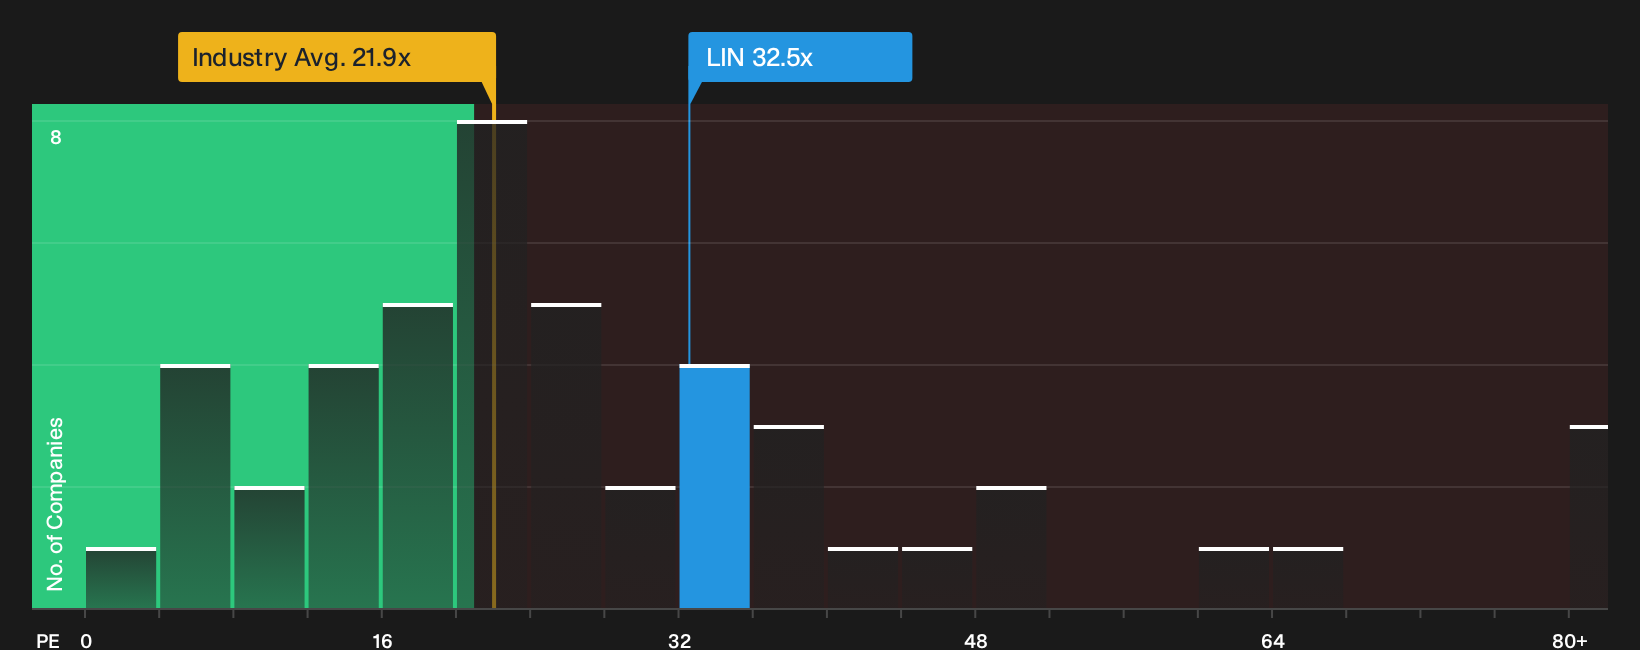
The popular narrative frames Linde as about 6% undervalued on a fair value of $544, yet the current P/E of 32.5x tells a tougher story. That ratio sits above the US Chemicals industry on 21.9x, peers on 31.4x and a fair ratio of 23.2x, which points to meaningful valuation risk if sentiment cools.
Put simply, investors are paying a premium price for a business already forecast to grow earnings at 9.4% a year, so the key question is whether that premium feels justified to you or stretches comfort.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Linde feels familiar, consider reviewing the full picture of data yourself. The easiest way to weigh both sides is to start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Linde?
Use the Simply Wall Street Screener to quickly surface fresh opportunities that fit your style before the crowd starts paying attention to them.
- Target potential mispricing by scanning for companies on our 29 high quality undervalued stocks that combine solid fundamentals with prices that lag their underlying strength.
- Build a steadier income stream by focusing on businesses in the 6 dividend fortresses that pair higher yields with durable cash generation.
- Prioritise resilience by filtering for companies in the 30 resilient stocks with low risk scores that show stronger balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com