


Japanese interest rates are finally moving, and that shift is quietly reshaping the ground under the country’s financial stocks. A central bank that now sees inflation near its 2% target can reward patient investors or catch unprepared holders off guard. This article walks through three Japanese financial stocks exposed to that policy story and explains where higher borrowing costs could help, hurt, or simply reset expectations.
The three stocks covered below are only a sample of the idea, and the full screen on Simply Wall St surfaces 9 more Japanese financial groups with equally detailed rate and profitability stories that are not discussed here. To see the broader field and identify which lenders or diversified financiers line up best with your own thesis, head straight to the Japanese Financials (Banks and Diversified Financials) screener and analyze the full set of candidates through your own lens.
Mebuki Financial GroupInc (TSE:7167)
Mebuki Financial GroupInc is a regional banking group in Japan that runs deposits, lending, securities and related services. Its ¥377.6b of revenue comes entirely from its core banking business. The group is fully Japan focused and has a market value of about ¥1.39t.
Mebuki Financial GroupInc offers exposure to Japanese regional banking at scale, with all ¥377.6b of revenue tied to domestic banking and a market cap around ¥1.39t that fits the screener’s size and quality filters. Investors watching rising local rates may focus most on what happens when one key pressure on lending spreads shifts again.
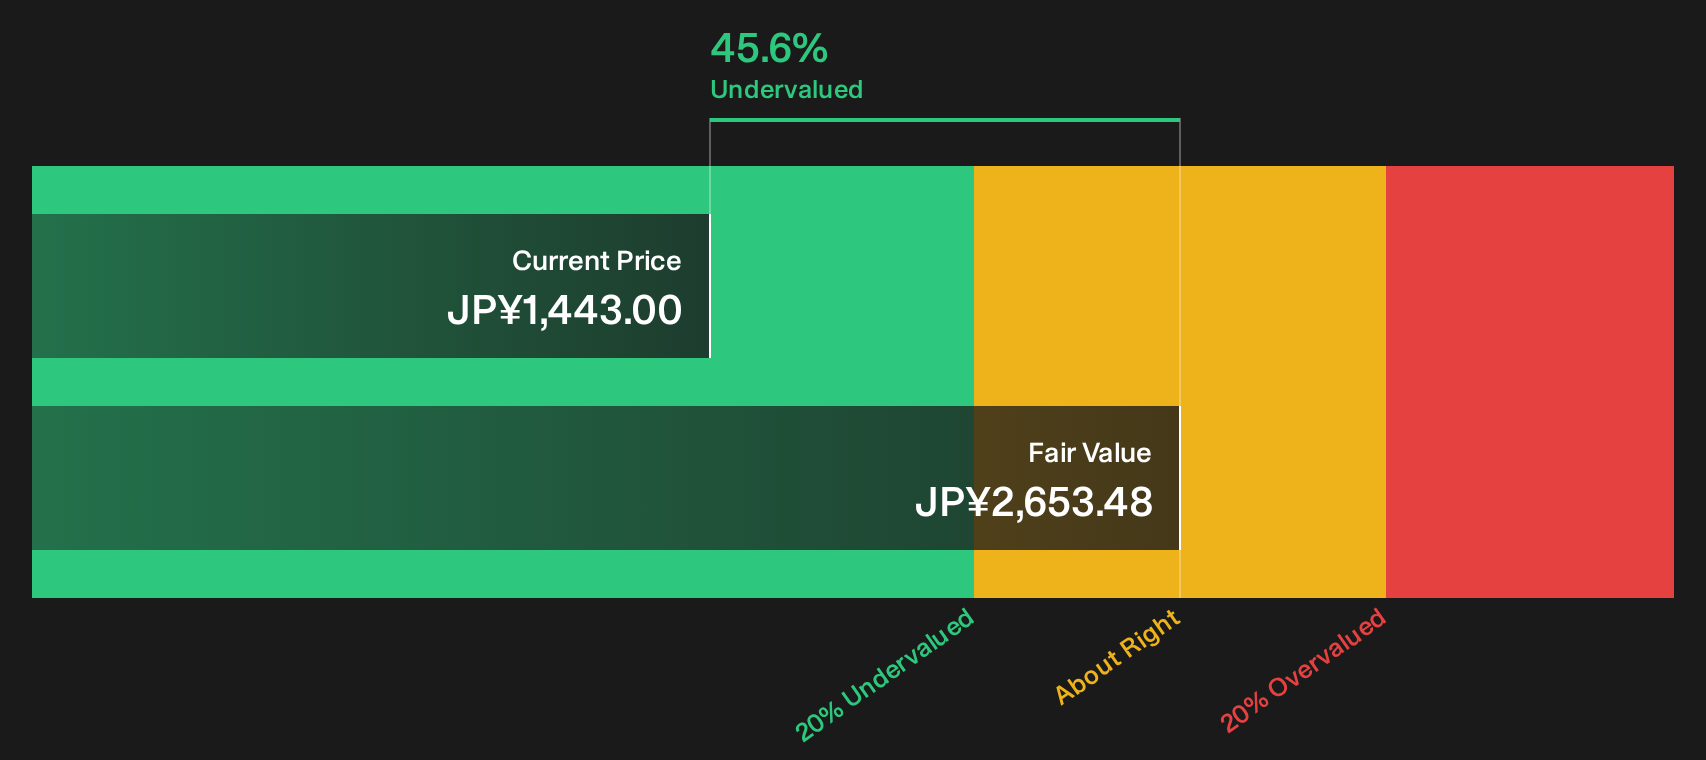
When that pressure finally shifts, tap the DCF valuation analysis for Mebuki Financial GroupInc to see how rate moves could be masking what Mebuki Financial GroupInc is really worth.
Hirogin Holdings (TSE:7337)
Hirogin Holdings is a Hiroshima based bank holding group that fits the Japanese Financials theme through its focus on traditional lending and deposits. Around ¥183.1b comes from the Banking segment and ¥23.4b from Leasing, with a market value near ¥633.8b.
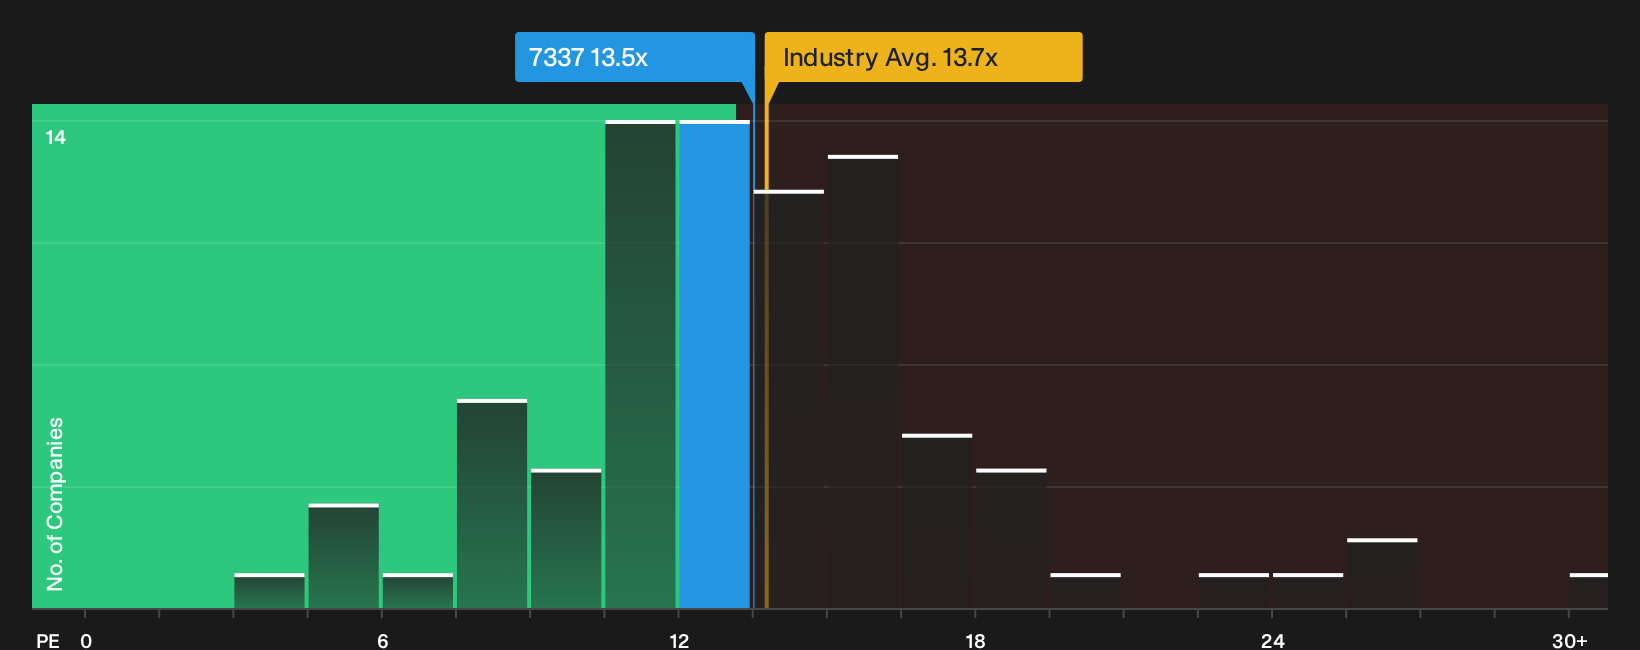
Hirogin Holdings ties closely to domestic rate moves, with traditional banking generating most of its ¥206.1b in segment revenue and a P/E of 13.5x that sits just under the broader Japanese market. Investors watching the Bank of Japan’s tightening path may focus on how changes in policy could affect pressures on net interest margins.
Those shifting pressures on net interest margins make it a good moment to review the analysis report for Hirogin Holdings and see what the market might be missing.
Nishi-Nippon Financial Holdings (TSE:7189)
Nishi-Nippon Financial Holdings is a Fukuoka based bank group in the Japanese Financials screener, with core banking bringing in about ¥199.8b, other operations ¥46.6b and an unallocated adjustment of ¥23.1b, all from Japan, and a market value around ¥605.6b.
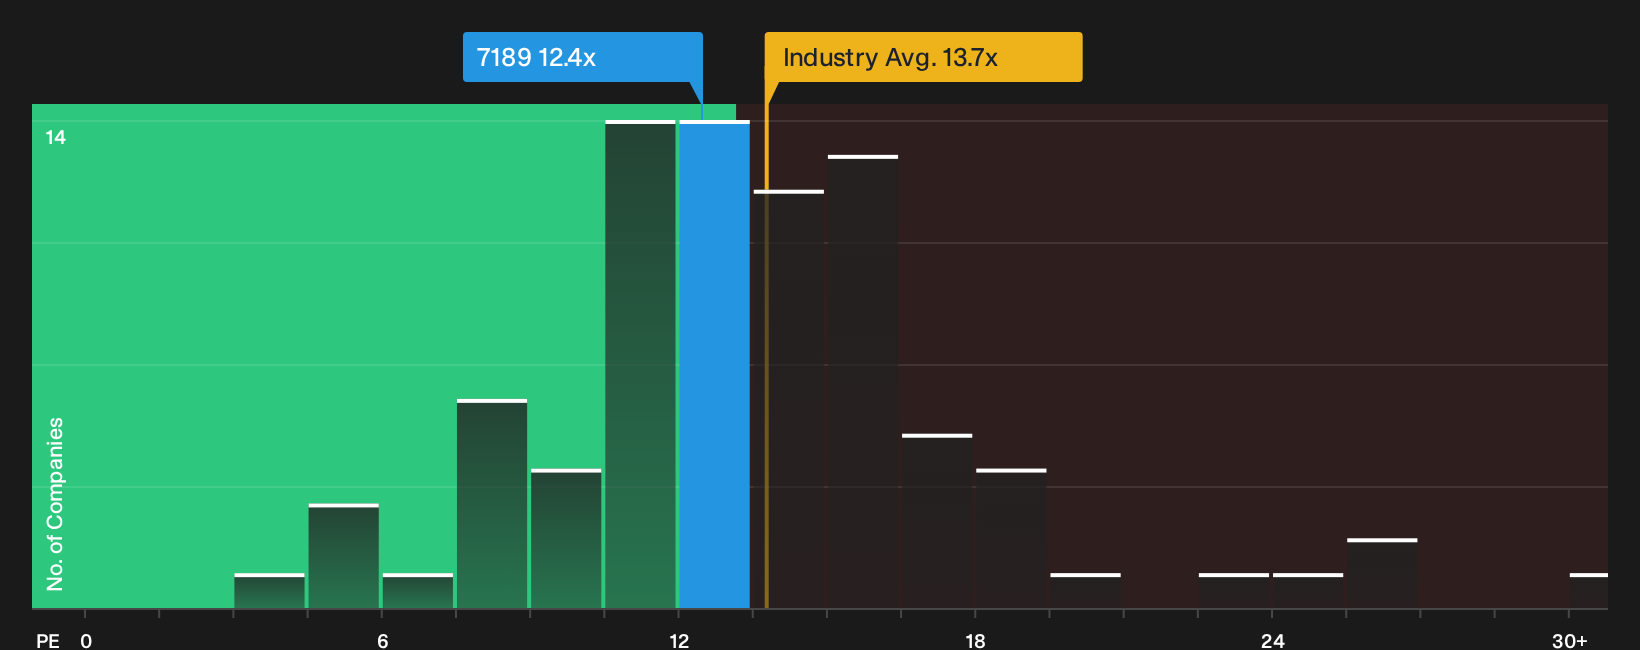
Nishi-Nippon Financial Holdings lines up cleanly with the screen’s focus on sizeable domestic lenders that screen well on value and balance sheet quality, with a P/E of 12.4x below both peers and the wider Japanese banks group and trading close to estimated fair value. That situation places considerable emphasis on what happens when one previously unseen pressure on lending economics shifts again.
If that pressure on lending economics is really shifting, review the 4 key rewards and 2 important warning signs to see where Nishi-Nippon Financial Holdings could be mispriced on both strength and risk.
Seeking Alternatives Before Everyone Else
Fresh ideas move first. Once momentum builds, quiet opportunities get caught, re-rated, or start flying as attention floods in. Scan these under the radar lists now and review them while they are still less widely followed.
- Target dependable income while prices are still resetting by reviewing the 29 dividend fortresses to see higher yield opportunities before they attract broader attention.
- Hunt for resilient balance sheets and steady fundamentals by working through the list of solid balance sheet and fundamentals (23 results) curated to surface sturdier businesses while market focus is still elsewhere.
- Pursue early stage pricing power by checking the 72 high quality undiscovered gems designed to spotlight quality operators that remain under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com