


Over the last 7 days, the United States market has experienced a slight decline of 1.2%, although it remains up by 11% over the past year, with earnings forecasted to grow by 17% annually. In this context, identifying undervalued stocks can be particularly appealing as they may offer potential opportunities for growth in an otherwise fluctuating market environment.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Textron (TXT) | $78.04 | $147.32 | 47% |
| Pediatrix Medical Group (MD) | $29.55 | $58.85 | 49.8% |
| Old Second Bancorp (OSBC) | $24.71 | $48.45 | 49% |
| Noah Holdings (NOAH) | $7.01 | $13.22 | 47% |
| Jones Lang LaSalle (JLL) | $312.55 | $610.10 | 48.8% |
| Halliburton (HAL) | $33.19 | $65.52 | 49.3% |
| ConnectOne Bancorp (CNOB) | $32.82 | $64.51 | 49.1% |
| Atlantic Union Bankshares (AUB) | $40.10 | $78.92 | 49.2% |
| Artisan Partners Asset Management (APAM) | $34.40 | $64.60 | 46.7% |
| Amazon.com (AMZN) | $250.38 | $471.23 | 46.9% |
Here's a peek at a few of the choices from the screener.
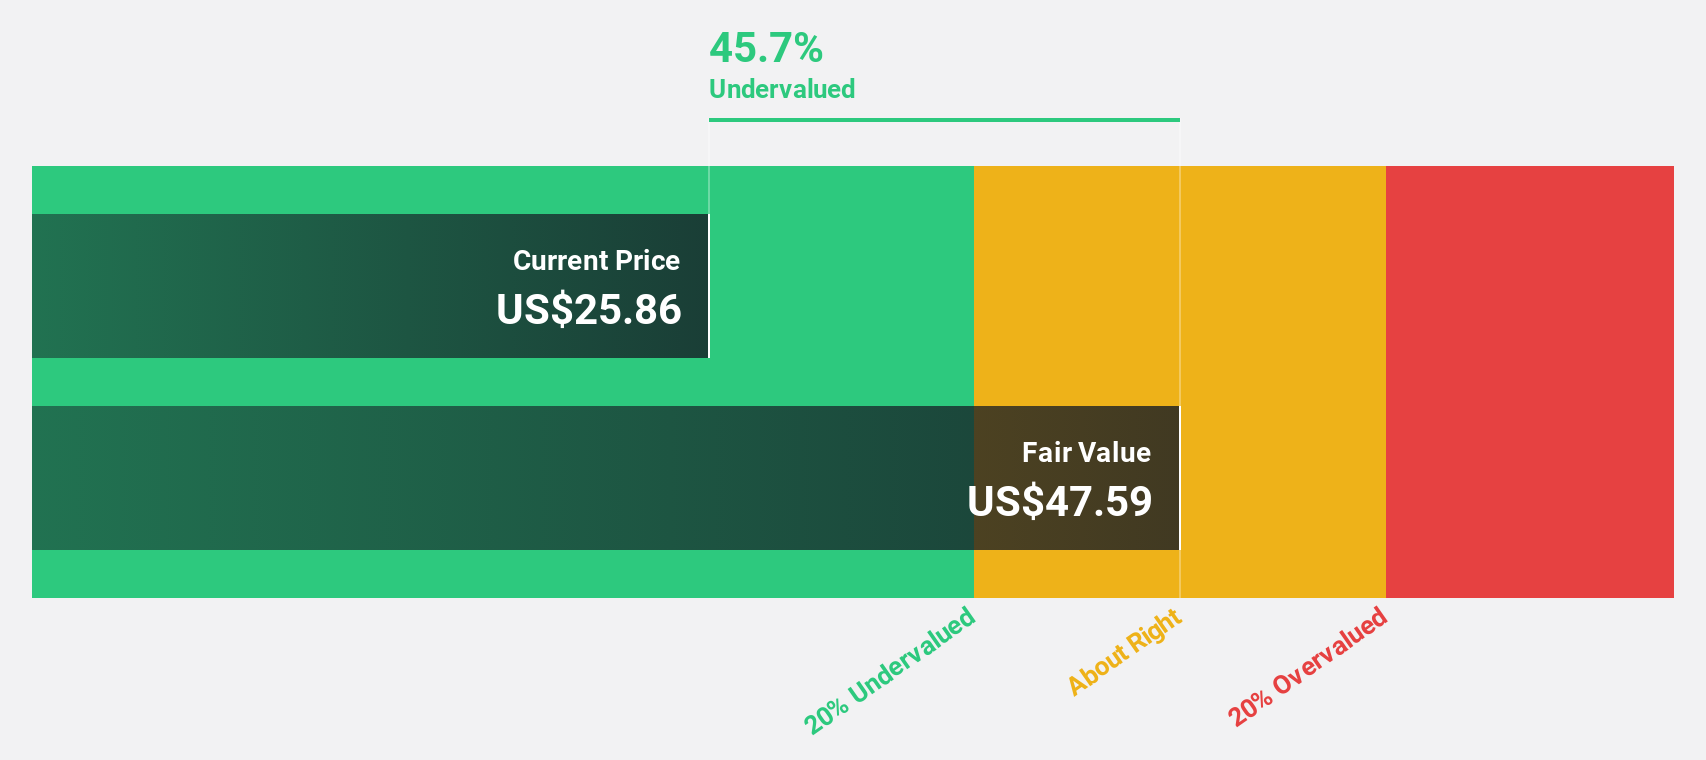
Associated Banc-Corp (ASB)
Overview: Associated Banc-Corp is a bank holding company offering a range of banking and nonbanking products and services to individuals and businesses across Wisconsin, Illinois, Missouri, Texas, and Minnesota, with a market cap of $5.44 billion.
Operations: The company's revenue segments include Community, Consumer, and Business generating $1.00 billion, Corporate and Commercial Specialty contributing $565.69 million, and Risk Management and Shared Services accounting for -$10.02 million.
Estimated Discount To Fair Value: 43.2%
Associated Banc-Corp is trading significantly below its estimated future cash flow value, indicating potential undervaluation. Despite slower forecasted revenue growth compared to the US market, its earnings are expected to grow annually by 12.65%. Recent financials show increased net income and interest income year-over-year, though there has been significant insider selling recently. The company maintains a reliable dividend yield of 3.22%, enhancing its appeal as an investment option based on cash flows.
- In light of our recent growth report, it seems possible that Associated Banc-Corp's financial performance will exceed current levels.
- Click here and access our complete balance sheet health report to understand the dynamics of Associated Banc-Corp.
Dover (DOV)
Overview: Dover Corporation offers a wide range of equipment, components, consumables, aftermarket parts, software and digital solutions, and support services globally with a market cap of $26.91 billion.
Operations: The company's revenue segments include equipment and components ($2.50 billion), consumable supplies ($1.75 billion), aftermarket parts ($1.25 billion), software and digital solutions ($850 million), and support services ($650 million).
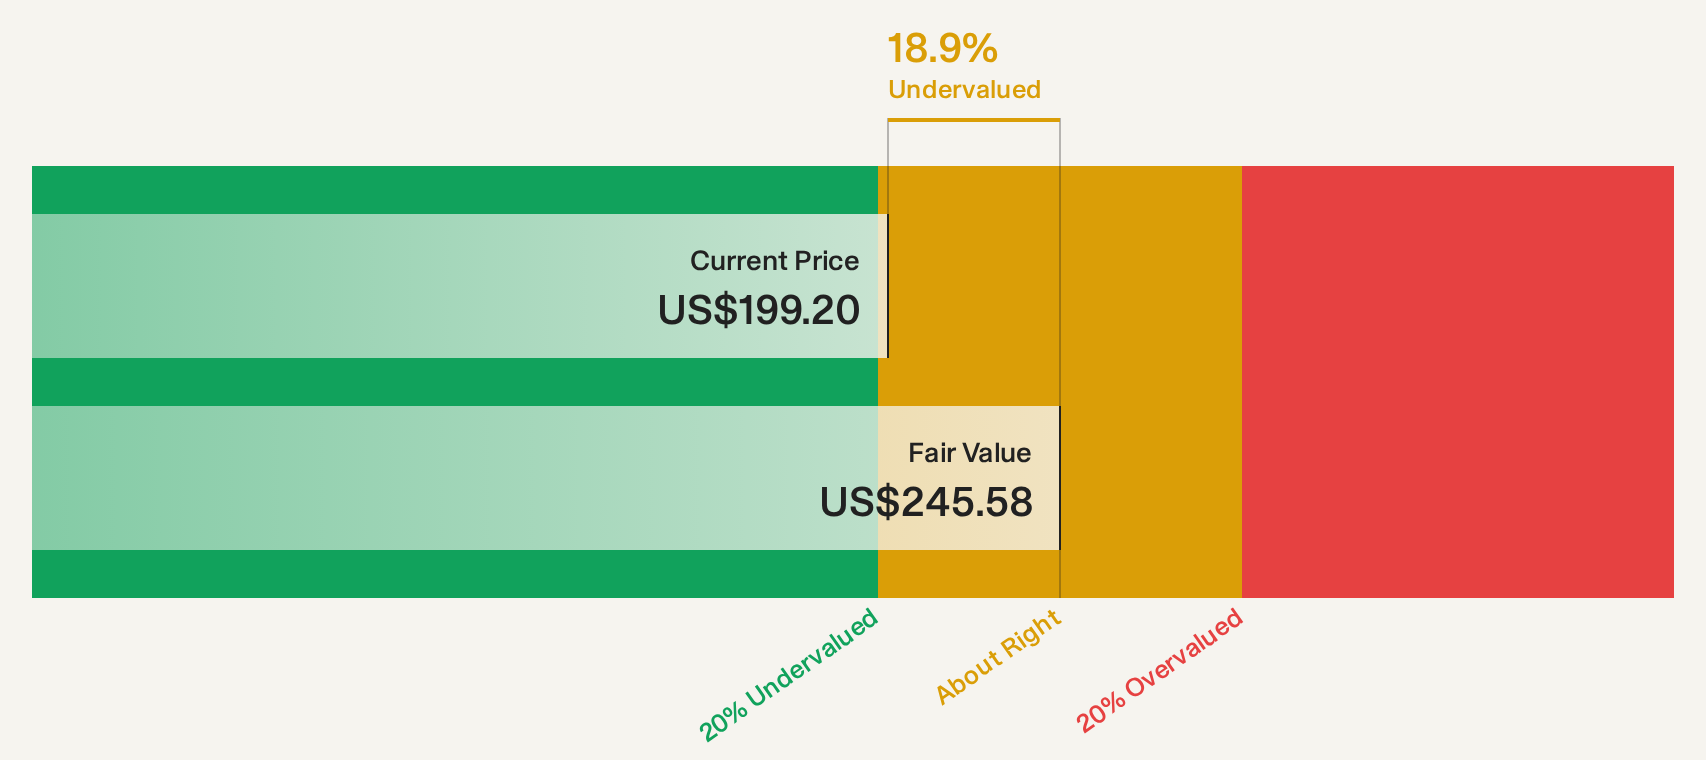
Estimated Discount To Fair Value: 20.4%
Dover is trading at US$195.49, significantly below its estimated future cash flow value of US$245.56, suggesting potential undervaluation. Recent earnings reports show improved financial performance with increased sales and net income year-over-year. However, its forecasted revenue and earnings growth are slower than the broader market averages. Despite these constraints, Dover's ongoing commitment to innovation and efficiency in product offerings could support future cash flow generation and investment appeal.
- Our earnings growth report unveils the potential for significant increases in Dover's future results.
- Dive into the specifics of Dover here with our thorough financial health report.
Lockheed Martin (LMT)
Overview: Lockheed Martin Corporation is an aerospace and defense company involved in the research, design, development, manufacture, integration, and sustainment of technology systems and services globally with a market cap of approximately $127.28 billion.
Operations: Lockheed Martin's revenue segments include Aeronautics at $27.20 billion, Missiles and Fire Control at $11.91 billion, Rotary and Mission Systems at $17.23 billion, and Space at $12.04 billion.
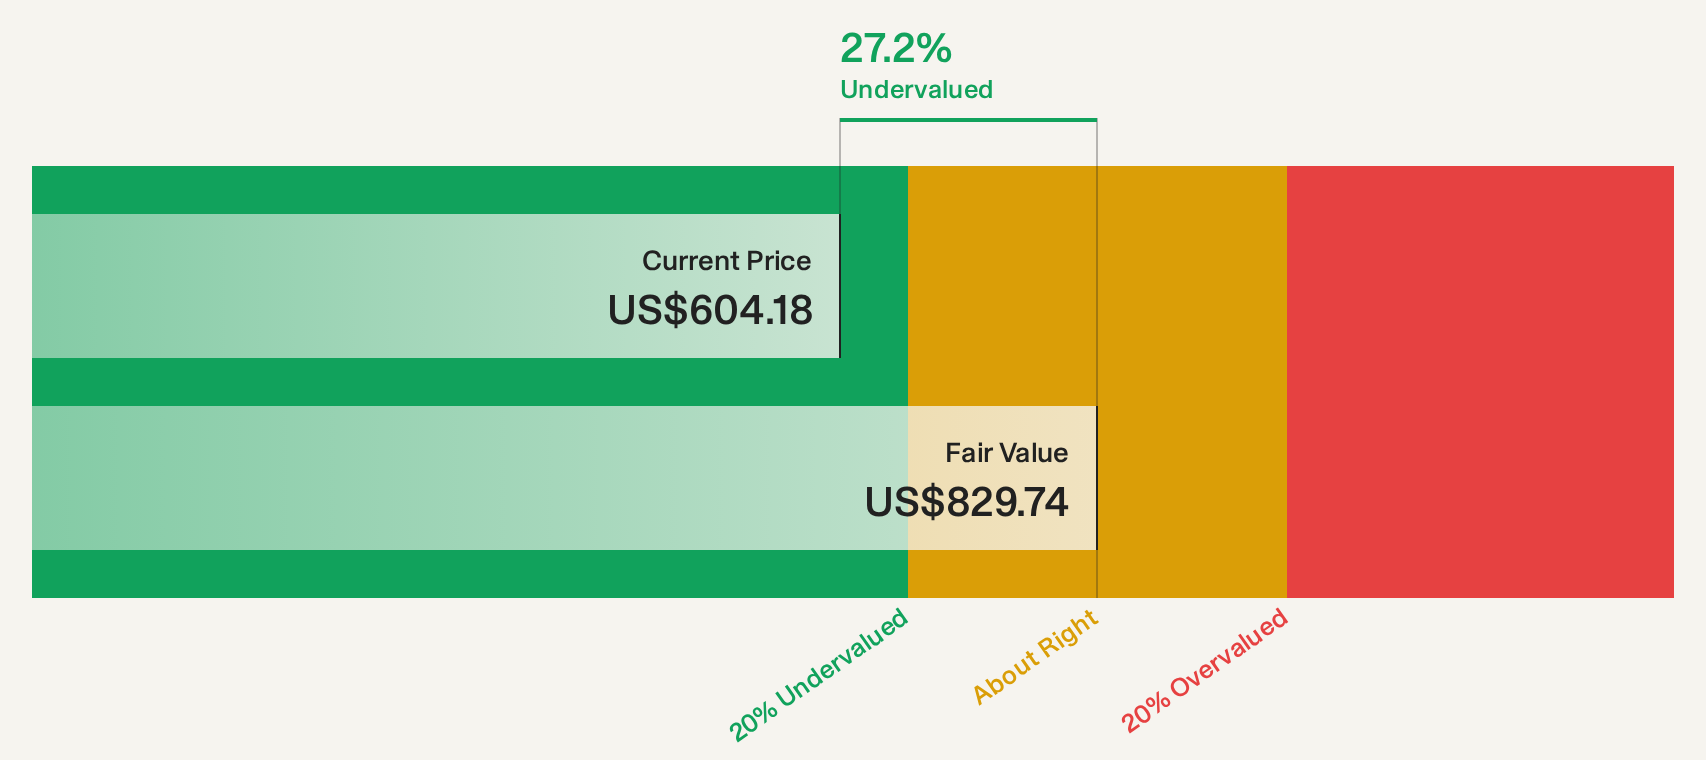
Estimated Discount To Fair Value: 26.7%
Lockheed Martin is trading at US$589.91, significantly below its estimated future cash flow value of US$804.43, highlighting potential undervaluation. Despite high debt levels and slower forecasted revenue and earnings growth compared to the market, Lockheed Martin's robust financial position is bolstered by recent earnings guidance upgrades and substantial multiyear contracts like the F-35 program. These factors, combined with a reliable dividend yield of 2.34%, underscore its strong cash flow prospects amidst industry challenges.
- Insights from our recent growth report point to a promising forecast for Lockheed Martin's business outlook.
- Click here to discover the nuances of Lockheed Martin with our detailed financial health report.
Make It Happen
- Dive into all 95 of the Undervalued US Stocks Based On Cash Flows we have identified here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com