


Keysight Technologies (KEYS) just landed Korea Testing Laboratory as a customer for its New Radio Non Terrestrial Network test gear, putting satellite enabled 5G validation in sharper focus for investors.
That KTL win lands during a choppy spell for Keysight Technologies, with the 1-day share price return down 8.74% and the 30-day share price return down 10.31%, even though the year to date share price return is up 50.79% and the 3-year total shareholder return sits at 160.34%. This mix points to strong longer term momentum despite the recent pullback as the market reassesses growth prospects and risk around its test and measurement portfolio.
Scan other testing and AI infrastructure plays that are moving on similar themes to Keysight Technologies by checking the hand-picked 55 AI infrastructure stocks.
Keysight Technologies has just dropped more than 8% in a day after a long run that lifted the shares sharply over three years. Does that move already offer a fair entry, or does patience still make more sense once valuation is on the table next?
Most Popular Narrative: 25% Undervalued
Keysight Technologies closed at $311.52, while the most followed narrative pegs fair value at $415.08. The recent slide still leaves a sizable valuation gap according to that framework, which is built on a discount rate of 8.95%.
Expansion of software, simulation and recurring service offerings is advancing, with software and services reaching roughly 33% of Q3 2026 revenue, annual recurring revenue at 24% of mix and the simulation business expected to exceed US$0.5b in 2026. This supports high gross margins near the upper 60s percentage range and contributes to operating margin strength.
See why 20 investors see Keysight Technologies as 25% undervalued.
Result: Fair Value of $415.08 (UNDERVALUED)
Still, that upbeat Keysight Technologies narrative can crack if supply constraints delay another US$100m of orders, or if Spirent integration delivers lower cost synergies than expected.
Find out about the key risks to this Keysight Technologies narrative.
Another View: Keysight Technologies Through The P/E Lens
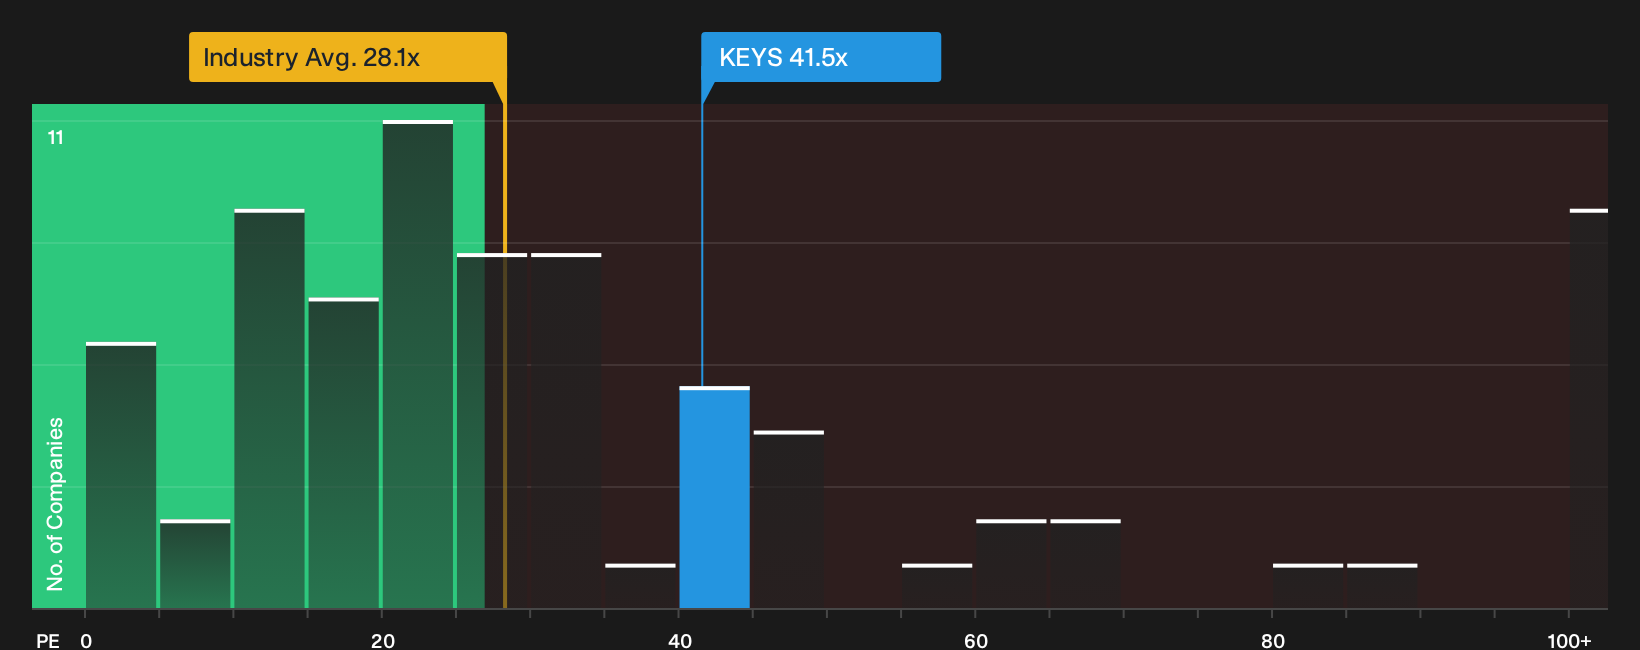
A second look using plain P/E math paints a less friendly picture for Keysight Technologies. The stock trades at 41.5x earnings, above both the US Electronic industry on 28.1x and its peer group average on 38.4x, and even ahead of its own 35.3x fair ratio.
That spread suggests investors are already paying a premium multiple, which can limit upside if expectations cool or earnings progress stalls. The question is whether you see that gap as justified quality or just added valuation risk if sentiment turns.
For a deeper breakdown of how this earnings multiple stacks up against history, peers and the fair ratio that the market could move toward next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Keysight Technologies can spark debate, so move quickly, review the underlying data, and then weigh the 4 key rewards and 1 important warning sign against your own expectations.
Looking for more investment ideas beyond Keysight Technologies?
If Keysight Technologies has your attention, do not stop your research here. Broaden your watchlist with other targeted opportunities that match your risk and return style.
- Target potential bargains by scanning a curated pool of quality companies trading below assessed value through the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with robust payouts using the 6 dividend fortresses.
- Dial down portfolio stress by focusing on sturdier balance sheets and resilient fundamentals with the list of solid balance sheet and fundamentals (26 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com