


UGI (UGI) is back on watch after a recent share-price move that left the stock up 4.8% over the past month and 3.4% over the past 3 months.
Momentum for UGI has been quietly rebuilding, with a 7 day share price return of 2.9%, a 1 month share price gain of 4.8%, and a 1 year total shareholder return of 20.7% that reflects both price moves and dividends.
Scan how UGI’s recent momentum compares with other potential breakouts on our hand picked list of 29 high quality undervalued stocks.
That kind of steady climb can signal either growing confidence in UGI’s underlying cash generation or a short term swing in sentiment. The valuation now needs to explain which story fits best.
Most Popular Narrative: 11% Undervalued
UGI last closed at $38.61, while the most followed narrative anchors fair value at $43.25. That gap frames the recent momentum as investors weigh rate visibility, LPG cash flows and the takeover offer against execution and regulatory risk.
The main thing that has to go right is continued execution on AmeriGas and UGI International as cash-generative LPG platforms, alongside regulatory and capital allocation decisions that keep UGI’s Pennsylvania gas utilities investing in modernization and safety.
UGI International’s high free cash flow LPG operations, which have produced more than US$800 million of free cash flow over three years with mid teens returns on capital and low to mid 20s EBITDA margins, together with the completed divestiture of seven smaller markets that brought in about US$215 million of cash, can support group deleveraging and potentially lift net margins and cash flow conversion.
What is behind 34 investors see UGI as 11% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, the narrative around UGI can shift quickly if the Pennsylvania safety case drives higher unplanned costs or if Midstream and Marketing earnings remain weaker for a longer period.
Find out about the key risks to this UGI narrative.
Another View on UGI’s Valuation
While the prevailing narrative leans on the $43.25 fair value tied to analyst targets and earnings power, the Simply Wall St DCF model presents a more conservative perspective. From that viewpoint, UGI at $38.61 appears overvalued relative to an estimated future cash flow value of $14.29. This raises a simple question: which signal do you trust more, earnings strength or cash generation?
Look into how the SWS DCF model arrives at its fair value.
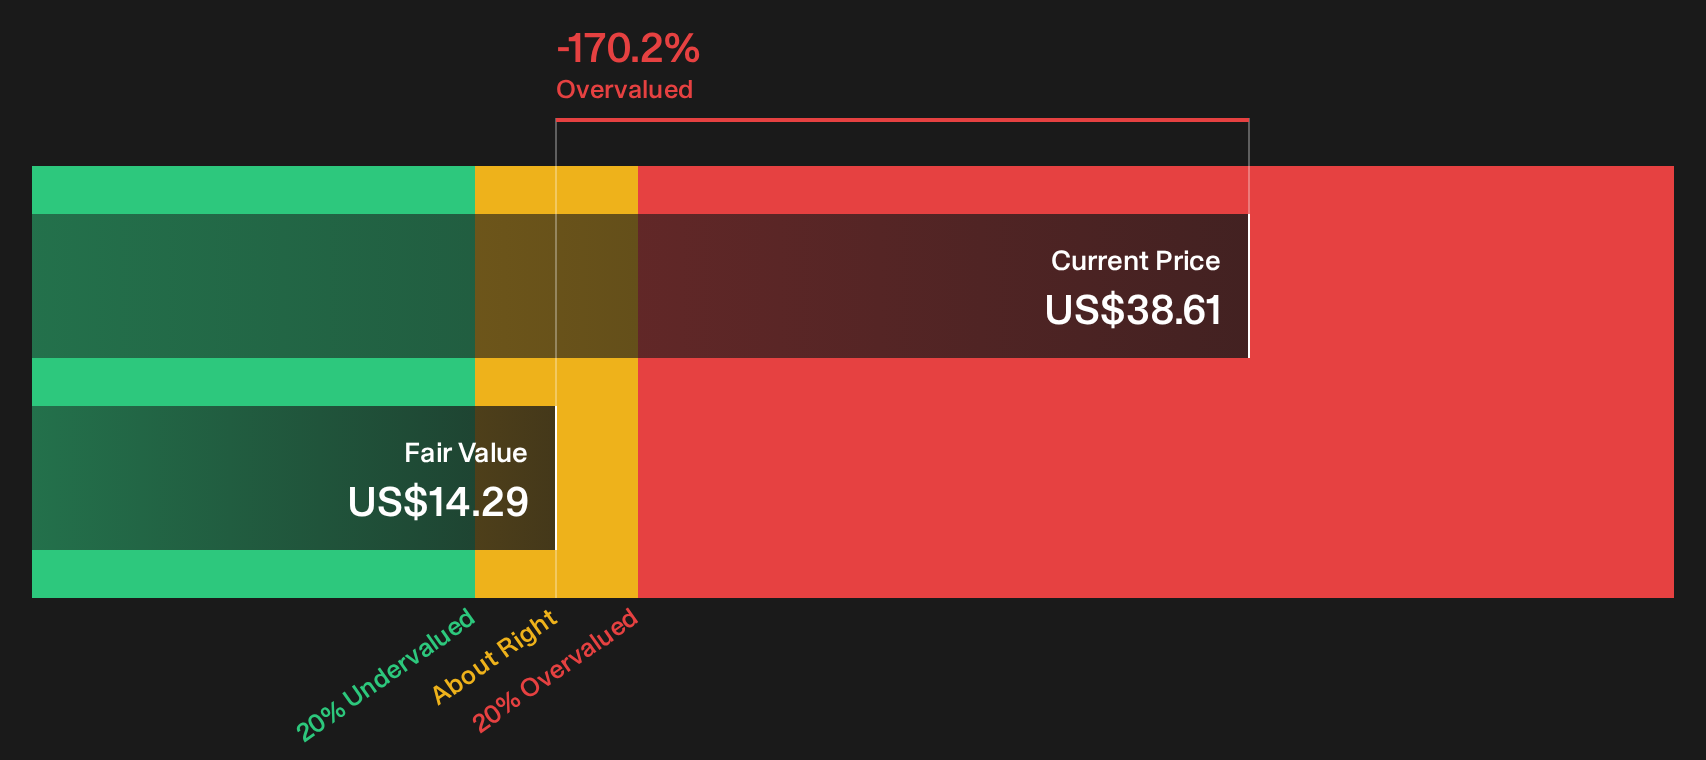
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UGI for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on UGI so far. If you want to move quickly and form your own view, start with the balance of 4 key rewards and 2 important warning signs.
Looking for more UGI investment ideas?
If UGI has sharpened your focus on valuation and momentum, do not stop here. Use curated screeners to source fresh candidates before they move without you.
- Target potential mispricings by reviewing companies on the 29 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- Strengthen your income playbook by scanning the 6 dividend fortresses and spotting payouts that aim for resilience as well as yield.
- Prioritise resilience first by working through the 30 resilient stocks with low risk scores and focusing on businesses with steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com