


Bozeman, Montana-based Fair Isaac Corporation (FICO) is a global data analytics and software company best known for developing the FICO Score, a widely used measure of consumer credit risk in the United States. The company has a market capitalization of $17.2 billion and provides AI-powered analytics, fraud detection, and decision-management software that helps banks, lenders, insurers, and other businesses assess creditworthiness, manage risk, prevent fraud, and automate business decisions.
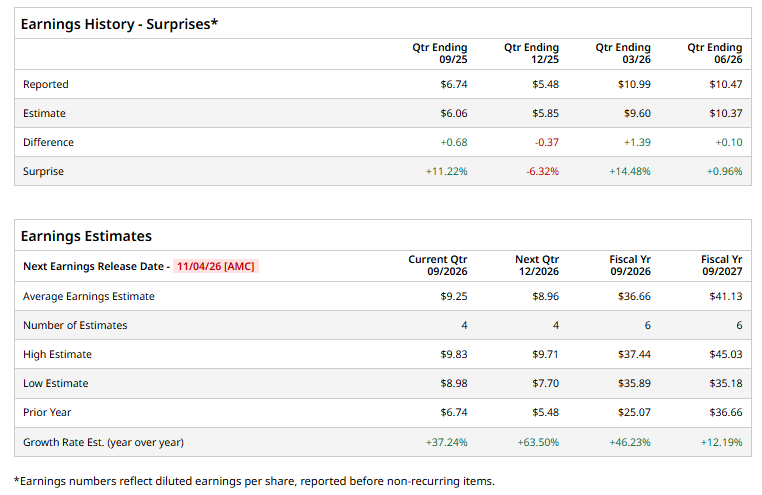
FICO is expected to release its Q4 2026 earnings on Wednesday, Nov. 4, after the market closes. Ahead of the event, analysts expect the company’s EPS to be $9.25 on a diluted basis, up 37.2% from $6.47 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in three of its last four quarters, while missing on one occasion.
For fiscal 2026, analysts project the company’s EPS to be $36.66, up 46.2% from $25.07 in fiscal 2025. Moreover, its EPS is expected to rise by roughly 12.2% year over year to $41.13 in fiscal 2027.
FICO stock has declined 47.7% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 14.4% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 27.7% rise during the same time frame.
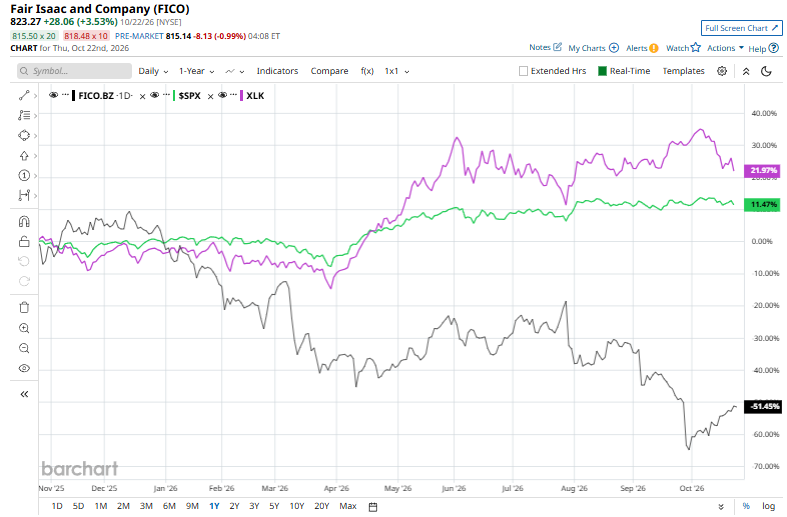
On Sept. 29, Fair Isaac shares plunged 20% in premarket trading after the Federal Housing Finance Agency announced a unified mortgage pricing grid that would place VantageScore on equal footing with FICO Classic. The selloff intensified after TransUnion committed to keeping VantageScore 4.0 mortgage pricing at $0.99 per score through December 2028, potentially increasing competitive pressure on FICO’s mortgage credit-scoring business.
Analysts are moderately bullish about FICO, with the stock having a “Moderate Buy” rating overall. Among the 21 analysts covering the stock, opinions include nine “Strong Buy,” three “Moderate Buy,” six “Hold,” and three “Strong Sell.” FICO’s average analyst price target is $1,035.95, indicating an upside of 25.9% from the current level.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.